Blog
Insights and news from the ATOM Mobility team
We started our blog to share free valuable information about the mobility industry: inspirational stories, financial analysis, marketing ideas, practical tips, new feature announcements and more.
We started our blog to share free valuable information about the mobility industry: inspirational stories, financial analysis, marketing ideas, practical tips, new feature announcements and more.
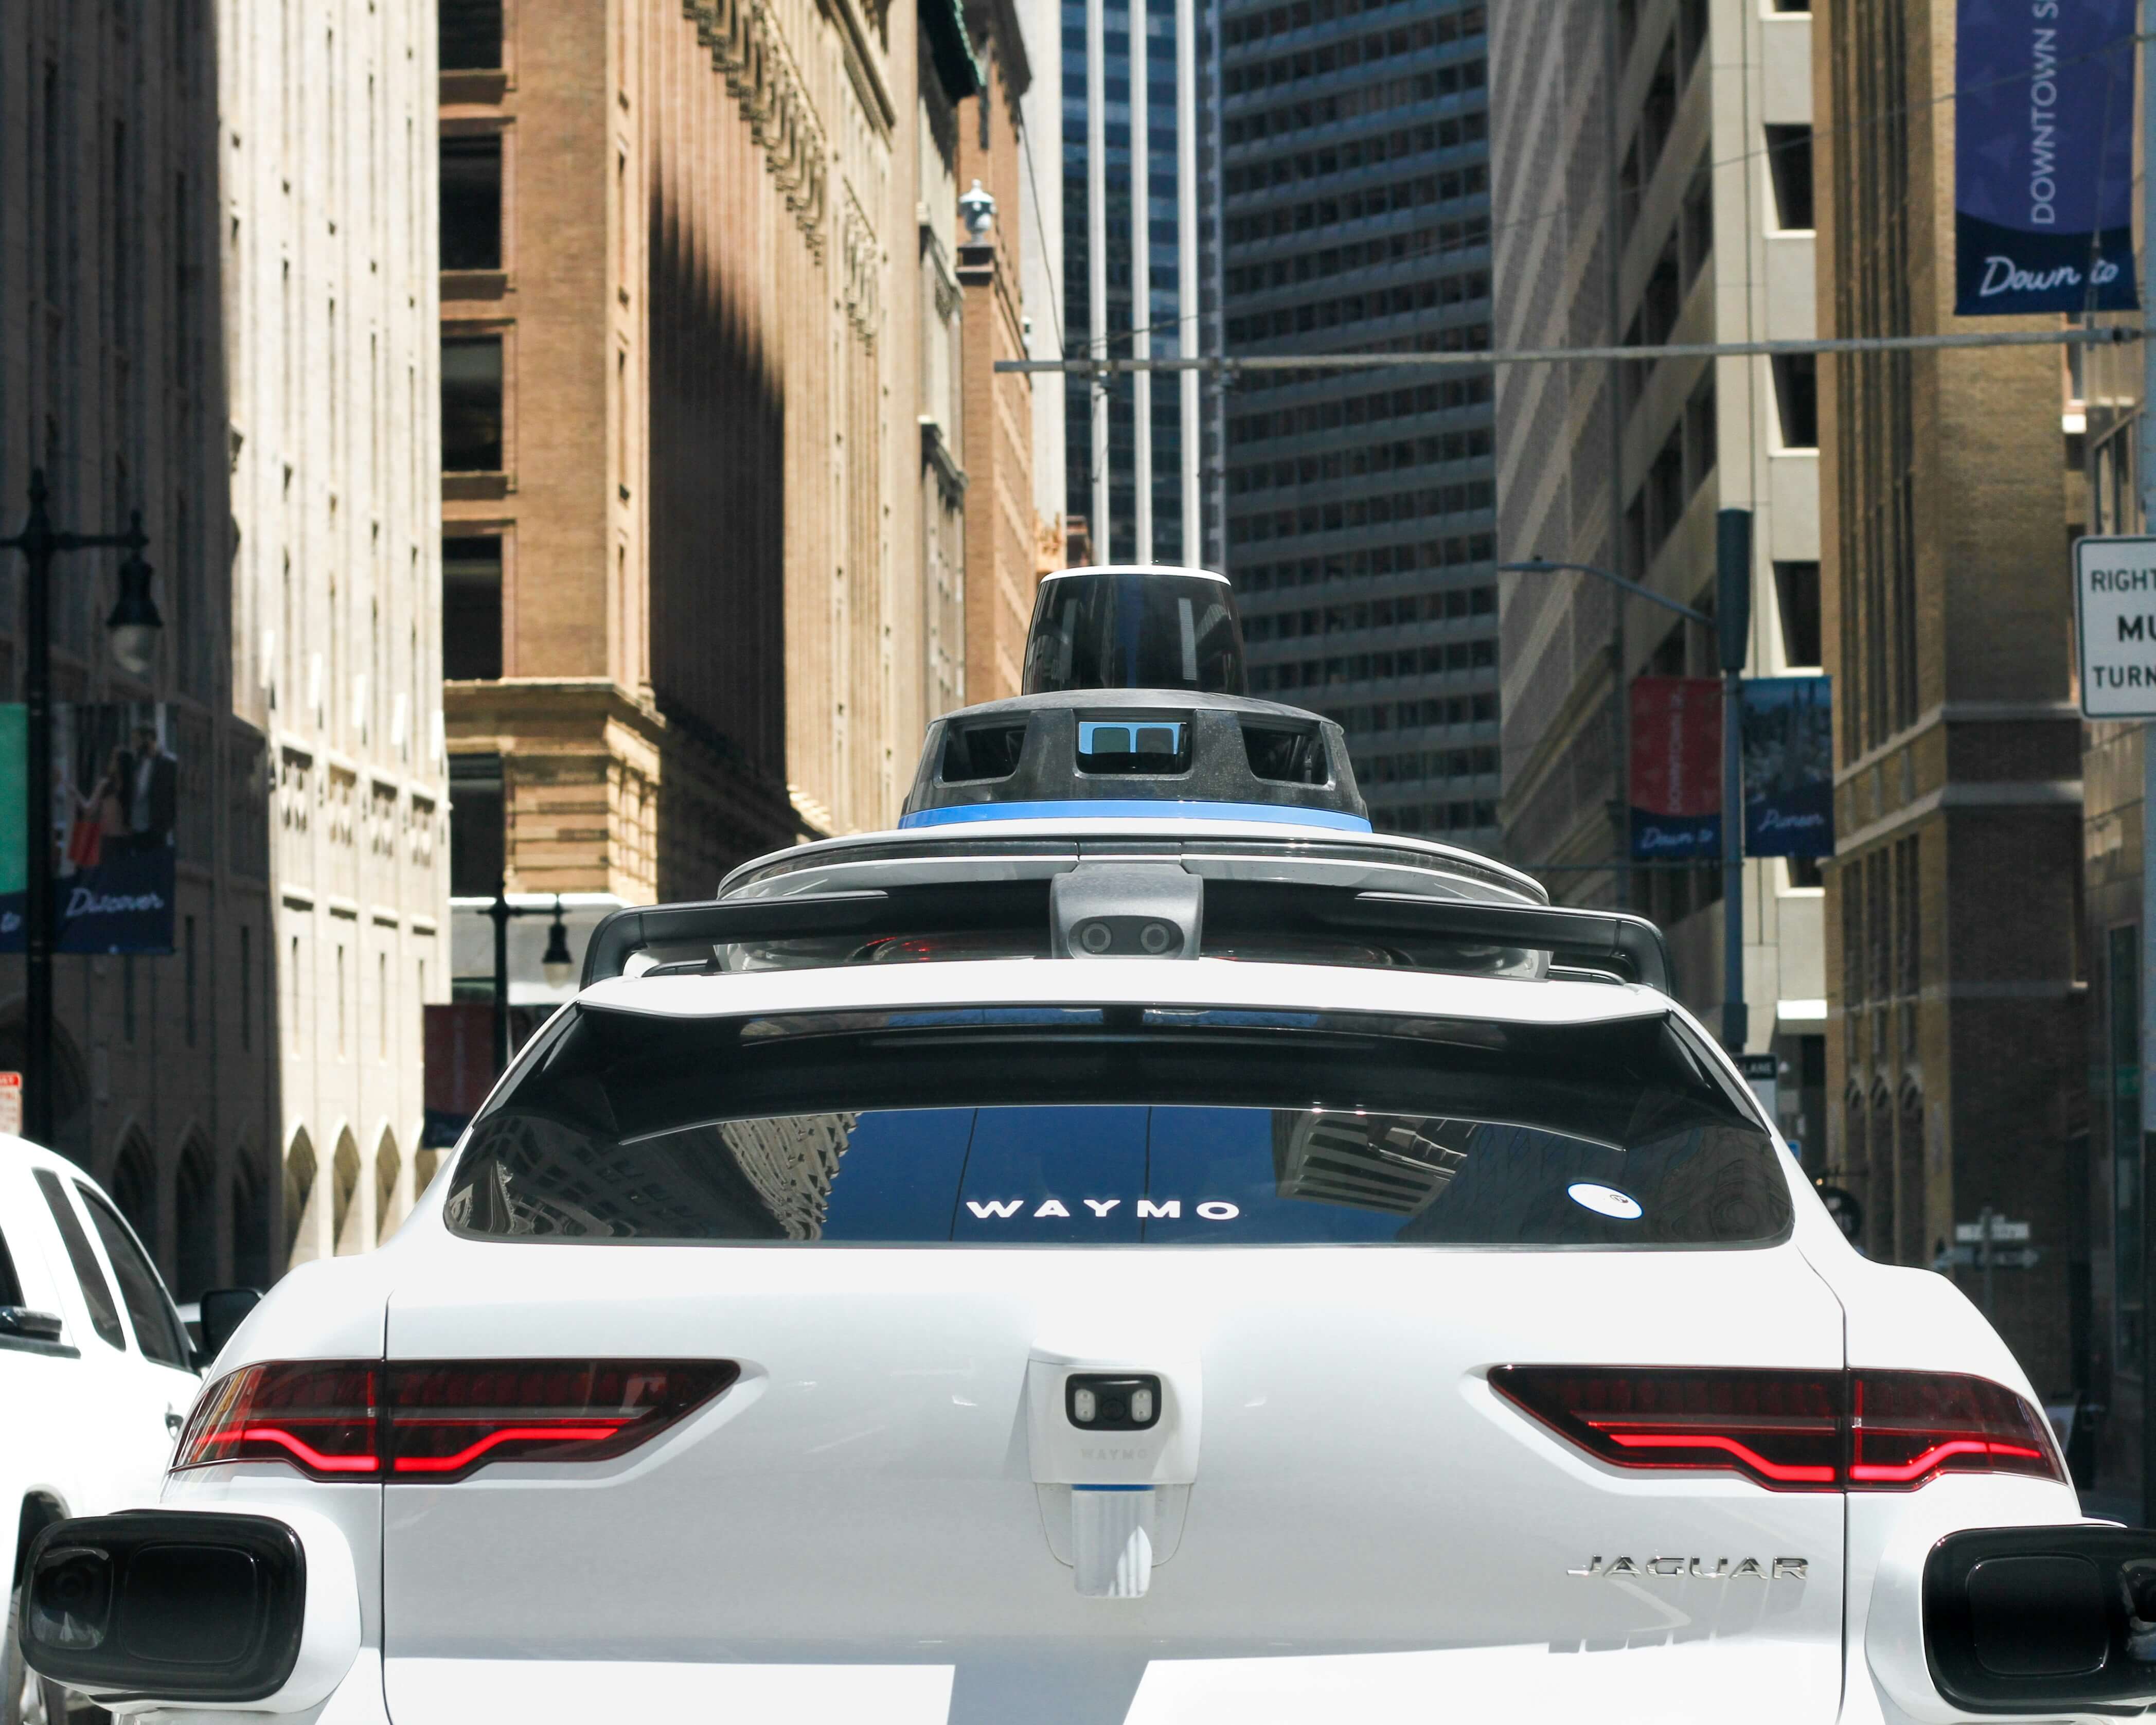
🤖 Who will actually operate Europe’s robotaxi fleets? Autonomous driving may remove the driver, but it doesn’t remove the work behind the car. Robotaxis still need charging, cleaning, maintenance, depots, customer support and someone managing the fleet every day. Early projects in Zagreb, Madrid and London illustrate different stages of deployment and how AV technology providers, fleet operators and booking platforms can work together. Taxi, rental and car-sharing companies already handle many of these tasks. What would it take to turn that experience into an autonomous fleet business?
For a taxi fleet owner, autonomous vehicles may seem to remove the most important part of the current business – the driver. But even without drivers, someone still needs to take care of the cars. They need to be owned or financed, charged, cleaned, inspected and repaired. Someone also needs to manage depots, deal with incidents, help customers and make sure enough cars are available.
The first robotaxi services and tests in Europe are already showing how this could work. The company that develops the autonomous driving technology does not always own or operate the cars. The app where customers book their rides may come from another company too. This could leave an important role for taxi, rental, car-sharing and other fleet companies that already know how to manage vehicles.
A taxi company today manages both cars and drivers. Drivers need to be recruited, scheduled, paid and supported. With a driverless fleet, these tasks would eventually disappear, but most of the work related to the cars would stay.
Autonomous cars still need charging or refuelling, cleaning, tyres, inspections, repairs and insurance. They also need somewhere to park when they are not working. If there is an accident or a technical problem, someone needs to deal with it and get the car back on the road. Customer support is still needed too when there are problems with bookings or payments, or when someone leaves something in the car.
Some of these tasks may even become more important. Robotaxis are expensive, and every hour a car spends charging, being cleaned or waiting for maintenance is an hour when it cannot take passengers. Moove, for example, already provides fleet ownership, depots, charging, maintenance and 24/7 operations for autonomous vehicles.
Drivers also do more than drive: they notice damage, report faults, help passengers and respond when something goes wrong. Without a driver, these responsibilities need clear processes and dedicated support. Existing fleet experience is an advantage, but operators will need to adapt it to vehicles running without someone behind the wheel.
There can be several companies behind one robotaxi ride. One provides autonomous driving technology, another may own the cars, and a local company can take care of the fleet. A platform such as Uber can then connect the cars with passengers. Sometimes one company may do several of these things, but this is not always the case.
Zagreb is one example. Pony.ai provides the autonomous driving system, Verne owns and operates the fleet, and Uber connects it with customers through its app. Autonomous rides became commercially available through Uber in August 2026 with a licensed operator onboard. On 10 September, Pony.ai and Verne also started fully driverless passenger test rides on a 22-kilometre route connecting parts of Zagreb with the airport. These are still limited test rides, not a fully driverless service across the whole city.
A similar model is being tested in Madrid. WeRide, Uber and AVOMO received permission in September 2026 to start testing and mapping under Spain’s ES-AV framework. The first 20 vehicles have an onboard specialist. WeRide provides the autonomous technology, Uber connects the cars with passengers, and AVOMO takes care of fleet operations. Commercial operations are planned for later in 2026, but the current permit is for testing and preparation rather than a general driverless taxi service.
In London, Wayve and Uber launched supervised autonomous passenger rides in September 2026. Customers can be matched with an autonomous vehicle through the Uber app, but there is still a licensed driver in the car.
The plans for the next few years are already much bigger. Pony.ai and Uber announced in August 2026 that they plan to deploy more than 2,000 robotaxis in Europe, starting with Zagreb and later expanding to four more European cities.
Bolt and Lucid announced another partnership in September, with Bolt aiming to deploy at least 25,000 autonomous Lucid vehicles across European cities. This is a future target, not 25,000 cars already operating today.
How these fleets are owned and operated may also be different from one city to another. Local regulations, available vehicles, charging and depot infrastructure and partnerships will all have an effect on how each service is set up.
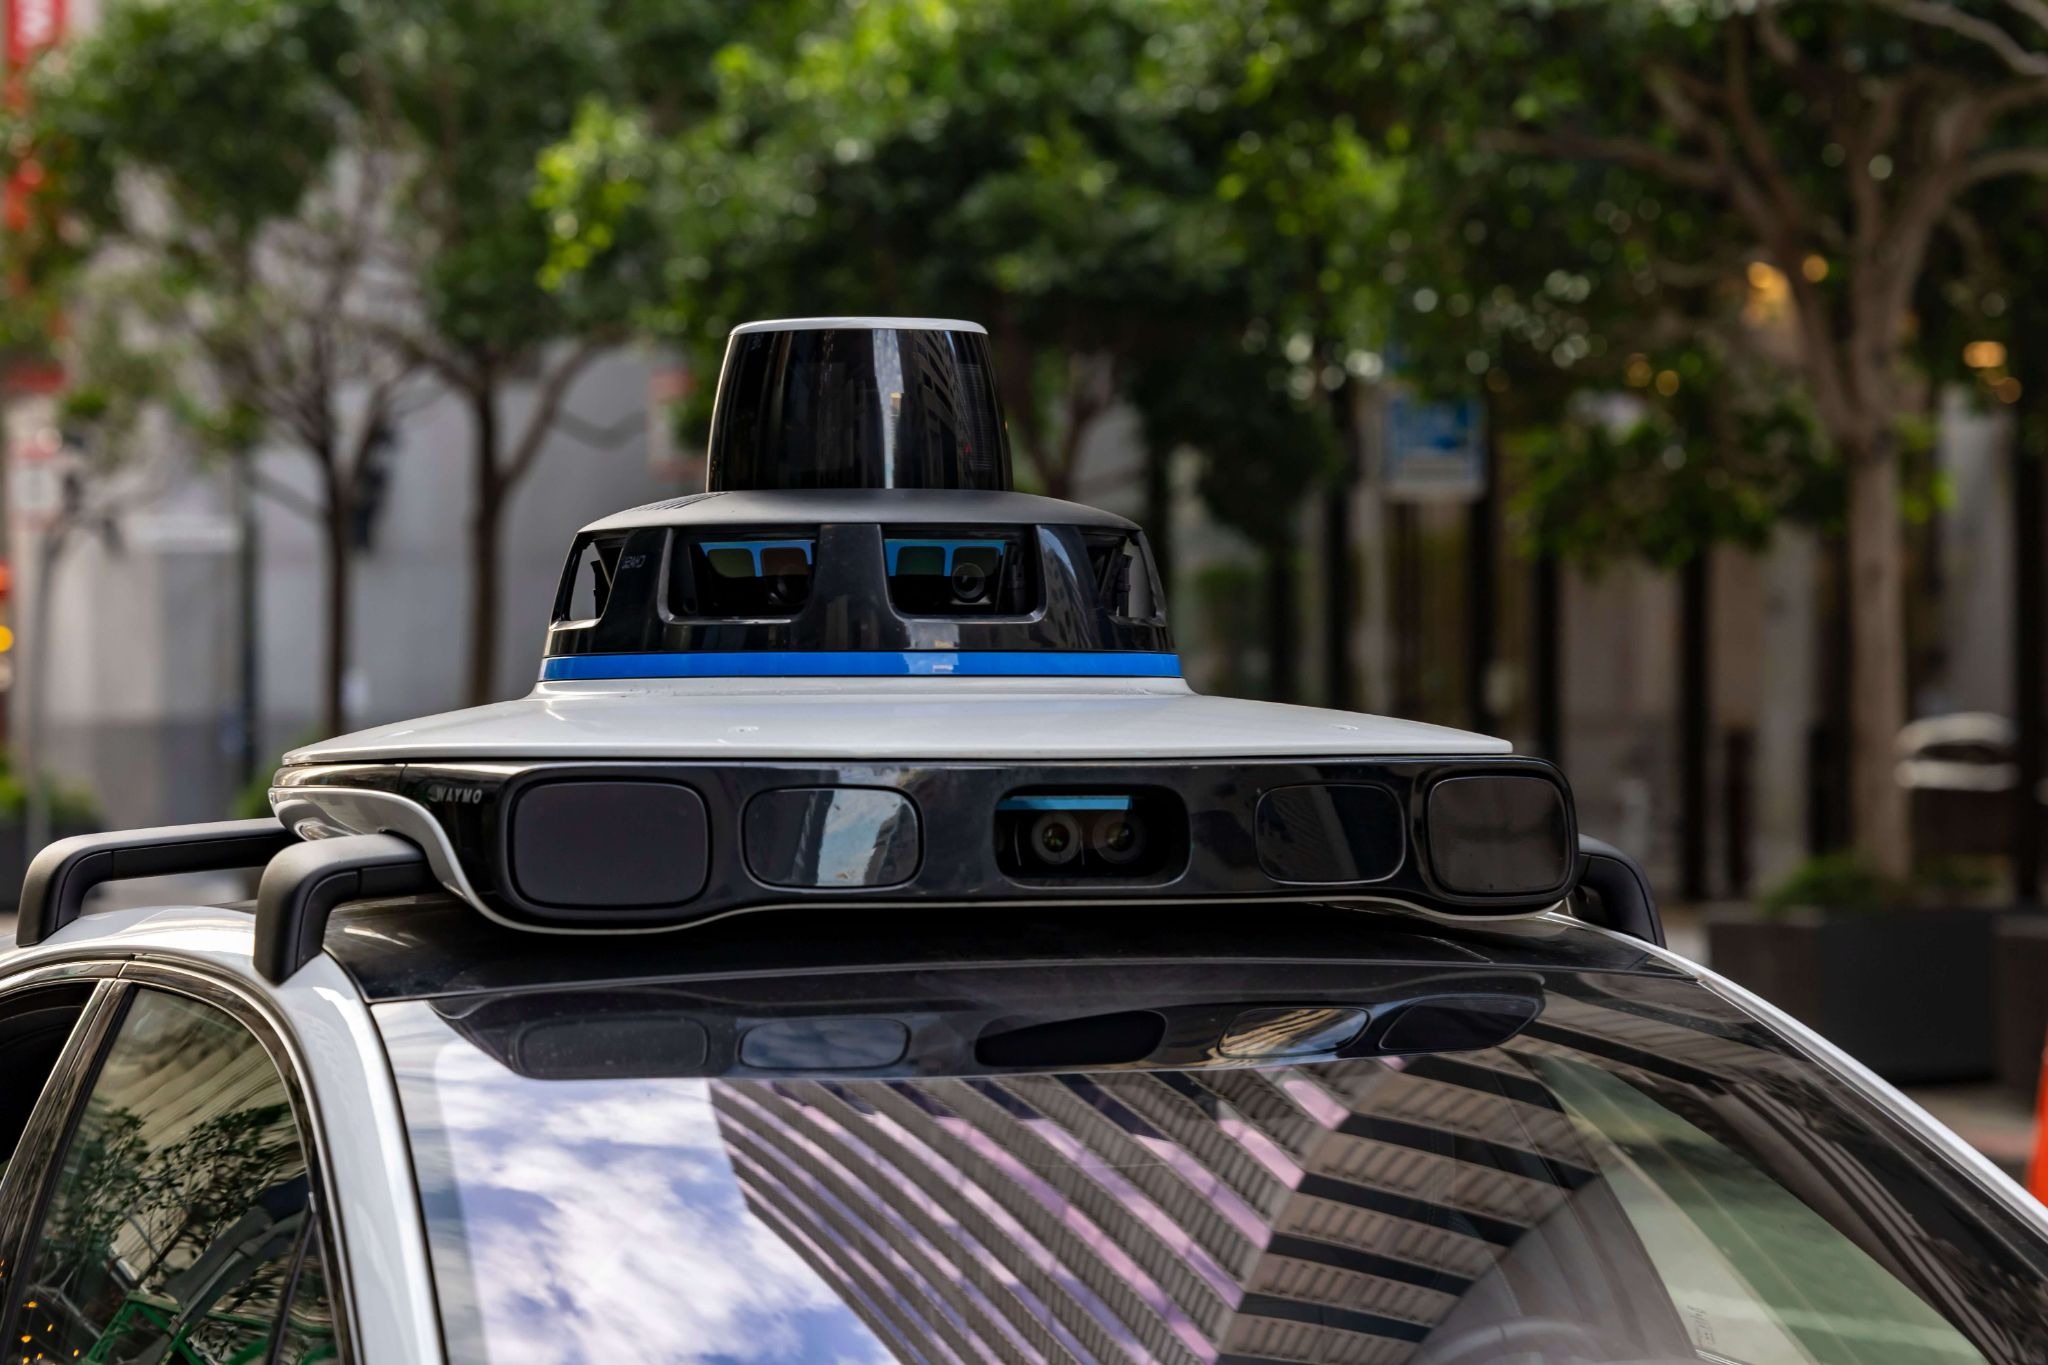
Taxi companies already do many of the things that would still be needed with an autonomous fleet. They maintain cars, deal with insurance and incidents, provide customer support and make sure enough vehicles are available. Some also already have their own depots, charging infrastructure or maintenance partners.
One possible model can already be seen in Zagreb. A local company owns and operates the autonomous fleet, while a larger ride-hailing platform brings customers. In the future, an existing taxi company could potentially have a similar role. Instead of managing cars and drivers, it could manage autonomous cars that receive bookings through a larger platform.
This does not mean platforms such as Uber will always rely on other companies to own the cars. Uber’s 2026 agreement with Rivian includes up to $1.25 billion in milestone-dependent investment and says that Uber or its fleet partners may purchase the autonomous vehicles. Uber is also developing infrastructure for autonomous fleets. Different ownership models are therefore possible.
Autonomous vehicles could also become interesting for rental and car-sharing companies, although this is probably further in the future. These businesses already manage vehicles, maintenance, cleaning, charging, bookings, customer accounts and payments, so much of the practical work is similar.
Autonomous driving could also change how rental and sharing cars are moved. Today, an employee may need to drive a car from one location to another. In the future, the vehicle could potentially do this itself within an area where autonomous driving is approved. It could even become possible for a rental car to drive itself to a customer’s pickup point.
Without drivers, it becomes especially important to understand how much time each vehicle is actually working. Every hour spent charging, being cleaned, waiting for maintenance or simply sitting unused means less time carrying paying passengers.
Some useful KPIs could be available hours per vehicle, paid trips per vehicle each day, revenue per available vehicle/day, empty kilometres, charging and maintenance downtime, cost per trip and incidents that need human help. These are most popular robotaxi industry KPIs of what a company could measure during a pilot.
For example, if cars spend too much time waiting to charge, the charging setup may need to change. A lot of empty kilometres could mean the cars are not in the right places, while too much maintenance downtime could make a vehicle more expensive to operate.
For either model, the business case depends on the partnership terms: who finances the vehicles, who carries the risk when demand is low, and how revenue and operating costs are shared. Operators should assess what remains after vehicle financing, insurance, charging, maintenance and partner fees. Depots, local service teams and reliable fleet availability could make an operator a valuable partner, but profitability still needs to be demonstrated.
One option for taxi fleets would be to work with an autonomous driving company and a larger ride-hailing platform. The local company could own or manage the cars and take care of the fleet, while customers book their rides through the larger platform.
Another option could be possible in cities where large ride-hailing platforms are not present or have limited coverage. A local company could work with an approved AV provider while using its own app, bookings, payments, customer support and fleet management.
In both cases, a company cannot simply buy autonomous cars and start offering rides. The technology needs to be approved, and local rules have to allow the service. These rules will also be different across Europe. Great Britain, for example, introduced its Automated Passenger Services permitting framework in 2026. Services similar to taxis or private hire vehicles need consent from the relevant local authority, while responsibility for the autonomous driving technology and the passenger service are treated separately.
A company does not need to have autonomous cars today to start preparing. A good first step is understanding the current fleet in detail – what each vehicle costs, how many hours it is available, how much time it spends charging or being repaired, and when cars are used the most.
Charging, cleaning, maintenance and depot processes are also worth looking at because all of these will still be needed with autonomous vehicles. A company interested in an AV pilot can then choose a location and use case, look at the local permit process and start talking to autonomous driving technology providers.
The software will also need some preparation. Customers still need to book and pay for rides, while the company needs fleet information, customer support, reporting and connections between its own systems and the AV technology. Starting with a small pilot makes it possible to test all of this before trying to build a larger service.
ATOM Mobility already provides many of the software functions used by taxi, ride-hailing, rental and sharing companies, including customer apps, bookings, payments, fleet management, maintenance tasks, analytics and APIs. Its ride-hailing software includes passenger and driver apps, dispatch, payments, fleet data, analytics and integrations. The ATOM Mobility API can also exchange data about vehicles, bookings, rides, payments, telemetry and maintenance tasks.
ATOM Mobility does not provide autonomous driving technology. This would come from a specialised AV company, and each project would have its own technical requirements and local approvals. For an AV pilot, ATOM Mobility could work with the fleet company and AV provider on the rider experience, integrations, fleet management and the data needed to measure how the pilot is working.
If you operate a taxi, rental or sharing fleet and want to explore an AV pilot, ATOM Mobility can help plan the booking and fleet-management setup, integrations and metrics you would need to test together with an AV technology partner.

Most taxi companies don’t fail because of tech - they fail because no one knows they exist 👀 In today’s market, competing with Uber isn’t about features, it’s about demand. 📈 No brand, random marketing, “Later” mindset results in low utilization & slow growth. In this article, we break down the most common mistakes - and how to build a marketing system that actually drives rides 🚀
Most taxi and ride-hailing companies don’t fail because of bad technology. They fail because no one knows they exist. In a market shaped by players like Uber, demand is no longer something that “just happens.” It’s engineered. Built. Optimized. Repeated.
Yet many operators still treat marketing as something secondary - something to figure out after the launch, after the fleet is ready, after drivers are onboarded. By then, it’s already too late.
A common pattern we see is this: a company launches with a functional product, maybe even a solid operational setup, but without a clear brand or acquisition strategy. A few campaigns are tested, some budget is spent across different channels, but nothing is consistent. There is no clear positioning, no defined audience, and no system to measure what actually works.
The result is predictable. Growth is slow, utilization stays low, and pressure starts to build. At that point, marketing becomes reactive - driven by urgency rather than strategy. Discounts increase, experiments multiply, and costs rise faster than revenue.
This is where many businesses lose control of their unit economics.
Poor marketing rarely comes from a lack of effort. It usually comes from wrong priorities. Many operators believe they have more urgent problems to solve - fleet, drivers, operations - and that marketing can wait. It feels logical in the short term, but in reality it’s a short-sighted decision that creates much bigger problems later.
Another common issue is lack of direction. Marketing activities exist, but they are scattered and unstructured. There is no clear target audience, no defined positioning, and no consistent brand language. Without that foundation, even well-funded campaigns struggle to deliver results.
This is where the gap between smaller operators and companies like Uber becomes obvious. The difference is not just budget - it’s clarity. They know exactly who they target, how they communicate, and how they measure success.
Without that clarity, marketing becomes noise. And noise doesn’t convert.
In early stages, many companies treat marketing as a “nice to have.” Budgets are allocated to everything else first, and whatever remains is used for promotion - if anything is left at all. The assumption is simple: launch first, invest in marketing later.
The same thinking often leads to another mistake - launching with a weak or non-existent brand. A generic app, no clear identity, no differentiation. It may save money initially, but it creates a much bigger problem: people don’t remember you, and you can’t build demand around something that has no identity.
At some point, reality catches up. Growth is slower than expected, revenues don’t match projections, and pressure builds. That’s when companies switch into reactive mode. Marketing becomes urgent instead of strategic. Discounts increase. Random campaigns are launched. Budgets are spent faster, but results don’t improve. Panic replaces planning - and panic-driven marketing almost never works.
Forget random marketing. It doesn’t scale. If you want predictable growth, start here:
The earlier you build this system, the faster you reach profitability.
At ATOM Mobility, we’ve seen this dynamic across hundreds of mobility businesses globally. The difference between those who scale and those who stall rarely comes down to technology alone. Execution is what separates them.
That’s also why we expanded beyond software and, together with industry experts, launched a dedicated marketing service to support operators directly.
We help mobility businesses go from zero to scalable demand - covering go-to-market strategy, branding, performance marketing, app store optimization, and continuous growth management, all tailored specifically for ride-hailing and taxi operators.
👉 Learn more and see how we can support your growth:
https://www.atommobility.com/marketing-agency
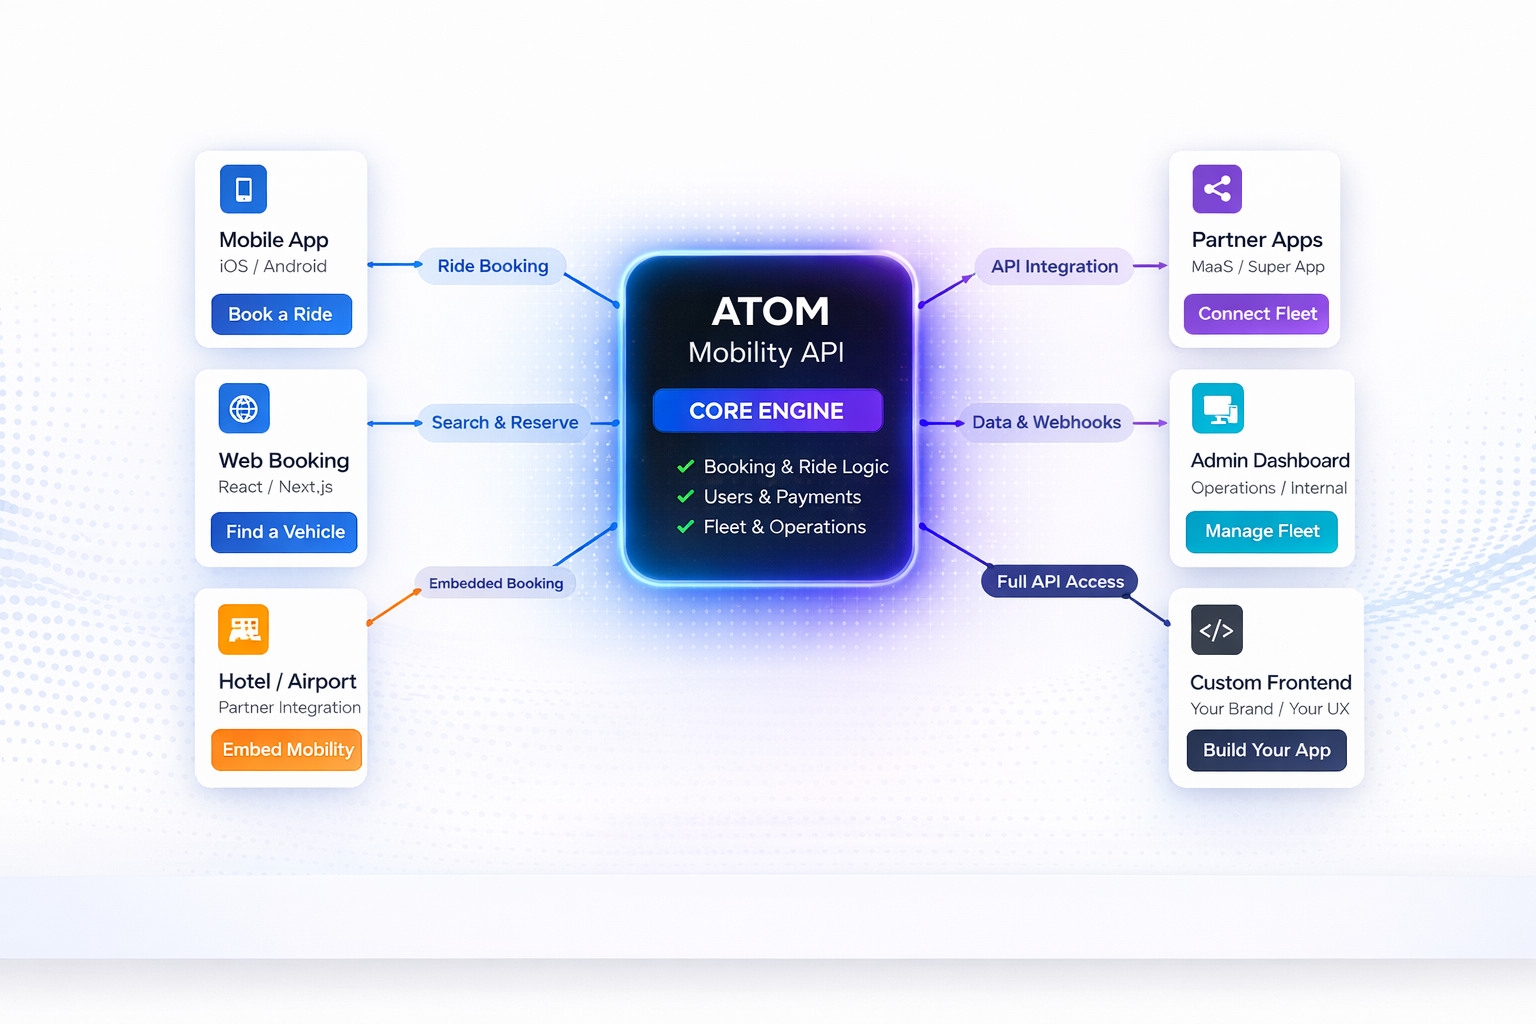
⚡ Launch faster and integrate anywhere with ATOM Mobility API. Build your own mobility experience without rebuilding the backend. Learn how ATOM Mobility API lets you integrate, customize, and scale faster.
Shared mobility is moving beyond standalone apps. Operators today are expected to integrate into existing ecosystems - from hotel and airport platforms to corporate travel tools and MaaS apps. Building all of that from scratch is slow, expensive, and hard to scale.
That’s why ATOM Mobility offers a fully developed OpenAPI - allowing you to build your own mobility experience on top of a proven backend.
Most mobility solutions are still built as closed systems. That creates friction: integrations take time, custom features require heavy development, and expanding into new channels becomes complicated.
An API-first approach changes this.
Instead of rebuilding core functionality, operators can use ATOM Mobility as the underlying system and build their own layer on top. Booking flows, payments, vehicle control, and operational logic are already there - accessible via API.
With API access, mobility can be embedded directly where users already are.
- A ride can be booked from a hotel website. A car can be unlocked through a partner app. A custom frontend can be built for a specific market without touching the backend.
- At the same time, operators can connect their own tools: from internal dashboards to finance and reporting systems (for example, Power BI) creating a more automated and scalable operation.
The result is not just a mobility app, but a flexible system that can adapt to different markets, partners, and use cases.
🚗 Booking & ride management - search vehicles, reserve and unlock, start and end trips, manage ride status.
💳 Payments & users - create and manage users, handle payments and pricing, access booking history.
🛴 Fleet & operations - vehicle status and location, zones and restrictions, pricing configuration.
🔌 Integrations - connect third-party apps, sync with external systems, automate workflows and more...
1. Embedded mobility in partner platforms
Booking directly from (no app download needed):
2. Custom frontends and apps
Operators build:
All powered by ATOM Mobility backend.
3. IoT and hardware integrations
4. Automation & internal tools
Instead of spending months building core systems, operators can use ATOM API and focus on what actually drives growth - distribution and partnerships.
Learn more:
https://www.atommobility.com/api
Explore the API:
https://app.rideatom.com/api/docs
🚗 Scaling a rental fleet without automating maintenance? That’s risky. Spreadsheets and routine checks might work at 20 vehicles, but once you grow past 50, things start slipping. More operators are using IoT telematics, automatic error codes, and mileage-based service alerts to catch issues early and keep vehicles available. See how rental fleet maintenance automation helps you scale without chaos.
How to automate maintenance alerts for rental fleets
Rental fleet maintenance automation is becoming essential for operators who want to scale without increasing operational complexity. Whether you manage cars, scooters, bikes, or mixed fleets, manual inspections and spreadsheets quickly fail once your fleet grows beyond a few dozen vehicles.
Breakdowns, missed services, and delayed repairs directly affect uptime, revenue, and customer satisfaction. Modern fleet technology makes it possible to automate maintenance using IoT telematics, onboard sensors, automatic error codes, mileage-based triggers, and structured dashboards.
Why manual maintenance tracking does not scale
In small fleets, maintenance is reactive. A customer reports an issue. A staff member checks the vehicle. Someone creates a task manually. This works for 20 vehicles, but for 200 it’s just too much work.
As fleets expand, issues are discovered too late, standards vary between locations, and staff spend more time coordinating than fixing. Rental fleet maintenance automation shifts operations from reactive repairs to preventive, system-driven workflows.
Using IoT telematics to monitor vehicles in real time
IoT telematics devices collect live data such as location, battery level, ignition status, engine health, and mileage. In car rental and car sharing fleets, telematics also track fuel levels, driving behaviour, and diagnostic information.
Instead of waiting for user reports, the system can trigger alerts automatically. For example:
This data feeds directly into the fleet platform, where workflows assign tasks automatically, reducing response times and eliminating internal coordination delays.
Onboard sensors and automatic error codes
Modern vehicles generate diagnostic trouble codes when systems fail. In connected fleets, these codes appear instantly in the operator dashboard.
If a vehicle reports a brake or engine warning, the system can block it from new bookings, notify technicians, and create a repair task automatically. In micromobility fleets, IoT modules detect tilt events, battery degradation, failed unlock attempts, or controller errors.
Digital reporting further improves vehicle availability. ATOM Mobility’s vehicle damage management feature shows how structured workflows reduce downtime and improve transparency.
Mileage-based and time-based service automation
Rule-based servicing is one of the most effective elements of rental fleet maintenance automation.
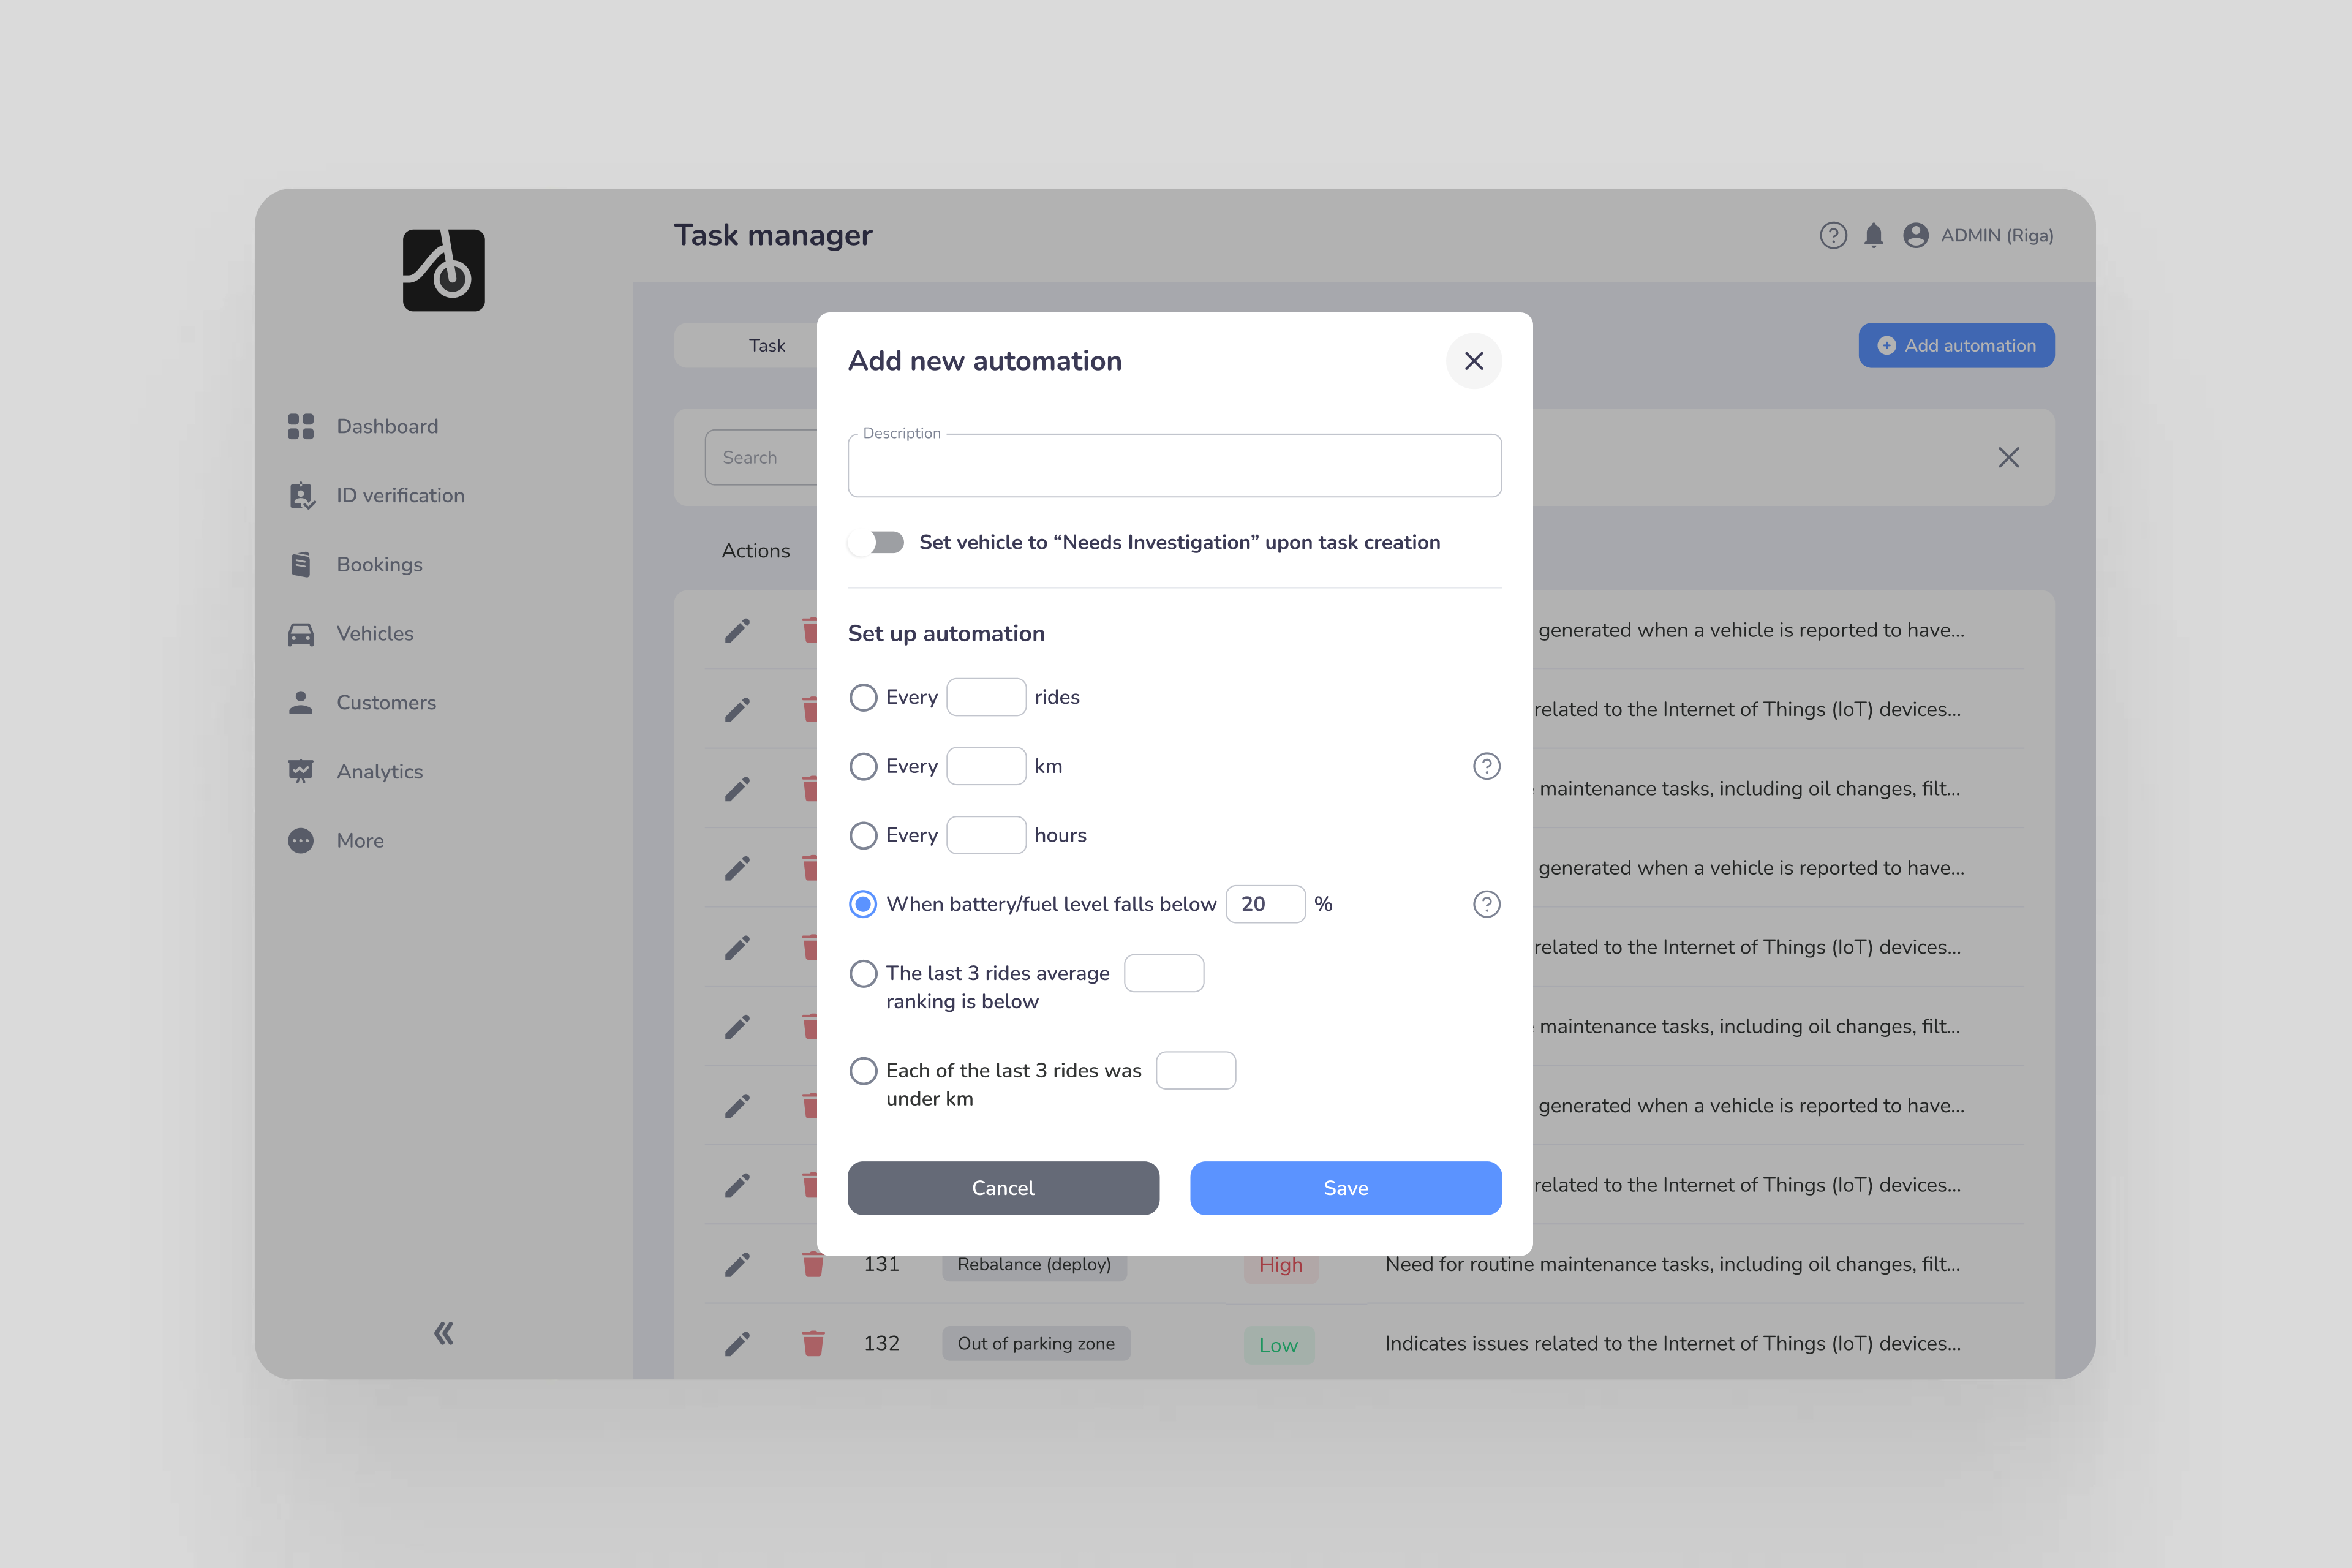
Operators can set simple service rules, such as:
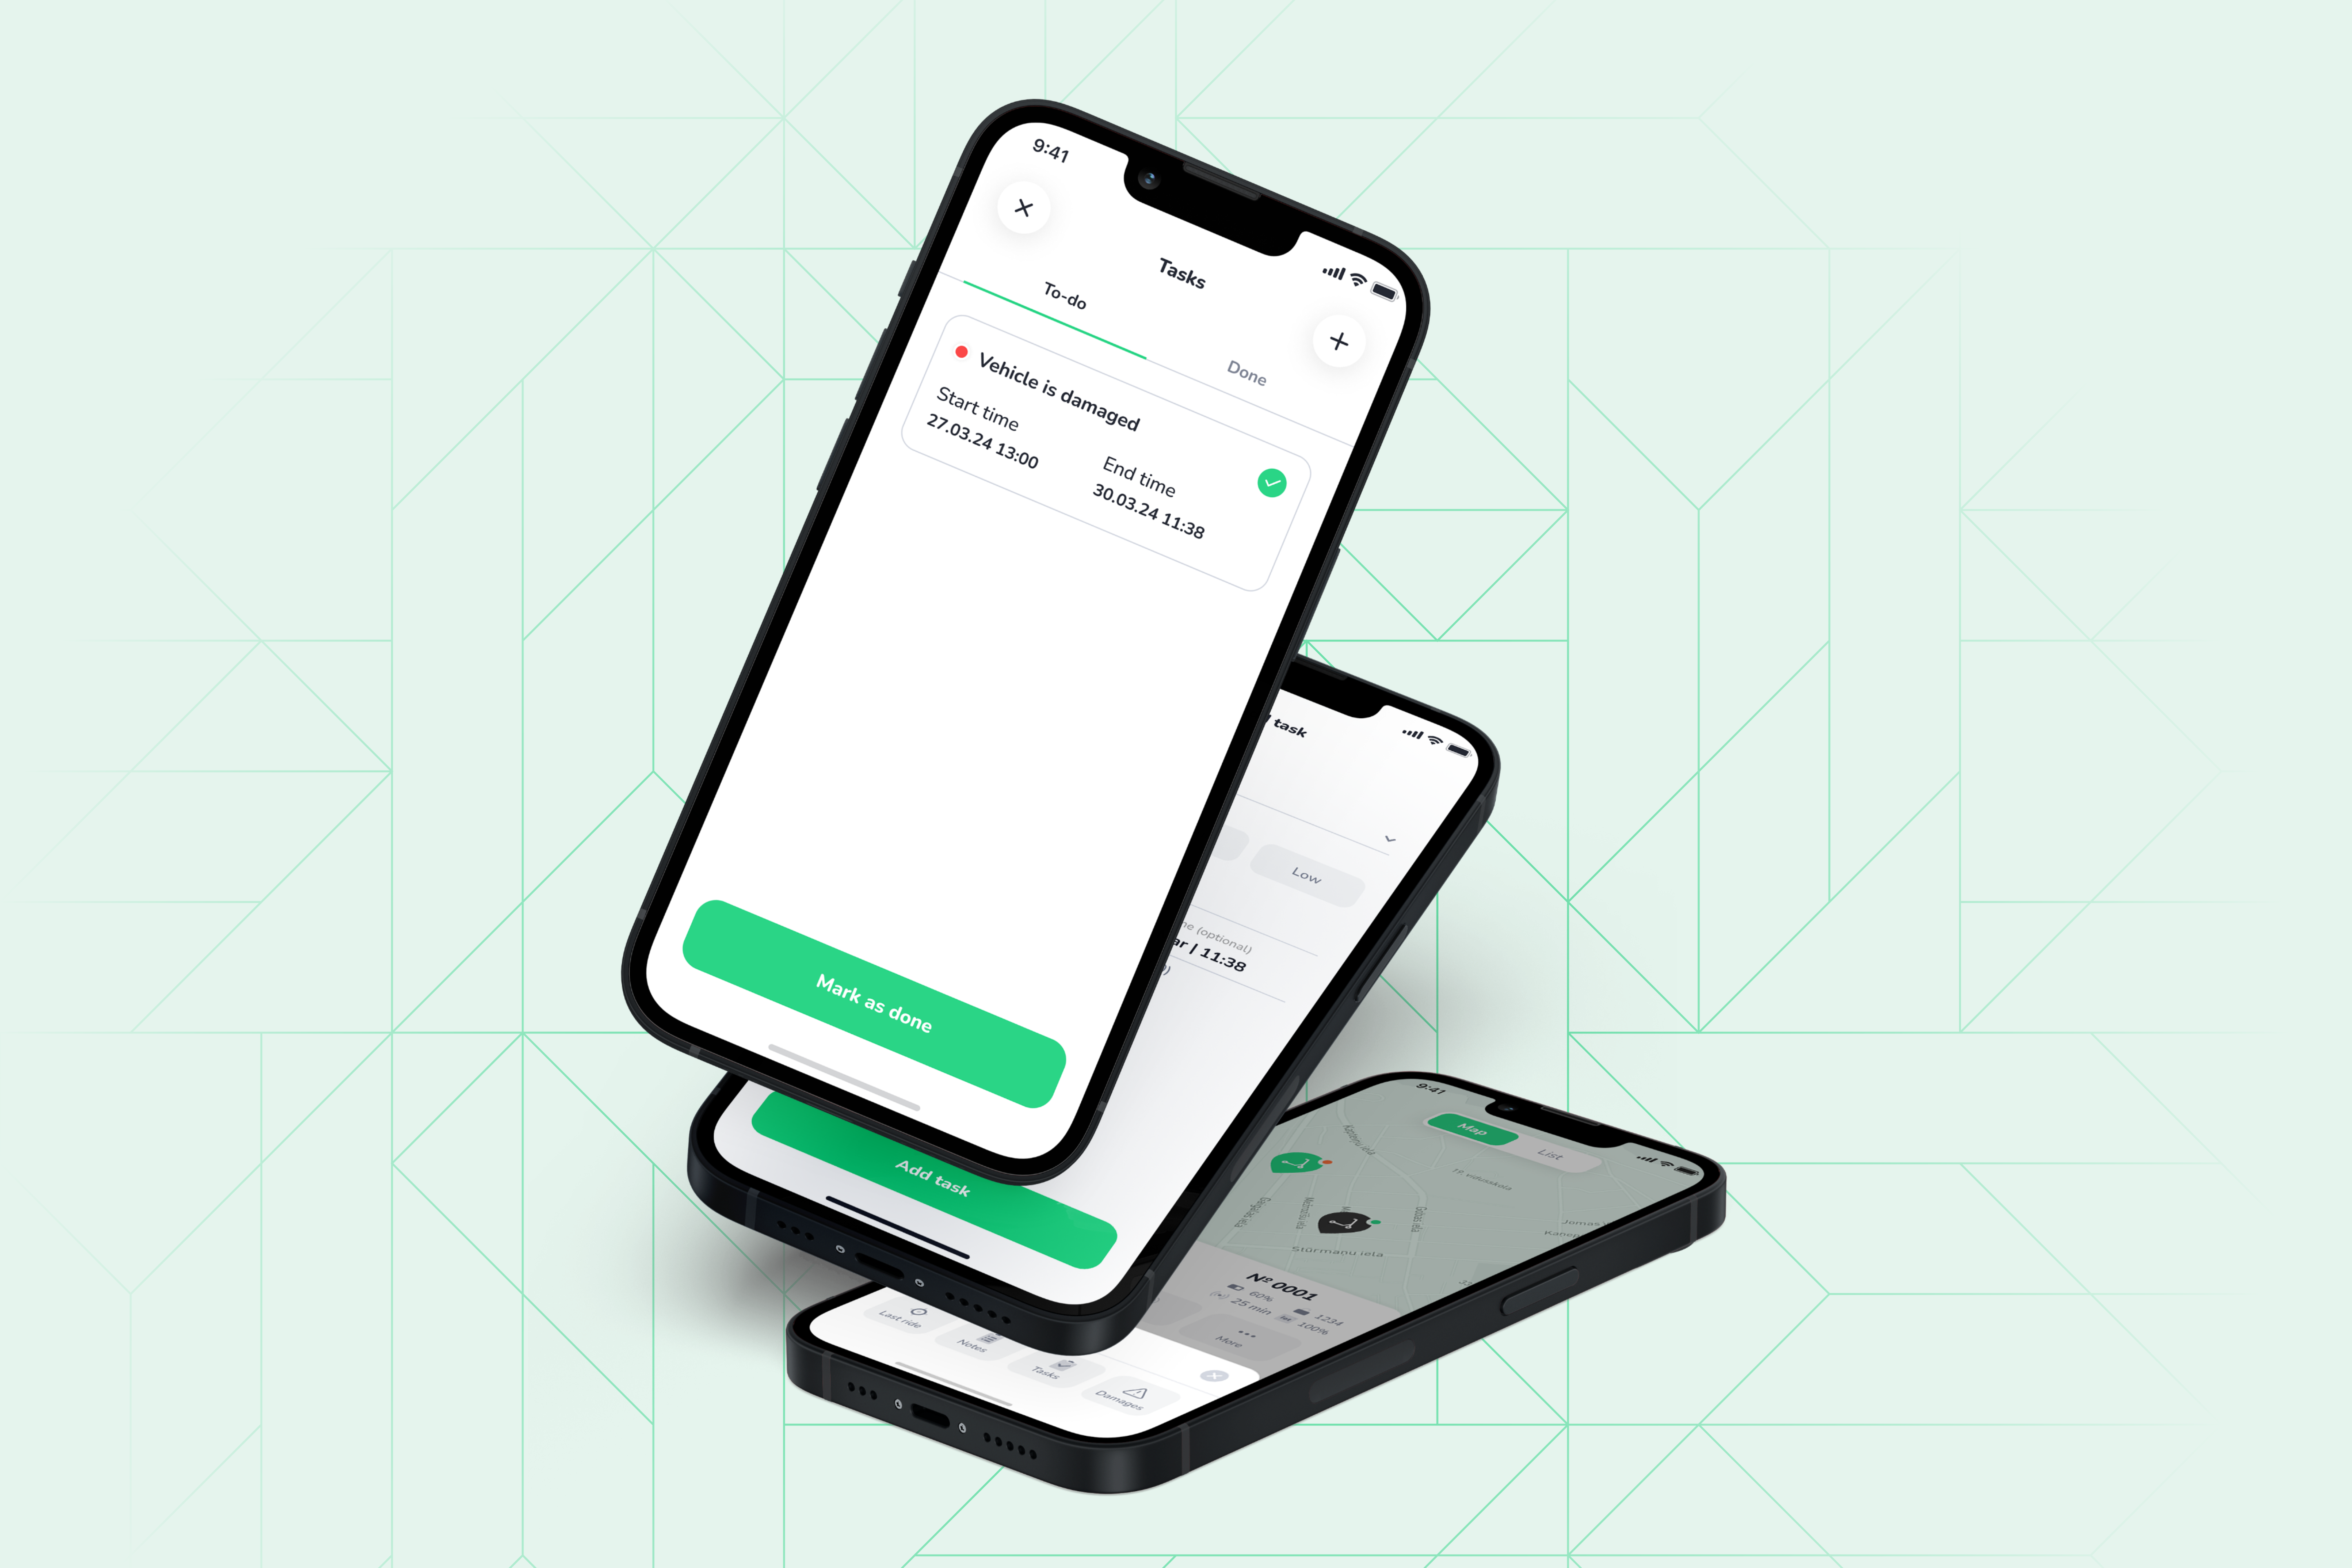
When a vehicle reaches one of these limits, the system creates a task automatically. The vehicle can also be temporarily removed from booking until the service is done. This becomes especially important when operating in multiple cities, because it keeps safety standards consistent across the entire fleet.
Maintenance dashboards and task automation
A maintenance dashboard centralises alerts, open issues, and upcoming service requirements.
With structured task management, teams can assign jobs, set priorities, track resolution times, and analyse recurring issues. ATOM Mobility’s Task Manager feature enables operators to convert alerts directly into trackable actions within one system. Alerts that turn into tasks automatically make it clear what needs fixing and when it should be handled.
From reactive to predictive maintenance
With enough historical data, fleets can move beyond fixed intervals. Operators can identify patterns such as faster brake wear in specific models or higher damage rates in certain areas. Predictive maintenance allows servicing based on actual usage intensity, reducing unnecessary costs while preventing major failures.
For operators growing from 50 to 500 vehicles, automation delivers clear advantages:
Automation supports maintenance teams with clearer priorities and better data.
Building the right automation stack
Effective rental fleet maintenance automation typically requires:
When these components are connected, maintenance becomes scalable and controlled instead of reactive. This is especially important for operators running scooter, bike, car sharing, or rental businesses, where uptime directly impacts revenue and retention.
Rental fleet maintenance automation makes maintenance more organised and easier to manage as you grow. IoT telematics, automatic diagnostics, mileage alerts, and task dashboards help create clear processes that support expansion.
For rental and shared mobility operators who want to grow steadily, automating maintenance is essential. It helps keep operations stable and supports long-term profitability.
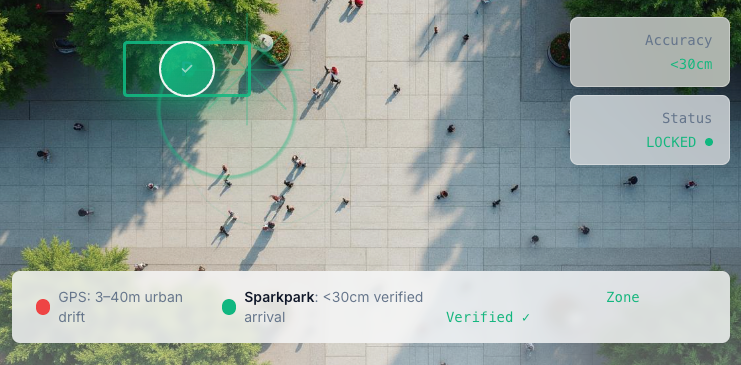
Lime improved GPS from 12m to ~1.5m accuracy - a big step forward for micromobility. 🚀 But parking compliance isn’t just about knowing where a vehicle is - it’s about proving it’s parked correctly. Real-world pilots (like Prague) show that physical verification (e.g. Bluetooth beacons) can significantly outperform GPS when it comes to actual compliance.
Lime just raised the bar for GPS-based parking compliance. But the bigger question is this: when cities want verified parking, is better GPS enough, or do operators need physical proof? That question matters more than ever.
Lime’s new LimeBike rollout in the UK comes with a major location upgrade. Lime says its new bikes can locate themselves to within 1.5 metres, a significant improvement from the roughly 12.3 metres typical in dense urban environments (this means that based on GPS data, a vehicle can be up to 12 meters farther or closer than the reported GPS location. Now this error is just 1.5 meters). That is real progress.
Lime’s upgrade is a meaningful step forward for GPS-based positioning. At the same time, cities are increasingly looking beyond positioning accuracy toward verifiable parking compliance.
Cities are becoming much less tolerant of parking disorder. In Kensington & Chelsea, the council seized 1,000 rental e-bikes by November 2025 and collected more than £81,000 in charges from operators.
That is the real backdrop for every operator today:
So yes, better GPS is good news. But it does not automatically mean cities will see parking as “solved.” A vehicle may be near a bay, beside a bay, or slightly outside it. In dense urban areas, that difference matters. Traditional GPS struggles there because of building interference, blocked satellite visibility, and signal reflections.
So the strategic question is no longer:
“Can we improve GPS?”
It is:
“What kind of system gives cities enough confidence to enforce parking rules fairly and consistently?”
A European Commission-backed pilot in Prague tested a different approach: Bluetooth-based parking verification.
Across 25 parking locations and 989 parking events, the results were clear:
When the goal is verified parking inside a defined zone, infrastructure-based validation can significantly outperform vehicle-only (GPS) positioning.
Lime’s move shows how far vehicle-side intelligence is improving. SparkPark points to a different model: verify the parking zone itself.
That distinction matters.
Those are fundamentally different approach.
One of the key findings from the Prague pilot is not just technical - it is institutional. Cities often rely on operator-provided data to assess compliance. That creates a trust gap. What cities increasingly want:
This is why the conversation is shifting from “better accuracy” → “verifiable proof.”
Parking compliance is becoming more important than ever:
Operators who can demonstrate verifiable compliance may have a clear advantage.
With ATOM Mobility, partners can explore:
Instead of waiting for hardware cycles, operators can move faster and adapt to changing city expectations.
Lime deserves credit for pushing GPS accuracy forward. It is a meaningful step for the industry. But the Prague pilot highlights something equally important:
Micromobility parking may not be solved by better positioning alone. It may also require verification.
Not:
“Where is the vehicle likely parked?”
But:
“Can this parking event be verified with confidence?”
The future of parking compliance is likely evolving across two complementary paths:
Path 1: improve GPS accuracy
Path 2: implement physical verification
The first makes parking smarter. The second makes it more reliable and verifiable.
And in regulated urban mobility, confidence and trust often matter as much as precision.
Want to explore how ATOM Mobility can support stricter parking compliance workflows and how SparkPark technology works alongside the ATOM Mobility platform? Get in touch with our team to discuss integration options and city-facing parking control setups.
Sources:
Lime GPS upgrade announcement:
https://www.smartcitiesworld.net/micromobility/new-lime-bike-upgrade-to-hit-uk-streets-this-month-12568
West Midlands LimeBike rollout:
https://www.wmca.org.uk/news/new-limebike-to-launch-in-west-midlands/
Kensington & Chelsea enforcement data:
https://www.rbkc.gov.uk/newsroom/1000-e-bikes-seized-borough
Prague SparkPark pilot (EIT Urban Mobility):
https://marketplace.eiturbanmobility.eu/best-practices/high-precision-parking-for-shared-micromobility-in-prague
SparkPark:
https://sparkpark.no
"State of art technology in mobile apps and dashboard, very good SLA!"
"Easy, nice looking, continuously updated and developed every month and most of all very reliable with a extreme high uptime"
"We used to work with a different service provider which wasn't fitting our needs. Switching to ATOM was an improvement on our side"
Use test credentials to log in - Phone number: +1 123123123, Code: 777777
Driver App demo credentials - Email: test@atom.com, Password: driver