Blog
Insights and news from the ATOM Mobility team
We started our blog to share free valuable information about the mobility industry: inspirational stories, financial analysis, marketing ideas, practical tips, new feature announcements and more.
We started our blog to share free valuable information about the mobility industry: inspirational stories, financial analysis, marketing ideas, practical tips, new feature announcements and more.
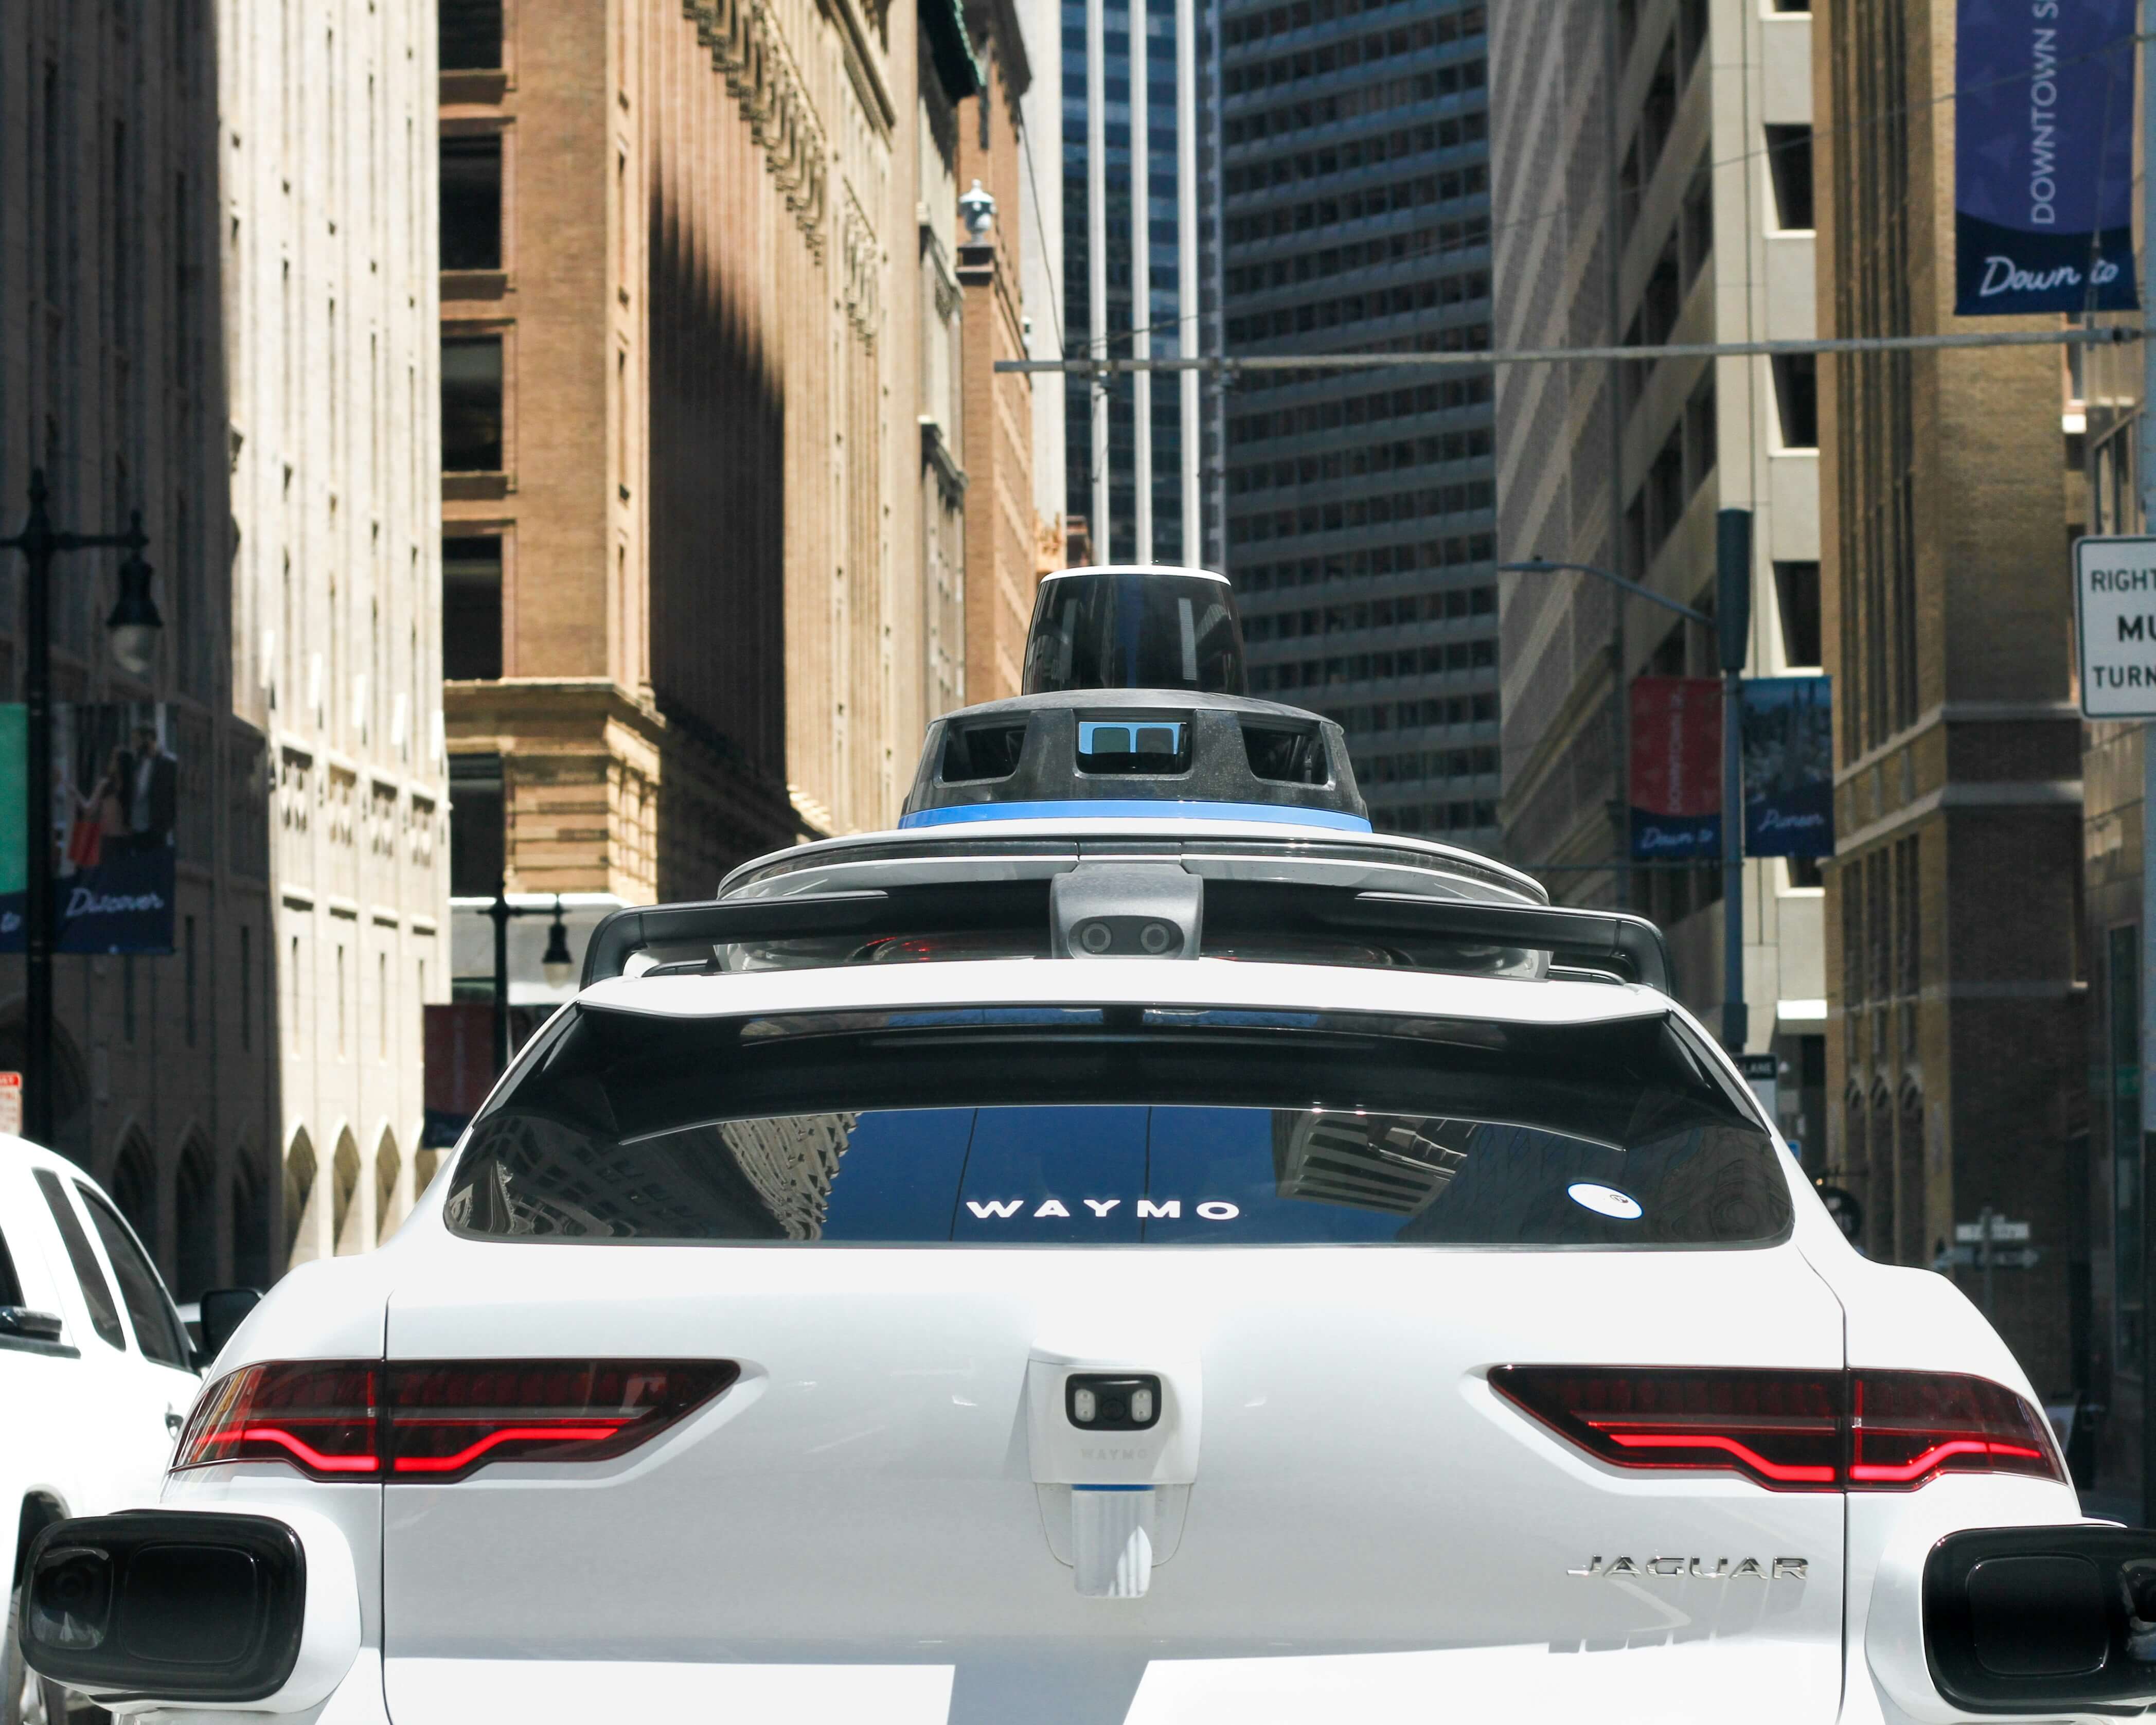
🤖 Who will actually operate Europe’s robotaxi fleets? Autonomous driving may remove the driver, but it doesn’t remove the work behind the car. Robotaxis still need charging, cleaning, maintenance, depots, customer support and someone managing the fleet every day. Early projects in Zagreb, Madrid and London illustrate different stages of deployment and how AV technology providers, fleet operators and booking platforms can work together. Taxi, rental and car-sharing companies already handle many of these tasks. What would it take to turn that experience into an autonomous fleet business?
For a taxi fleet owner, autonomous vehicles may seem to remove the most important part of the current business – the driver. But even without drivers, someone still needs to take care of the cars. They need to be owned or financed, charged, cleaned, inspected and repaired. Someone also needs to manage depots, deal with incidents, help customers and make sure enough cars are available.
The first robotaxi services and tests in Europe are already showing how this could work. The company that develops the autonomous driving technology does not always own or operate the cars. The app where customers book their rides may come from another company too. This could leave an important role for taxi, rental, car-sharing and other fleet companies that already know how to manage vehicles.
A taxi company today manages both cars and drivers. Drivers need to be recruited, scheduled, paid and supported. With a driverless fleet, these tasks would eventually disappear, but most of the work related to the cars would stay.
Autonomous cars still need charging or refuelling, cleaning, tyres, inspections, repairs and insurance. They also need somewhere to park when they are not working. If there is an accident or a technical problem, someone needs to deal with it and get the car back on the road. Customer support is still needed too when there are problems with bookings or payments, or when someone leaves something in the car.
Some of these tasks may even become more important. Robotaxis are expensive, and every hour a car spends charging, being cleaned or waiting for maintenance is an hour when it cannot take passengers. Moove, for example, already provides fleet ownership, depots, charging, maintenance and 24/7 operations for autonomous vehicles.
Drivers also do more than drive: they notice damage, report faults, help passengers and respond when something goes wrong. Without a driver, these responsibilities need clear processes and dedicated support. Existing fleet experience is an advantage, but operators will need to adapt it to vehicles running without someone behind the wheel.
There can be several companies behind one robotaxi ride. One provides autonomous driving technology, another may own the cars, and a local company can take care of the fleet. A platform such as Uber can then connect the cars with passengers. Sometimes one company may do several of these things, but this is not always the case.
Zagreb is one example. Pony.ai provides the autonomous driving system, Verne owns and operates the fleet, and Uber connects it with customers through its app. Autonomous rides became commercially available through Uber in August 2026 with a licensed operator onboard. On 10 September, Pony.ai and Verne also started fully driverless passenger test rides on a 22-kilometre route connecting parts of Zagreb with the airport. These are still limited test rides, not a fully driverless service across the whole city.
A similar model is being tested in Madrid. WeRide, Uber and AVOMO received permission in September 2026 to start testing and mapping under Spain’s ES-AV framework. The first 20 vehicles have an onboard specialist. WeRide provides the autonomous technology, Uber connects the cars with passengers, and AVOMO takes care of fleet operations. Commercial operations are planned for later in 2026, but the current permit is for testing and preparation rather than a general driverless taxi service.
In London, Wayve and Uber launched supervised autonomous passenger rides in September 2026. Customers can be matched with an autonomous vehicle through the Uber app, but there is still a licensed driver in the car.
The plans for the next few years are already much bigger. Pony.ai and Uber announced in August 2026 that they plan to deploy more than 2,000 robotaxis in Europe, starting with Zagreb and later expanding to four more European cities.
Bolt and Lucid announced another partnership in September, with Bolt aiming to deploy at least 25,000 autonomous Lucid vehicles across European cities. This is a future target, not 25,000 cars already operating today.
How these fleets are owned and operated may also be different from one city to another. Local regulations, available vehicles, charging and depot infrastructure and partnerships will all have an effect on how each service is set up.
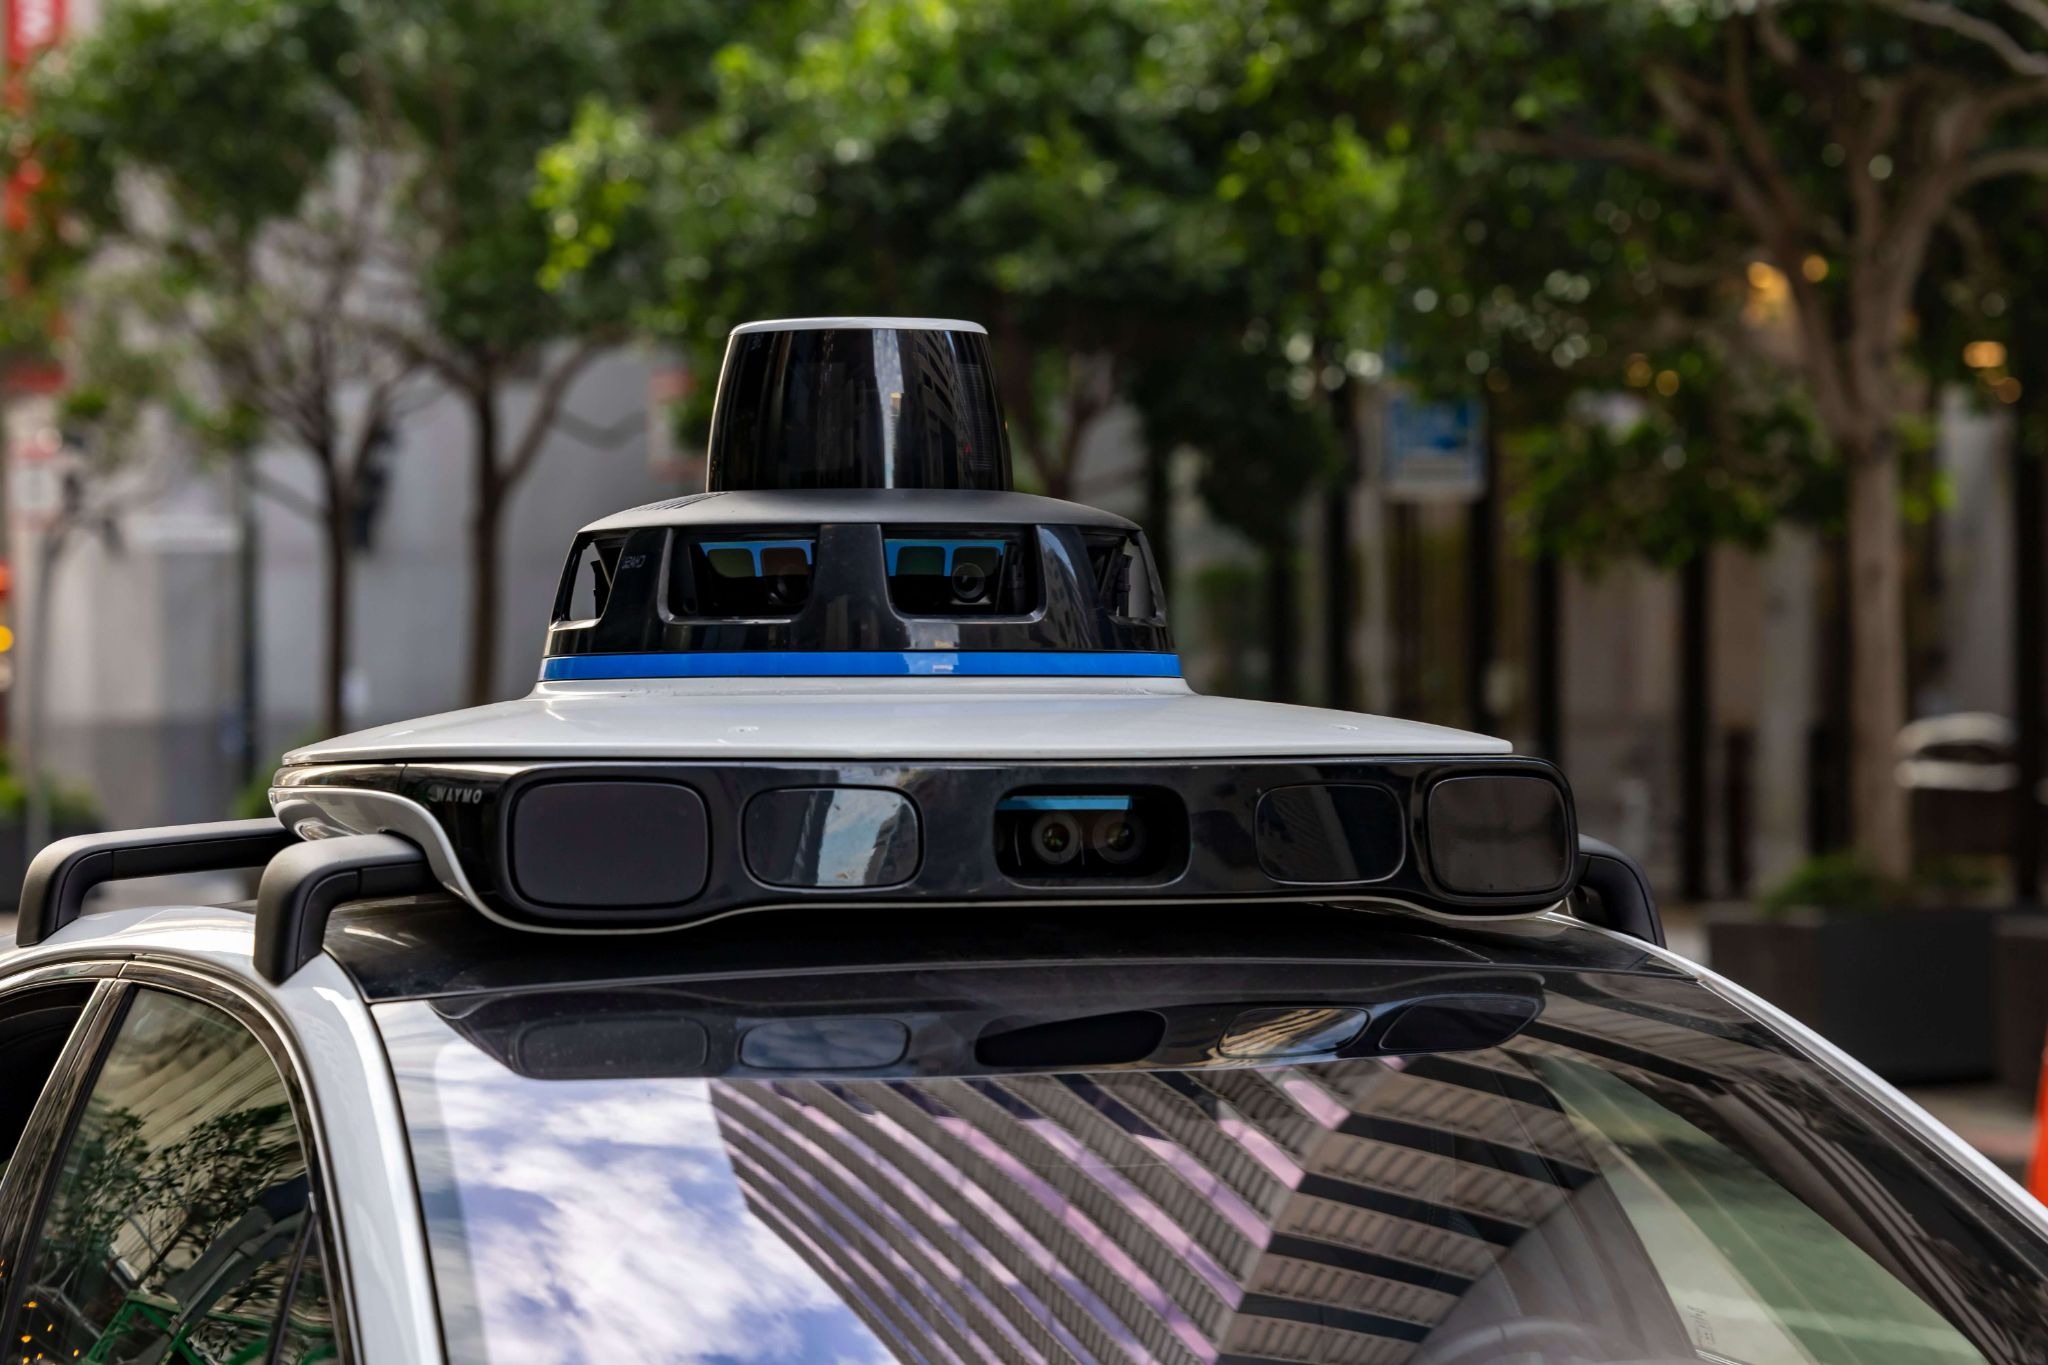
Taxi companies already do many of the things that would still be needed with an autonomous fleet. They maintain cars, deal with insurance and incidents, provide customer support and make sure enough vehicles are available. Some also already have their own depots, charging infrastructure or maintenance partners.
One possible model can already be seen in Zagreb. A local company owns and operates the autonomous fleet, while a larger ride-hailing platform brings customers. In the future, an existing taxi company could potentially have a similar role. Instead of managing cars and drivers, it could manage autonomous cars that receive bookings through a larger platform.
This does not mean platforms such as Uber will always rely on other companies to own the cars. Uber’s 2026 agreement with Rivian includes up to $1.25 billion in milestone-dependent investment and says that Uber or its fleet partners may purchase the autonomous vehicles. Uber is also developing infrastructure for autonomous fleets. Different ownership models are therefore possible.
Autonomous vehicles could also become interesting for rental and car-sharing companies, although this is probably further in the future. These businesses already manage vehicles, maintenance, cleaning, charging, bookings, customer accounts and payments, so much of the practical work is similar.
Autonomous driving could also change how rental and sharing cars are moved. Today, an employee may need to drive a car from one location to another. In the future, the vehicle could potentially do this itself within an area where autonomous driving is approved. It could even become possible for a rental car to drive itself to a customer’s pickup point.
Without drivers, it becomes especially important to understand how much time each vehicle is actually working. Every hour spent charging, being cleaned, waiting for maintenance or simply sitting unused means less time carrying paying passengers.
Some useful KPIs could be available hours per vehicle, paid trips per vehicle each day, revenue per available vehicle/day, empty kilometres, charging and maintenance downtime, cost per trip and incidents that need human help. These are most popular robotaxi industry KPIs of what a company could measure during a pilot.
For example, if cars spend too much time waiting to charge, the charging setup may need to change. A lot of empty kilometres could mean the cars are not in the right places, while too much maintenance downtime could make a vehicle more expensive to operate.
For either model, the business case depends on the partnership terms: who finances the vehicles, who carries the risk when demand is low, and how revenue and operating costs are shared. Operators should assess what remains after vehicle financing, insurance, charging, maintenance and partner fees. Depots, local service teams and reliable fleet availability could make an operator a valuable partner, but profitability still needs to be demonstrated.
One option for taxi fleets would be to work with an autonomous driving company and a larger ride-hailing platform. The local company could own or manage the cars and take care of the fleet, while customers book their rides through the larger platform.
Another option could be possible in cities where large ride-hailing platforms are not present or have limited coverage. A local company could work with an approved AV provider while using its own app, bookings, payments, customer support and fleet management.
In both cases, a company cannot simply buy autonomous cars and start offering rides. The technology needs to be approved, and local rules have to allow the service. These rules will also be different across Europe. Great Britain, for example, introduced its Automated Passenger Services permitting framework in 2026. Services similar to taxis or private hire vehicles need consent from the relevant local authority, while responsibility for the autonomous driving technology and the passenger service are treated separately.
A company does not need to have autonomous cars today to start preparing. A good first step is understanding the current fleet in detail – what each vehicle costs, how many hours it is available, how much time it spends charging or being repaired, and when cars are used the most.
Charging, cleaning, maintenance and depot processes are also worth looking at because all of these will still be needed with autonomous vehicles. A company interested in an AV pilot can then choose a location and use case, look at the local permit process and start talking to autonomous driving technology providers.
The software will also need some preparation. Customers still need to book and pay for rides, while the company needs fleet information, customer support, reporting and connections between its own systems and the AV technology. Starting with a small pilot makes it possible to test all of this before trying to build a larger service.
ATOM Mobility already provides many of the software functions used by taxi, ride-hailing, rental and sharing companies, including customer apps, bookings, payments, fleet management, maintenance tasks, analytics and APIs. Its ride-hailing software includes passenger and driver apps, dispatch, payments, fleet data, analytics and integrations. The ATOM Mobility API can also exchange data about vehicles, bookings, rides, payments, telemetry and maintenance tasks.
ATOM Mobility does not provide autonomous driving technology. This would come from a specialised AV company, and each project would have its own technical requirements and local approvals. For an AV pilot, ATOM Mobility could work with the fleet company and AV provider on the rider experience, integrations, fleet management and the data needed to measure how the pilot is working.
If you operate a taxi, rental or sharing fleet and want to explore an AV pilot, ATOM Mobility can help plan the booking and fleet-management setup, integrations and metrics you would need to test together with an AV technology partner.

At ATOM Mobility, we’re always looking for ways to improve the user experience. One of the most requested features from our customers has been alternative login options. And now, we’re happy to announce that Apple and Google sign-in options are finally here!
Most mobile apps rely on phone number verification for sign-ups and logins. This is also the case for ATOM Mobility, where users verify their phone number using a One-Time Password (OTP). We use trusted partners like Twilio, Dexatel, and others to ensure secure phone verification. Big companies like Uber, Bolt, and inDrive also follow this method because it helps prevent fraud and unauthorized access.
However, we know that not everyone wants to use their phone number every time they log in. Some users prefer quicker options, especially if they’re alreadyuse Apple or Google on their devices. That’s why we’ve now added these alternatives.

According to global data, a significant number of people prefer logging in with their existing accounts rather than typing in a phone number. Research shows that about 60-80% of users choose social logins if given the option. That’s a huge number! By adding Apple and Google login, we’re making it even easier for users to sign up and start using your app instantly.
Many popular apps and platforms already offer these sign-in options because they reduce the time it takes for users to access services. The fewer steps involved, the more likely users are to complete registration rather than abandoning the process midway. For businesses, this translates to higher conversion rates and more engaged users.
Adding Apple and Google login options isn’t just about convenience. It has real benefits for operators as well:
It’s important to note that phone number verification still plays a big role in fraud prevention. If users sign in without verifying their number, there’s a higher risk of fake accounts. That’s why we’re keeping the OTP method as the default while offering Apple and Google login as an alternative.
Many companies, including ATOM Mobility, prioritize fraud prevention. While Apple and Google sign-in reduce the risk of failed logins, they also require additional monitoring to ensure that the platform remains secure. Implementing fraud detection measures alongside these sign-in options can help maintain a balance between user convenience and platform security.
The updated login screen will now include Apple and Google sign-in buttons alongside the phone number option. Users can choose their preferred method, making the process faster and more flexible.
If you are an ATOM Mobility customer, enabling this feature in your app settings is simple. Once activated, users will see the Apple and Google login buttons immediately when they open the app. This small but powerful change can lead to more completed registrations and a smoother onboarding experience.
This is just one of the many improvements we’re bringing to ATOM Mobility. We’re constantly working on new features to enhance the user experience and streamline operations. Check out our other top features:
At ATOM Mobility, we believe in continuous innovation. Now that Apple and Google login options are live, we are exploring other ways to simplify user access and improve security. Some potential future developments include:
With Apple and Google login now available, signing up for ATOM Mobility-powered apps is easier than ever. Whether users prefer OTP verification or a simple one-tap login, they now have more choices. This update is all about making the experience smoother and increasing the number of successful registrations.
If you’re an ATOM Mobility customer, make sure to enable this feature and give your users the flexibility they want. And if you need any help, feel free to reach out to our team!
Stay tuned for more updates as we continue to improve the platform!

🚲 Donkey Republic is proving that bike-sharing can be profitable, while many competitors are struggling to stay on the road to success. Donkey Republic is partnering with cities, keeping costs low, and focusing on bikes. With more cities pushing for car-free mobility, can Donkey Republic continue to grow?
Bike-sharing has had a wild ride over the past ten years. Some companies threw thousands of bikes onto city streets without permission, while others spent tons of money but couldn’t figure out how to make a profit. Donkey Republic took a different approach—and it worked.
Started in Copenhagen in 2014, Donkey Republic didn’t rush to expand or rely on big investors. Instead, it focused on working with cities, keeping things simple, and making sure the business could actually make money. In 2023, the company earned €15.4 million (DKK 115.2 million), up 70% from the previous year, and, more importantly, it made a profit of €1.27 million (DKK 9.5 million).
The company’s founder, Erdem Ovacik, got the idea when he saw a friend using combination locks to share bikes with others in Copenhagen. He figured there had to be a better way. The answer? A mobile app and smart locks, so people could rent a bike quickly without needing a docking station.
In 2015, Donkey Republic started with just 30 bikes. Instead of flooding the streets with bikes and hoping for the best, it worked directly with city governments to get approval. That helped avoid the problems that companies like Ofo and Mobike faced when they expanded too fast and then collapsed.
A lot of bike and scooter companies try to grow as fast as possible, spending loads of money and hoping to make a profit later. Donkey Republic didn’t do that. By 2020, it had expanded to 13 countries, including Germany, Spain, the Netherlands, and Finland, but always in a controlled way.
A big part of its success comes from working with cities instead of fighting them. Instead of just dropping bikes on the street and hoping no one complains, Donkey Republic made agreements with local governments. This means the company doesn’t have to worry as much about sudden bans or changing rules.
For example, in 2023, Paris banned rental e-scooters, which was a disaster for other companies. But because Donkey Republic focuses on bikes, it wasn’t affected.
Donkey Republic has shown impressive financial progress in recent years. In 2023, the company reported a revenue of DKK 115.2 million – a 70% increase compared to the previous year. Even more importantly, they achieved a positive EBITDA (Earnings before interest, taxes, depreciation, and amortization) of DKK 9.5 million, marking a shift toward profitability.

2024 has been even stronger for Donkey Republic. The company reported a revenue of DKK 145 million, representing a 25% increase from 2023. For the first time, they also recorded a positive EBIT of DKK 1 million. This shows that their long-term strategy of working with cities and optimizing operations is paying off.
Several factors have contributed to Donkey Republic’s success:
While Donkey Republic has shown that micromobility can be profitable, the road ahead isn’t without challenges. Competition is fierce, and other companies are rapidly expanding their e-bike fleets to compete in Donkey Republic’s space. Additionally, while city partnerships provide stability, they also limit rapid expansion – municipal contracts take time to secure, and some cities prefer to invest in their own public bike-sharing programs.
Still, Donkey Republic is betting that the demand for sustainable, city-friendly transport will only grow. With urban areas across Europe cracking down on car use – such as London’s Ultra Low Emission Zone (ULEZ) and Paris’s car-restriction policies – bike-sharing is well-positioned to thrive.
So while scooter operators continue to battle regulatory headaches and profit struggles, Donkey Republic is proving that a disciplined, city-first approach might just be the key to lasting success in micromobility.

🚗📉 Why do big car brands struggle in carsharing while independent startups thrive? OEMs like Volvo and SEAT have shut down, but new players like Kia are stepping in with smarter strategies. Meanwhile, independent operators like GreenMobility are scaling fast. 🔍 What’s the secret to success in carsharing? It’s all about adaptability, cost control, and tech partnerships.
The carsharing industry is at a crossroads. Once hailed as the future of urban mobility, it has seen a mix of success and failure, with some players thriving and others closing shop. So we ask: why do some carsharing ventures fail while others continue to grow? And more importantly, what does it take to run a sustainable and profitable carsharing business in today’s competitive landscape?
Recent developments have been telling. Two OEM-backed carsharing ventures have recently shut down, while independent operators continue to expand, and a new entrant – Kia – has just launched its own service. This article takes you into the challenges, key success factors, and the evolving role of technology in the industry.
Before diving into specific cases, it’s important to clarify what OEMs (Original Equipment Manufacturers) are and how they differ from startups. OEMs are traditional car manufacturers – companies like Kia, Volvo, or Ford – that primarily produce and sell vehicles under their brand names. Some OEMs have expanded into mobility services, including carsharing, but often struggle because their main focus remains on car sales.
In contrast, startups and independent operators like GreenMobility are built from the ground up as mobility service providers. They don’t manufacture cars but instead focus entirely on the carsharing experience, optimizing operations, technology, and customer service. This difference in core focus often determines success or failure in the carsharing industry.
Automakers have long recognized the potential of carsharing as a way to diversify revenue streams, enhance brand loyalty, and explore new mobility business models. However, history has shown that simply putting cars on the streets and creating an app isn’t enough to make carsharing work.
Several OEM-backed carsharing services have struggled to maintain profitability. Volvo’s Volvo On Demand recently announced its closure as part of a broader strategy to optimize costs. Similarly, SEAT ceased operations at the end of 2024 due to declining demand and rising operational costs (€31 million total losses, with €11 million lost in 2023 alone, against a turnover of €16 million).
The challenges OEMs face in carsharing stem from several factors:
However, these closures don’t necessarily mean that carsharing itself is an unsustainable model. Instead, they highlight the need for a different approach – one that independent players are executing more effectively.

While OEM carsharing ventures struggle, independent operators like GreenMobility are experiencing growth. Unlike traditional automakers, these companies are built from the ground up as mobility service providers, allowing them to operate more efficiently.
GreenMobility’s growth can be attributed to:
By leveraging a digital-first approach, these companies are able to optimize vehicle utilization, reduce operational costs, and offer a seamless user experience—something OEMs often struggle to achieve.
Does KIA’s entry in carsharing bring new hopes?
Amidst the shifting landscape, Kia has entered the carsharing market with its new service, Hyr & Dela. Unlike previous OEM carsharing attempts, Kia's model focuses on businesses rather than individual consumers. This service allows companies to rent vehicles on a monthly basis and share them among employees, partners, or customers via a digital platform.
Why does this approach make sense?
If executed well, Kia’s corporate-focused carsharing model could prove to be a sustainable business approach, avoiding many of the pitfalls that plagued previous OEM carsharing attempts.

So, what can current and future carsharing ventures learn from these experiences?
Rigid business models and a lack of flexibility are major roadblocks to success. Carsharing services need to be highly adaptable, leveraging data to adjust pricing, fleet locations, and service offerings dynamically.
Carsharing is a capital-intensive business. Operators need to optimize fleet efficiency, reduce downtime, and control maintenance and insurance costs. This is where independent operators often outperform OEMs, as they are more agile in managing expenses.
A carsharing platform is only as good as its technology. Companies partnering with mobility tech providers like ATOM Mobility can benefit from advanced booking systems, automated fleet management, and data-driven decision-making—key elements for a seamless and cost-effective service.
Choosing the right city or region for carsharing is crucial. Factors like public transportation integration, parking regulations, and urban population density can make or break a carsharing business.
Carsharing is not just about providing access to vehicles—it’s about service excellence, convenience, and user experience. For OEMs to succeed, they need to rethink their approach and adopt a more customer-centric mindset.
The future of carsharing
The carsharing industry is at an inflection point. While some OEM-backed services have faced hurdles, independent operators like GreenMobility and strategic initiatives like Kia’s Hyr & Dela show that success is still possible with the right approach. The key lies in adaptability, cost control, technology integration, and market focus.
As the industry continues to evolve, Kia’s entry into corporate carsharing is an exciting development. With a smart strategy and strong execution, they have the potential to carve out a successful niche in the market.
We’ll be keeping an eye on Kia’s progress and, in the meantime, wishing them the best of luck in their new venture. Let’s hope they are here to stay!

Through collaboration with ATOM Mobility, Fair has been able to focus on what matters most – supporting drivers and redefining fairness – while leveraging ATOM Mobility’s expertise to handle the technical complexities of running a ride-hailing service.
The story of the ride-hailing service Fair, which focuses on driver empowerment, begins with a series of driver-led protests in Sweden a few years ago. Fast forward to now, the company operates in several cities and hundreds of drivers.
The ride-hailing industry has revolutionized urban mobility, but not without its challenges. While consumers enjoy affordable rides and seamless booking experiences, drivers often shoulder the challenges of the trade-off. In Sweden, where the cost of living is high, many drivers working for major ride-hailing platforms like Uber and Bolt have faced increasingly difficult conditions, from lower earnings per trip to rigid and punitive policies. We got in touch with Samual Nygren, Co-Founder of Fair, to discuss how a driver-first ride-hailing platform has emerged as a beacon of change.
Launch date: June 2023
Country: Sweden
App downloads: More than 20 000
App rating: 4.9/5
Web page: https://fairtaxi.se
App Store: https://apps.apple.com/se/app/fair-taxi/id6450279161
Google Play: https://play.google.com/store/apps/details?id=fair.app
The origins of Fair: A movement born from protests
Fair’s story begins with a series of driver-led protests in Sweden a few years ago. Disillusioned by shrinking incomes and unfair practices, drivers took to the streets of Stockholm, blocking traffic with their cars and holding up signs to demand change. Among them was a group seeking to create a nonprofit organization to advocate for better conditions. The founders of Fair became involved through a personal connection, seeing the drivers' struggles firsthand and recognizing an opportunity to support their cause.
Initially approached to help develop a website for the organization, Fair’s founders quickly saw an opportunity to go beyond advocacy and create something actionable: a competitive, driver-focused ride-hailing service. This marked the birth of Fair, a platform designed not just to offer rides but to redefine what fairness looks like in the gig economy.

A fairer model: Drivers in the driver’s seat
At its core, Fair operates on the principle of empowerment. Unlike traditional platforms where drivers often feel like disposable assets, Fair positions drivers as majority stakeholders in the company. This means they have a say in how the platform operates and directly benefit from its success. Key features of Fair’s model include:
- Lower platform fees: By keeping fees as low as possible, Fair ensures drivers retain a larger share of their earnings.
- Generous terms: Unlike major platforms where declining too many ride requests can result in penalties or even bans, Fair’s policies are designed to accommodate the realities of drivers’ lives.
- Nonprofit principles: Fair’s nonprofit orientation underscores its commitment to prioritizing drivers over profits.
This model has resonated deeply with drivers in Stockholm, where Fair first launched. With the success of its pilot, the company is now expanding into smaller cities across Sweden, taking its mission of fairness to a broader audience.
Beyond rides: Advocating for labor rights
Fair’s mission extends beyond providing a ride-hailing service. It aims to shine a spotlight on the working conditions that gig economy workers face – not just in ride-hailing but also in food delivery and other sectors. Historically, Sweden has been a stronghold for labor rights and fair pay, but the gig economy’s precarious working conditions have exposed gaps in this framework.
By raising awareness and leading by example, Fair seeks to spark a broader conversation about fairness in the gig economy. Its success could pave the way for similar initiatives in other industries and countries.

Partnering with ATOM Mobility: A platform built for change
Fair’s innovative approach is supported by its partnership with ATOM Mobility, a technology platform that powers mobility businesses around the globe. Through this collaboration, Fair has been able to focus on what matters most – supporting drivers and redefining fairness – while leveraging ATOM Mobility’s expertise to handle the technical complexities of running a ride-hailing service.
ATOM Mobility provides the infrastructure that allows Fair to offer seamless booking experiences for users and operational efficiency for drivers. This partnership ensures that Fair’s resources are directed toward growth and advocacy, rather than reinventing the wheel technologically. By working together, Fair and ATOM Mobility demonstrate how technology and purpose-driven businesses can create lasting impact in the gig economy.
Looking ahead: Building a fairer future
While Fair is still growing, its impact is already evident. By putting drivers first and demonstrating that fairness and profitability can coexist, Fair is challenging the status quo of the gig economy. The platform’s expansion into smaller cities and its growing driver community are testaments to the demand for a more equitable alternative.
As Fair continues to scale, it stands as a powerful example of how even small players can drive meaningful change. With its driver-first principles and commitment to fairness, Fair isn’t just a ride-hailing platform – it’s a movement.
"State of art technology in mobile apps and dashboard, very good SLA!"
"Easy, nice looking, continuously updated and developed every month and most of all very reliable with a extreme high uptime"
"We used to work with a different service provider which wasn't fitting our needs. Switching to ATOM was an improvement on our side"
Use test credentials to log in - Phone number: +1 123123123, Code: 777777
Driver App demo credentials - Email: test@atom.com, Password: driver