Opportunity for local shared mobility solutions as Bird and Micromobility.com struggle to turn a profit
May 30, 2023
min. read

Shared mobility companies Bird and Micromobility.com (formerly Helbiz) stormed onto the scene by introducing innovative and convenient transportation solutions, capturing the attention of urban dwellers worldwide.
However, as the micromobility industry enters a more mature phase, companies like Bird and Micromobility.com continue to grapple with obstacles when it comes to attaining financial stability. This has prompted them to reassess their excessively ambitious expansion strategies.
What factors contribute to these challenges, and what implications does this hold for the industry as a whole? Could local micromobility ventures provide a superior solution to meet the increasing demand for these services? Let's delve further into the financial predicament of Bird and Micromobility.com to gain a better understanding.
Established in 2017, Bird is a micromobility company that provides electric transportation solutions in the USA and Europe. Their range of shared vehicles includes e-scooters and e-bikes. The company also sells vehicles to distributors, retailers, and direct customers. With its headquarters located in Miami, Florida, Bird currently employs 425 individuals and operates in 105 cities.
Recently, Bird's first-quarter 2023 financials revealed challenges in maintaining ridership and revenue. Despite implementing cost-cutting measures, the company's performance failed to convince investors of its ability to achieve profitability – the company's stock plummeted nearly 19% after announcing its first-quarter earnings.
In 2022, Bird faced a challenging year. The company announced plans to completely exit Germany, Sweden, and Norway, as well as wind down operations in numerous other markets, primarily small to mid-sized, across the U.S., Europe, the Middle East, and Africa. They also reduced their staff by 23%.
Despite a positive revenue increase of 12.06% in 2022, the company faced substantial losses totaling $358.74 million, marking a significant 66.9% increase compared to 2021. The challenges continued in 2023 as Bird witnessed a decline in rides and deployed vehicles. With a net loss of $44.3 million recorded at the end of Q1 2023, it’s likely that the company will continue to downsize its operations.
Founded in 2015 and headquartered in New York, Micromobility.com delivers micromobility services in Italy, the United States, and Singapore (43 cities in total), which include e-scooters, e-bicycles, and e-mopeds. It also operates Helbiz Kitchen, a delivery-only ghost kitchen restaurant, and the Helbiz Live streaming platform. The company currently employs 284 people.
In 2023, the company, formerly known as Helbiz, underwent a rebranding and transformed into Micromobility.com Inc. This rebranding coincided with the plans to launch retail stores across the United States.
In 2022, Micromobility.com successfully completed its acquisition of Wheels, a shared micromobility operator, along with promises to its investors that the merger would lead to a doubling of annual revenue and facilitate the path to profitability. The company set its sights on capitalizing on Wheels' extensive user base of 5 million riders and venturing into untapped markets.
Despite these hopes, Micromobility.com experienced less than stellar financial results in 2022. The company achieved a revenue of $15.54 million, indicating a 21.07% growth compared to the previous year's $12.83 million. However, the company also incurred losses amounting to -$82.07 million, reflecting a 13.3% increase compared to 2021.
In 2023, Micromobility.com announced a reverse stock split to meet Nasdaq Capital Market's minimum bid price requirement and make their common stock more attractive to investors. This move didn't come as a surprise, considering that the company received a delisting warning from Nasdaq in 2022. Coupled with its enduring track record of operating losses and negative cash flows over time, the overall outlook of the company's financial performance is rather discouraging.
The difficulties faced by Bird and Micromobility.com can be partly explained by their venture capital-backed business model. They witnessed swift expansion while hemorrhaging substantial amounts of money. And the more they expanded, the more money they bled. Now, it’s unsurprising to witness their heavily subsidized business models shifting their priorities from aggressive growth to mitigating losses and striving for profitability.
In recent years, there has been a surge in the popularity of shared mobility special purpose acquisition companies (SPAC). These companies are created solely for the purpose of raising capital through an initial public offering and have no commercial operations of their own. The ultimate goal of a SPAC is to acquire or merge with an existing company.
Financial struggles have become a common theme among shared mobility SPACs This can be attributed to the rush of companies going public without first establishing a sustainable business model – and Bird and Micromobility.com are no exception to this trend. The challenges faced by these companies emphasize the significance of building a strong and viable foundation prior to entering the public market.
The relentless pursuit of expansion has proven to be an ineffective strategy. For instance, some experts suggest that Bird's decision to outsource its operations to franchises made it harder to persuade cities and secure contracts. Their emphasis on breadth rather than depth resulted in a lack of understanding regarding local communities and the nuances of local legislation. As a result, major players like Bird and Micromobility.com have been withdrawing their fleets from “less profitable” cities.
According to a McKinsey study, the shared micromobility market has the potential to reach a staggering $50 billion to $90 billion by 2030, with an estimated annual growth rate of approximately 40% between 2019 and 2030. By 2030, shared micromobility could constitute around 10% of the overall shared mobility market.
In this context, the recent financial challenges faced by Bird and Micromobility.com should not be seen as indicative of a bleak future for the entire industry. Instead, these setbacks highlight the inherent unsustainability of aggressive and expansive business models within the shared micromobility landscape.
Local operators with smaller ground teams enjoy a notable edge over companies like Bird and Micromobility.com. By focusing on underserved markets and having an intimate understanding of their communities, these operators can deliver superior service while maintaining lower costs and stable profit margins.
Returning to Bird's Q1 2023 financial report, they also reported 0.9 rides per deployed vehicle per day. Now, let's compare this figure to other operators. We conducted a survey involving two EU-based operators that make use of Atom Mobility:
As fleet sizes increase, the average ride per vehicle tends to decrease, as seen with Operator 1 and Bird. However, the figure from Operator 2 highlights the potential for local operators to thrive in underserved cities that larger shared mobility companies may neglect.
We have seen examples of this – Go Green City, a Swiss electric moped-sharing company, presently provides its services in Zurich and Basel. Their small, tightly-knit team prioritizes local knowledge, enabling them to operate with enhanced flexibility and agility – a level of service that larger companies like Bird or Micromobility.com will find challenging to match. Overall, more than 300 projects have successfully launched their shared mobility ventures with Atom Mobility's assistance, operating in over 140 cities across the globe.
As the desire for shared micromobility services grows – with a focus on community safety and the ethical integration of these modes of transportation into the overall urban transit system – it seems that local operators have a distinct edge over large multinationals.
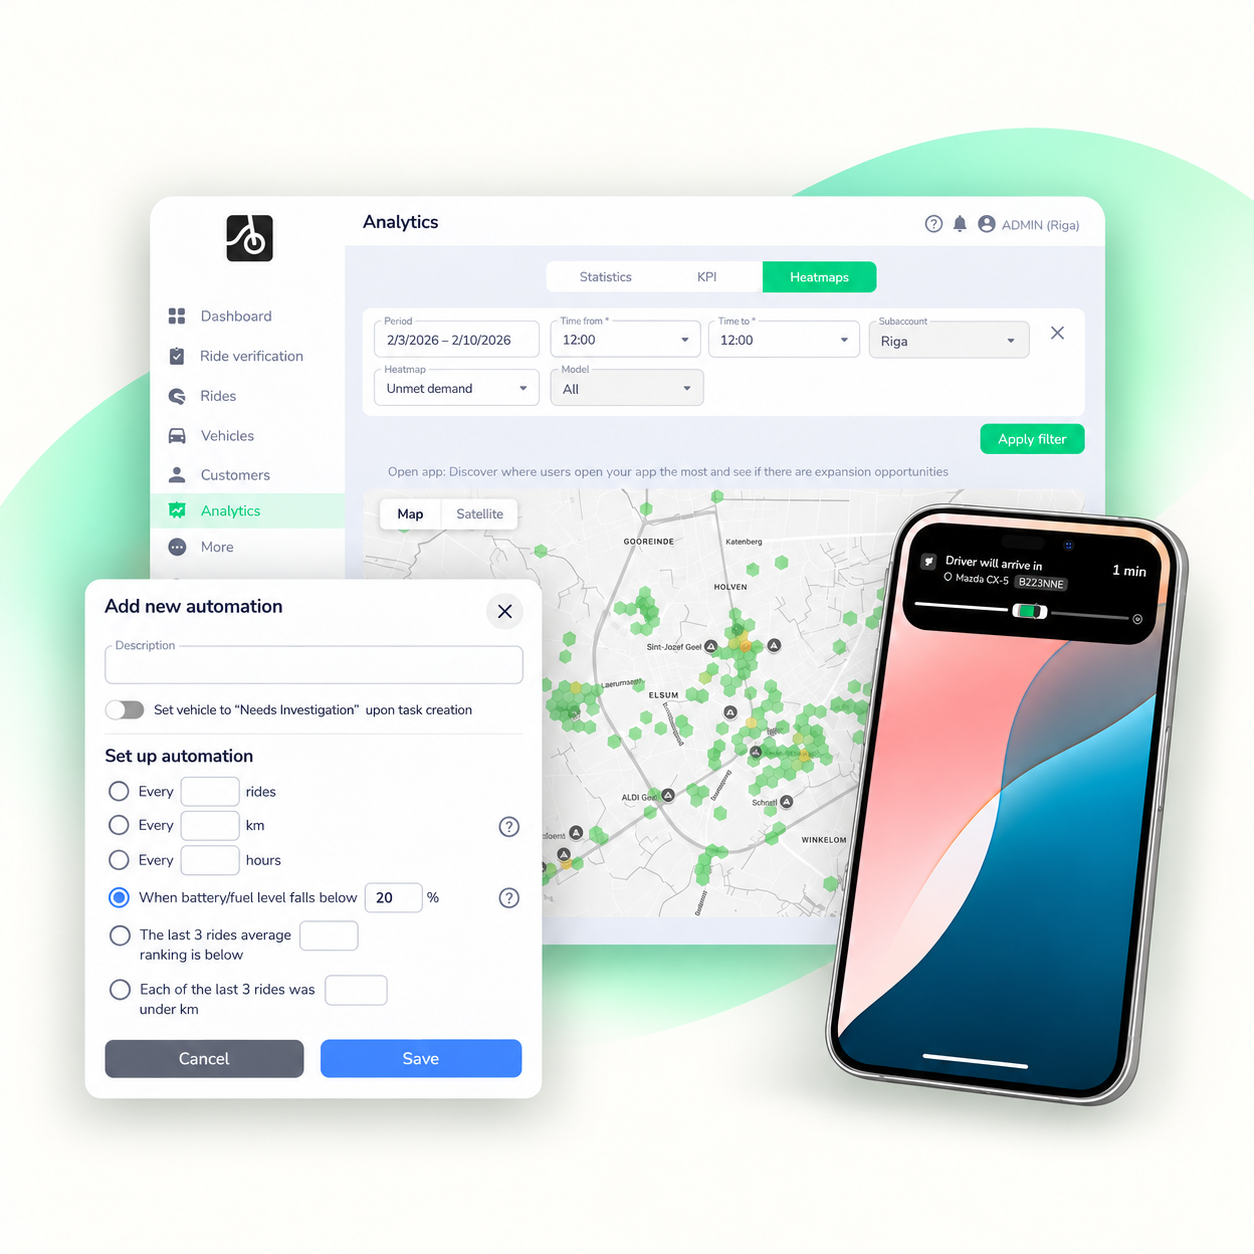
🚀 ATOM Mobility ships 7-15 new features every month, alongside smaller improvements and fixes. Explore five recent highlights: unmet demand heatmaps, automated fleet tasks, field-team performance tracking, new subscription types, and lock-screen ride updates - helping operators run more efficient fleets and improve the rider experience.
Knowing where customers need vehicles, keeping field teams productive, and giving riders reasons to return are everyday priorities for mobility operators. Every month, ATOM Mobility ships 7-15 new features, alongside smaller improvements and fixes. Here are five highlights from our recent releases - and how they can help operators improve fleet performance and the customer experience.
A customer opens your app, finds no vehicle nearby, and leaves. Your ride history alone won’t show you that missed opportunity.
The Unmet Demand heatmap highlights areas where users open the app but cannot find an available scooter, bike, or car within 1000 metres radius. Beyond colour-coded hexagons, on zoomed in view it shows the number of unique users who searched for a vehicle in each area without finding one nearby.
Use these insights to identify gaps in fleet coverage, prioritise rebalancing, and assess potential parking locations. Alongside seeing where rides happen, you can now understand where potential demand goes unmet.

Keeping a fleet ready for customers means staying on top of maintenance, charging, refuelling, and service quality. As your fleet grows into hundreds of vehicles, manually tracking when each vehicle needs attention becomes increasingly time-consuming.
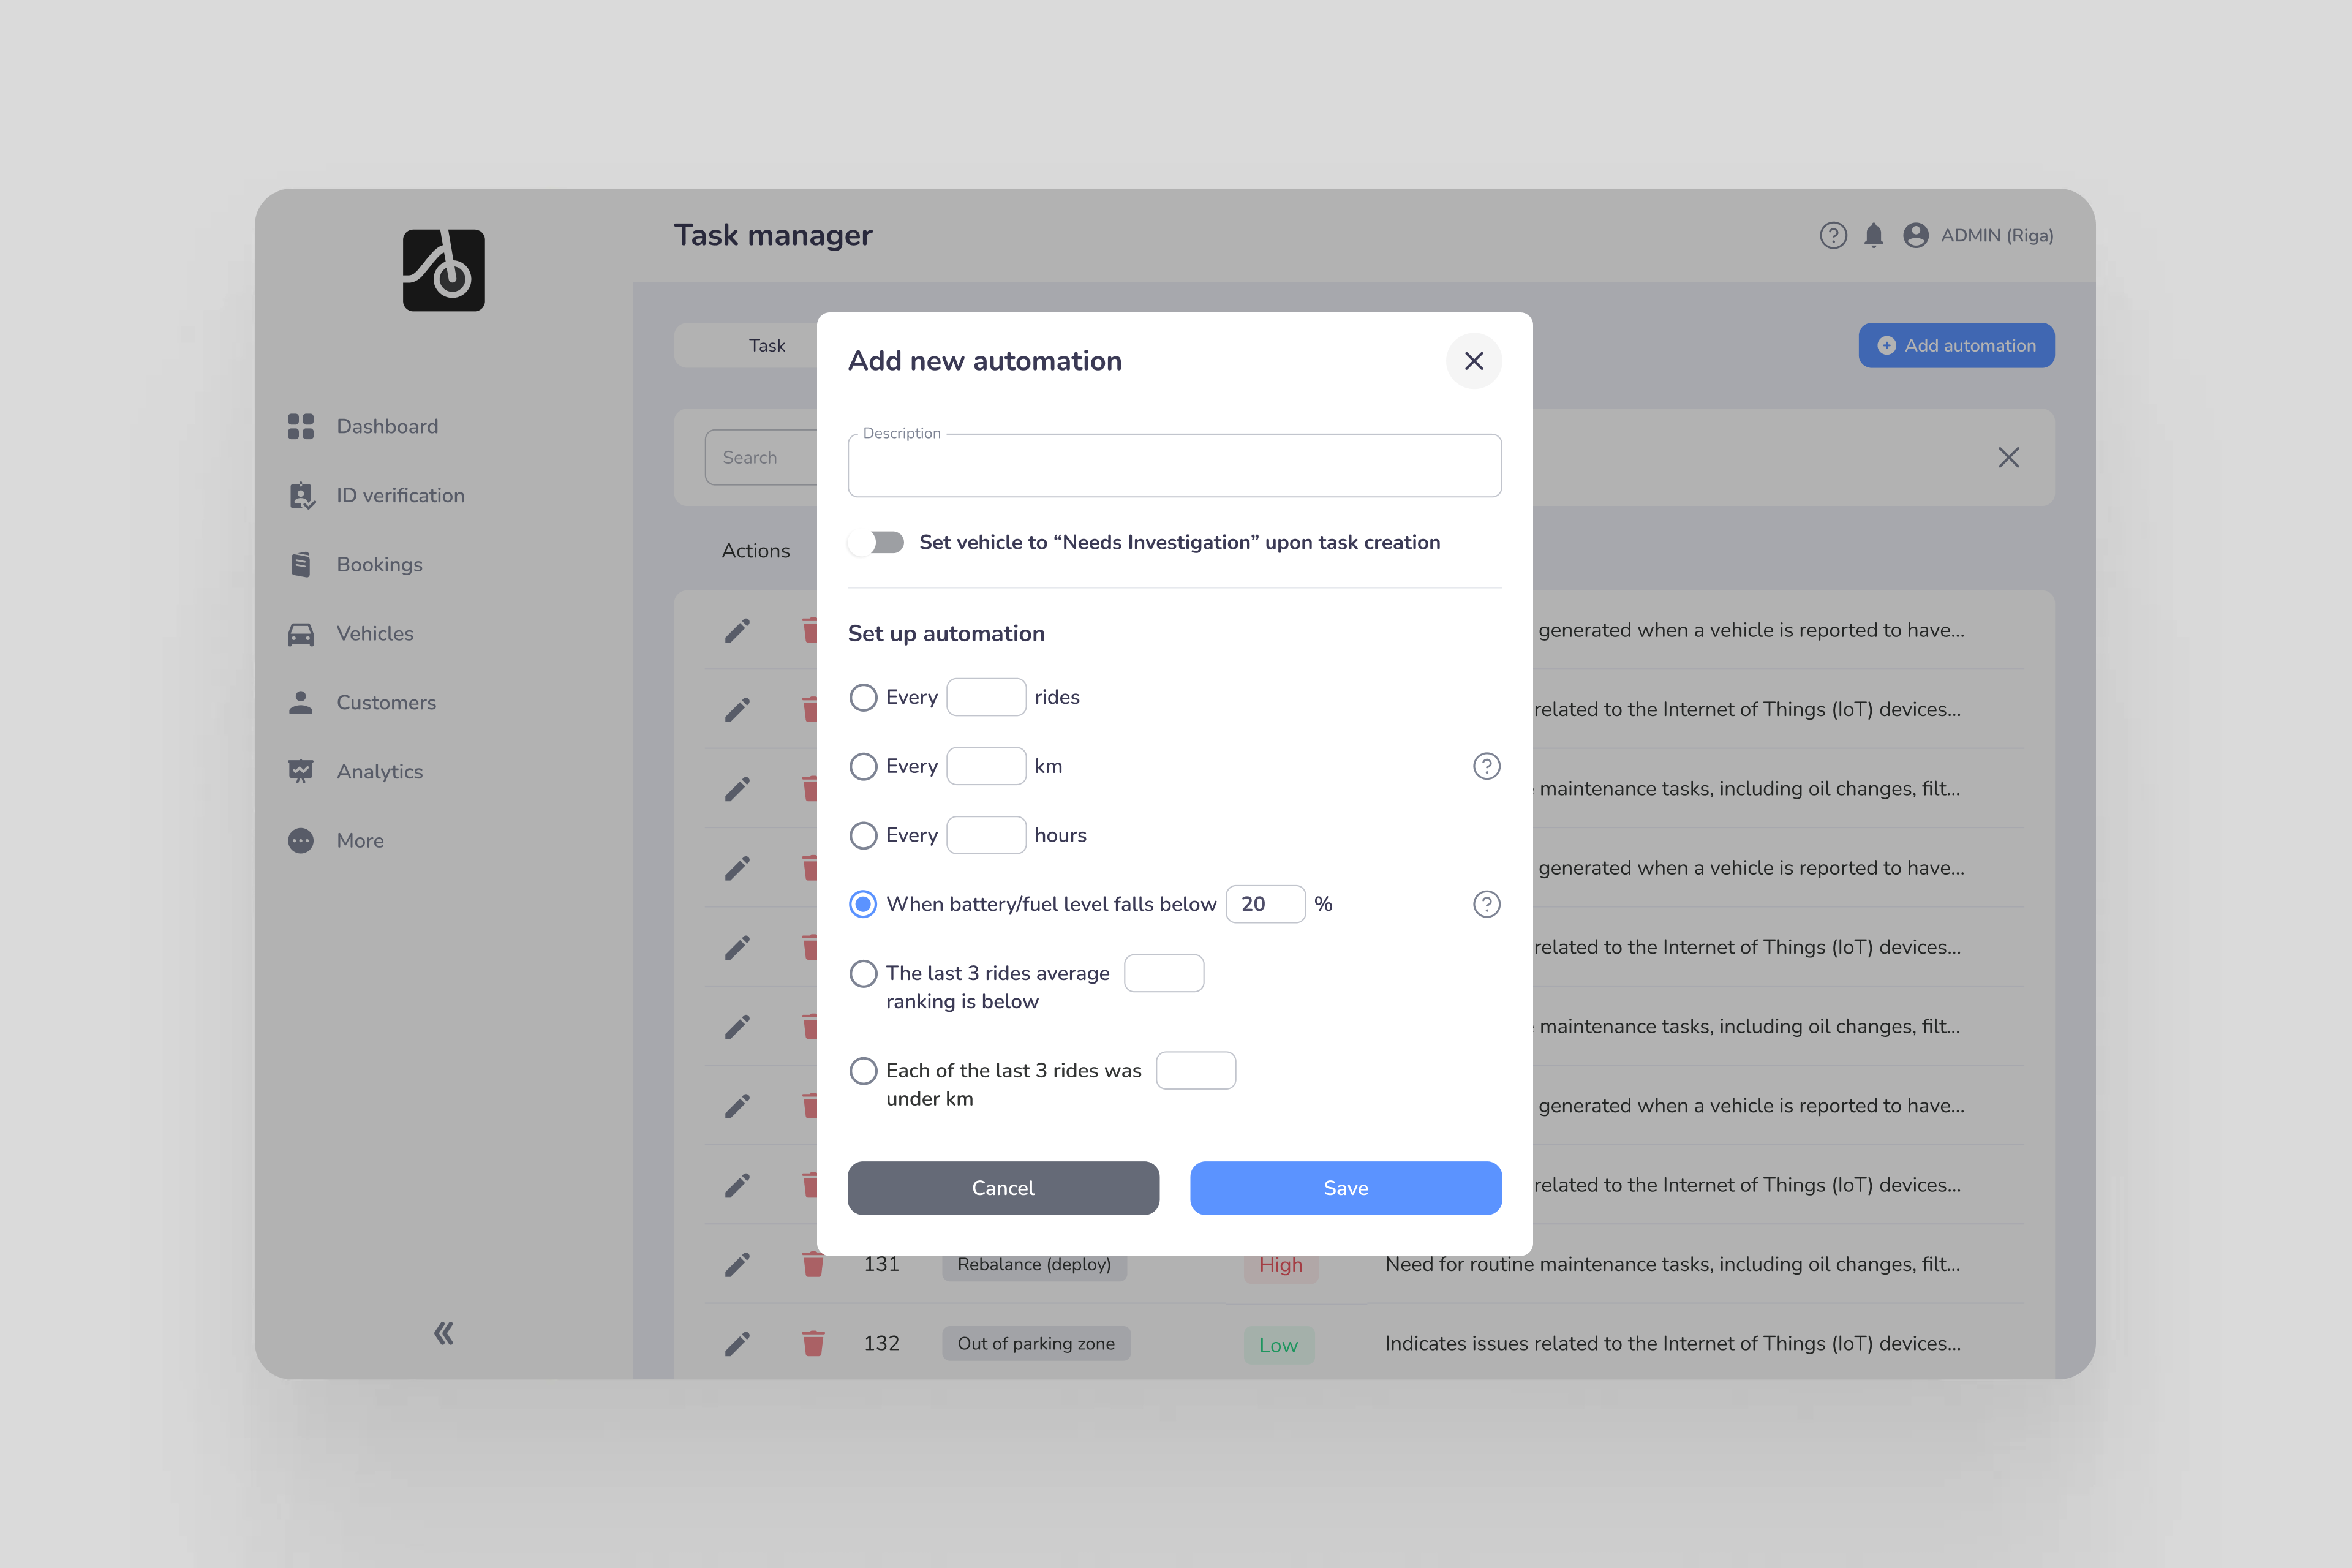
Task Manager automations turn vehicle usage, condition, and ride feedback into actionable tasks. Operators can configure tasks to be created:
These rules can support routine maintenance, trigger charging or refuelling tasks, and flag vehicles for inspection after low ratings or unusually short rides. For rebalancing tasks, if a customer uses the vehicle before collection, the task is automatically removed. This reduces manual monitoring and helps your team respond to vehicles that need attention.
How long do tasks take? Where does your team spend its time? Which operational bottlenecks need attention?
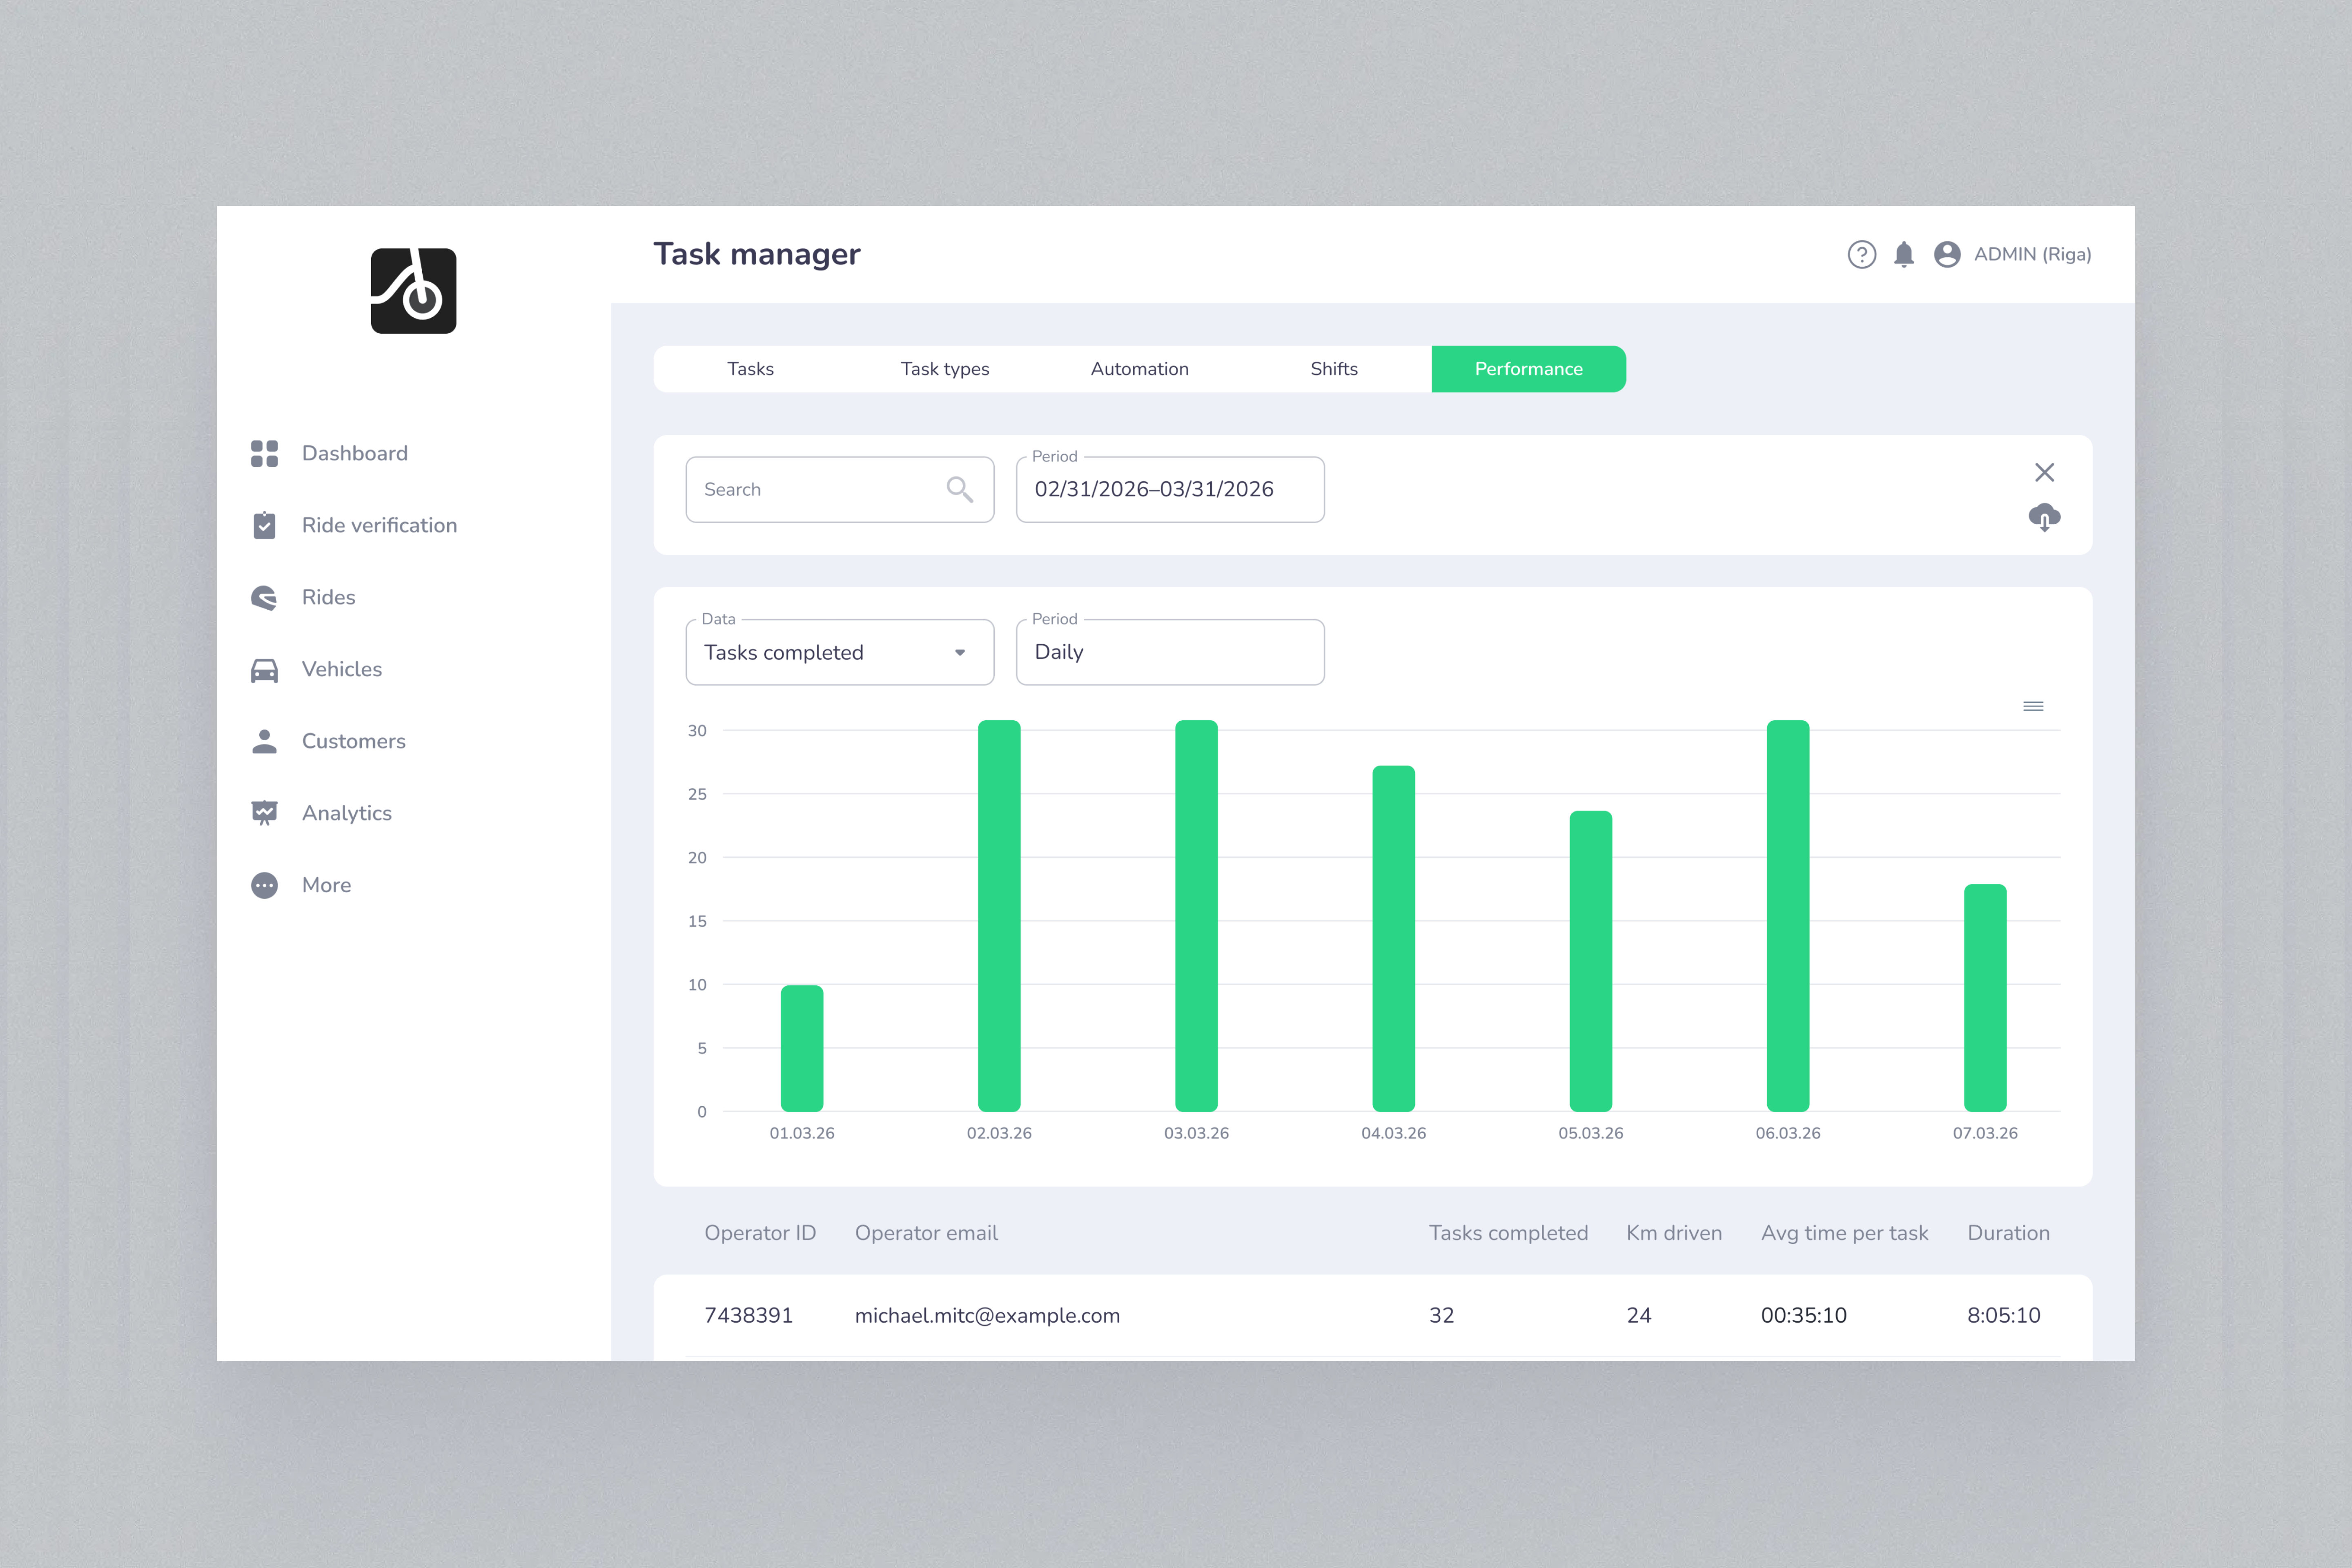
New Shifts and Operator Performance views give vehicle sharing and digital rental operators visibility into shift status and duration, distance driven, completed tasks, and average time per task.
Managers can use these insights to investigate delays, improve routes, and identify training needs. For example, longer task completion times could prompt a closer look at travel distances, workload, or the processes used at each location. Comparing results alongside task types and working conditions helps turn performance data into practical operational improvements.
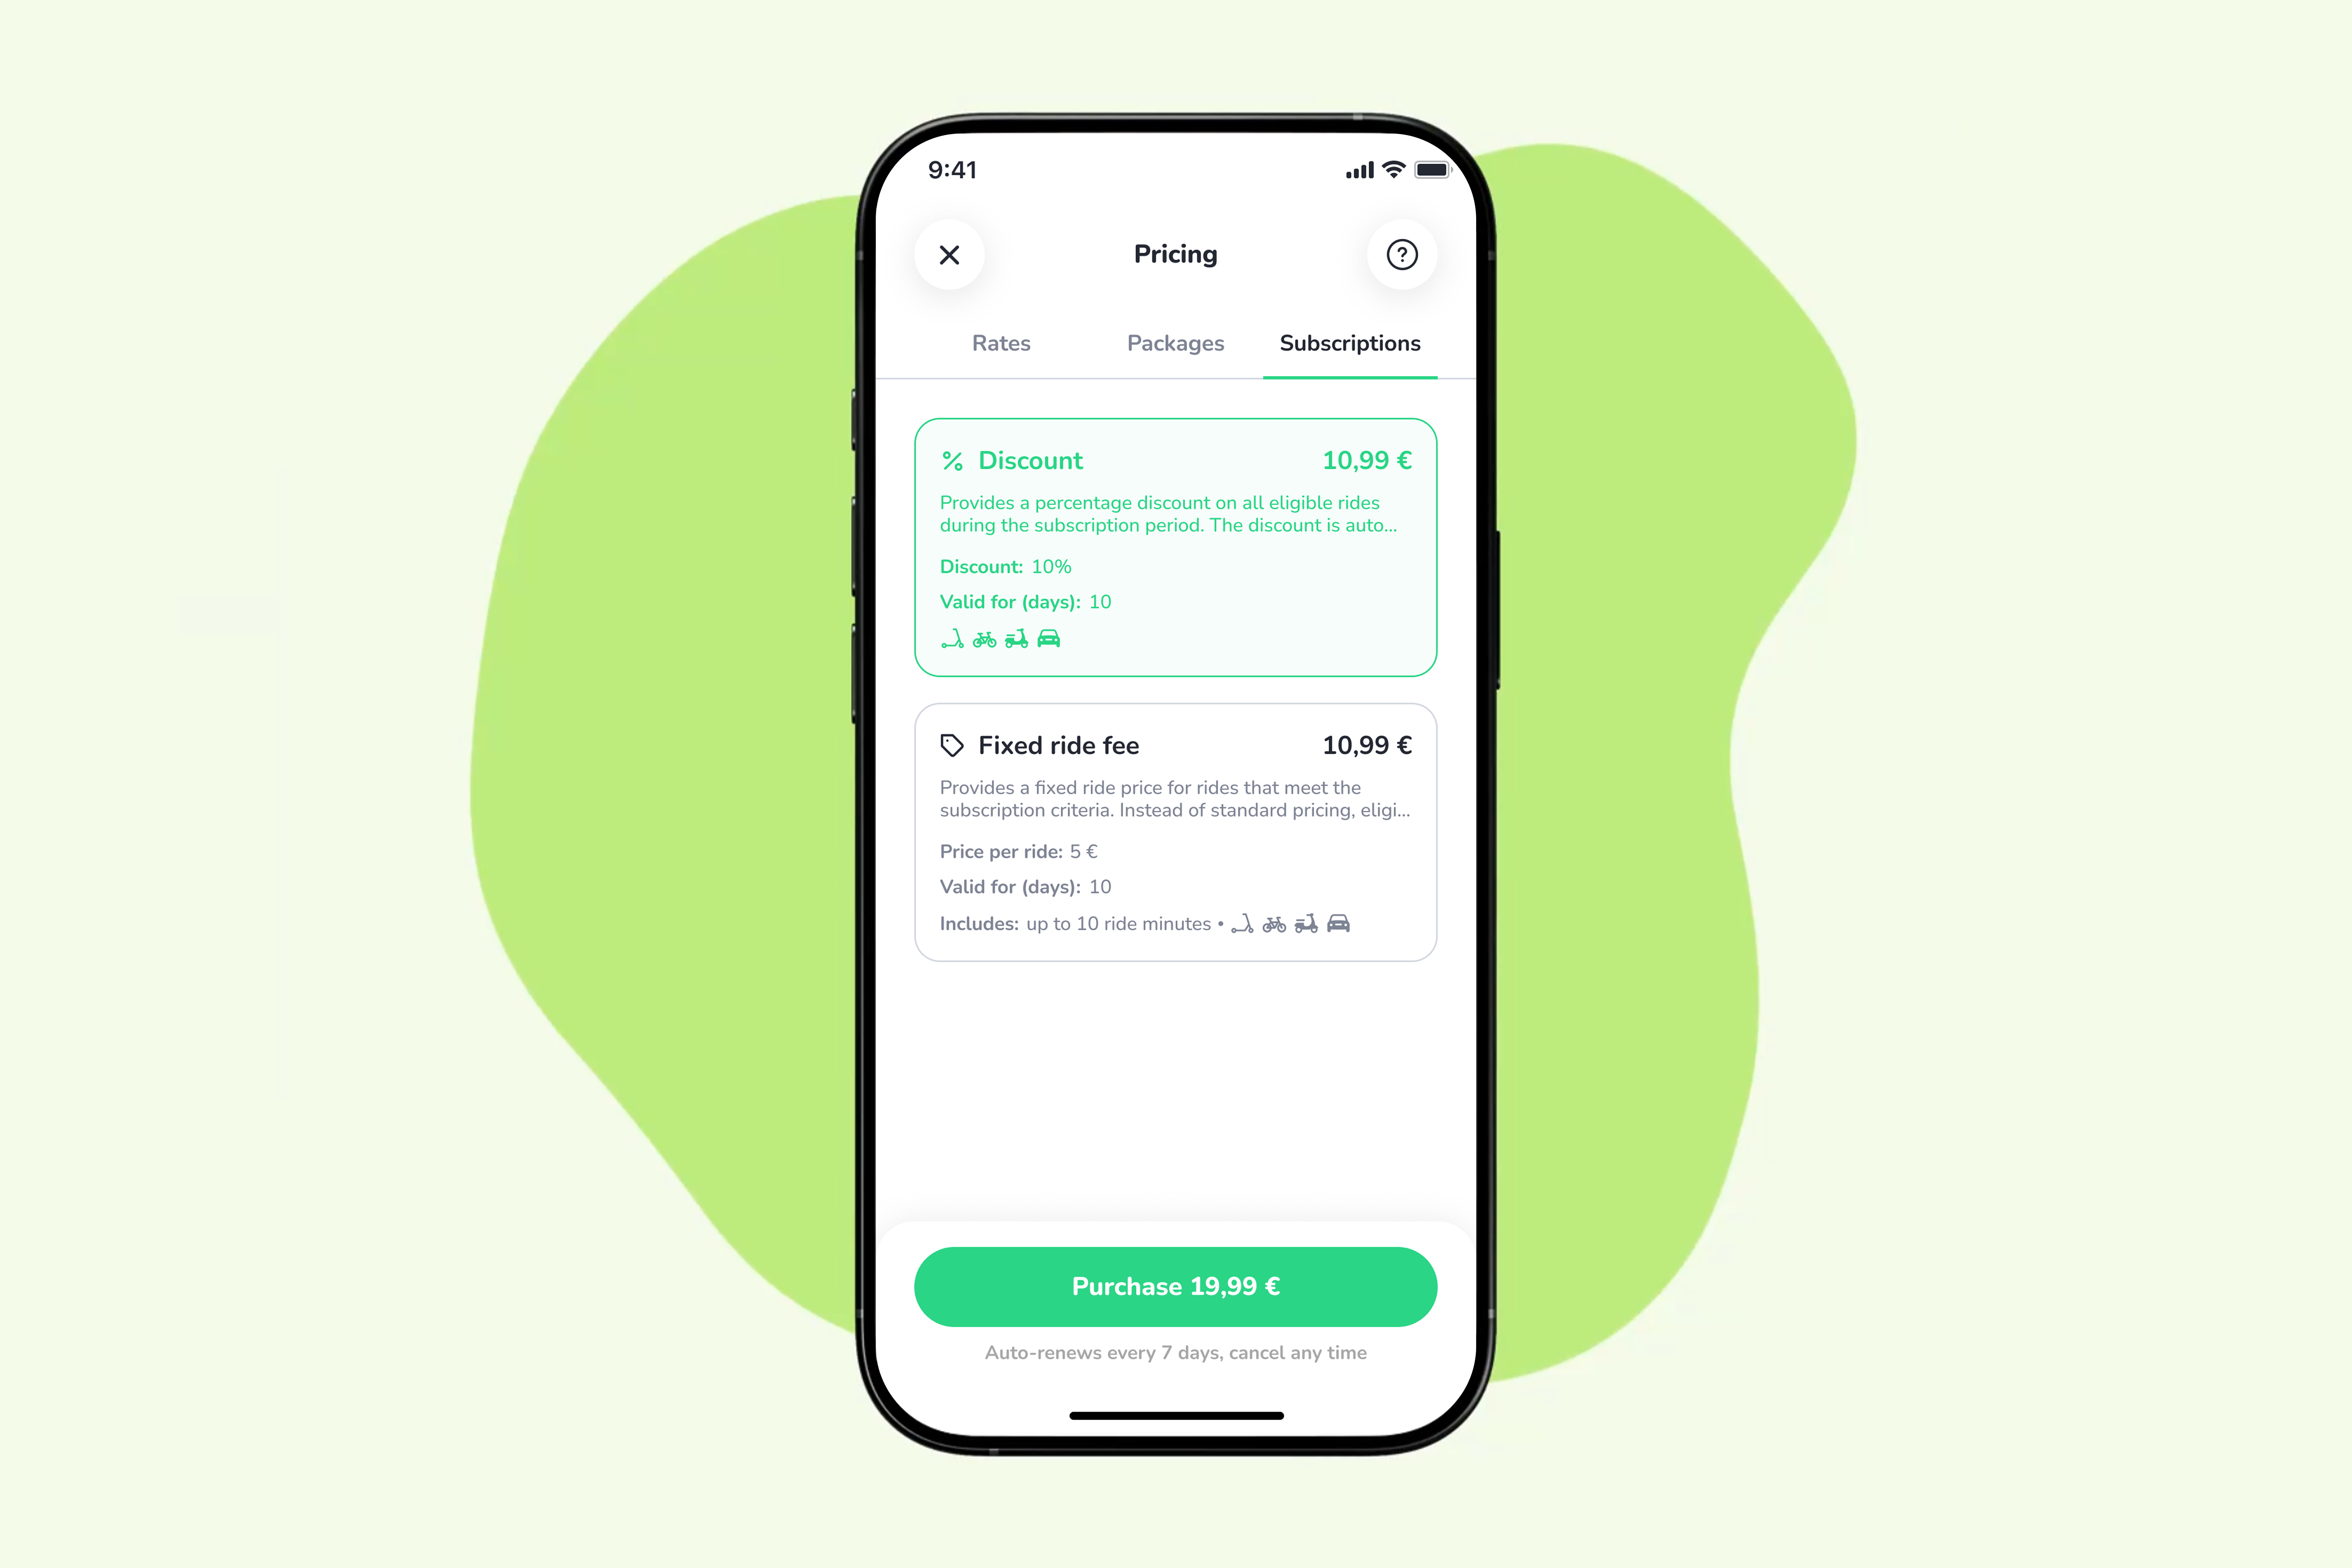
Different customers have different riding habits. Your subscriptions should reflect that.
ATOM Mobility now supports two additional subscription types:
These options let operators design offers around frequent riders and short-distance commuters. For example, you could offer subscribers a percentage discount on eligible rides or a predictable flat fee for qualifying short trips. Operators gain more flexibility to test offers that encourage repeat usage while fitting their pricing strategy.
Checking an active trip should be simple.
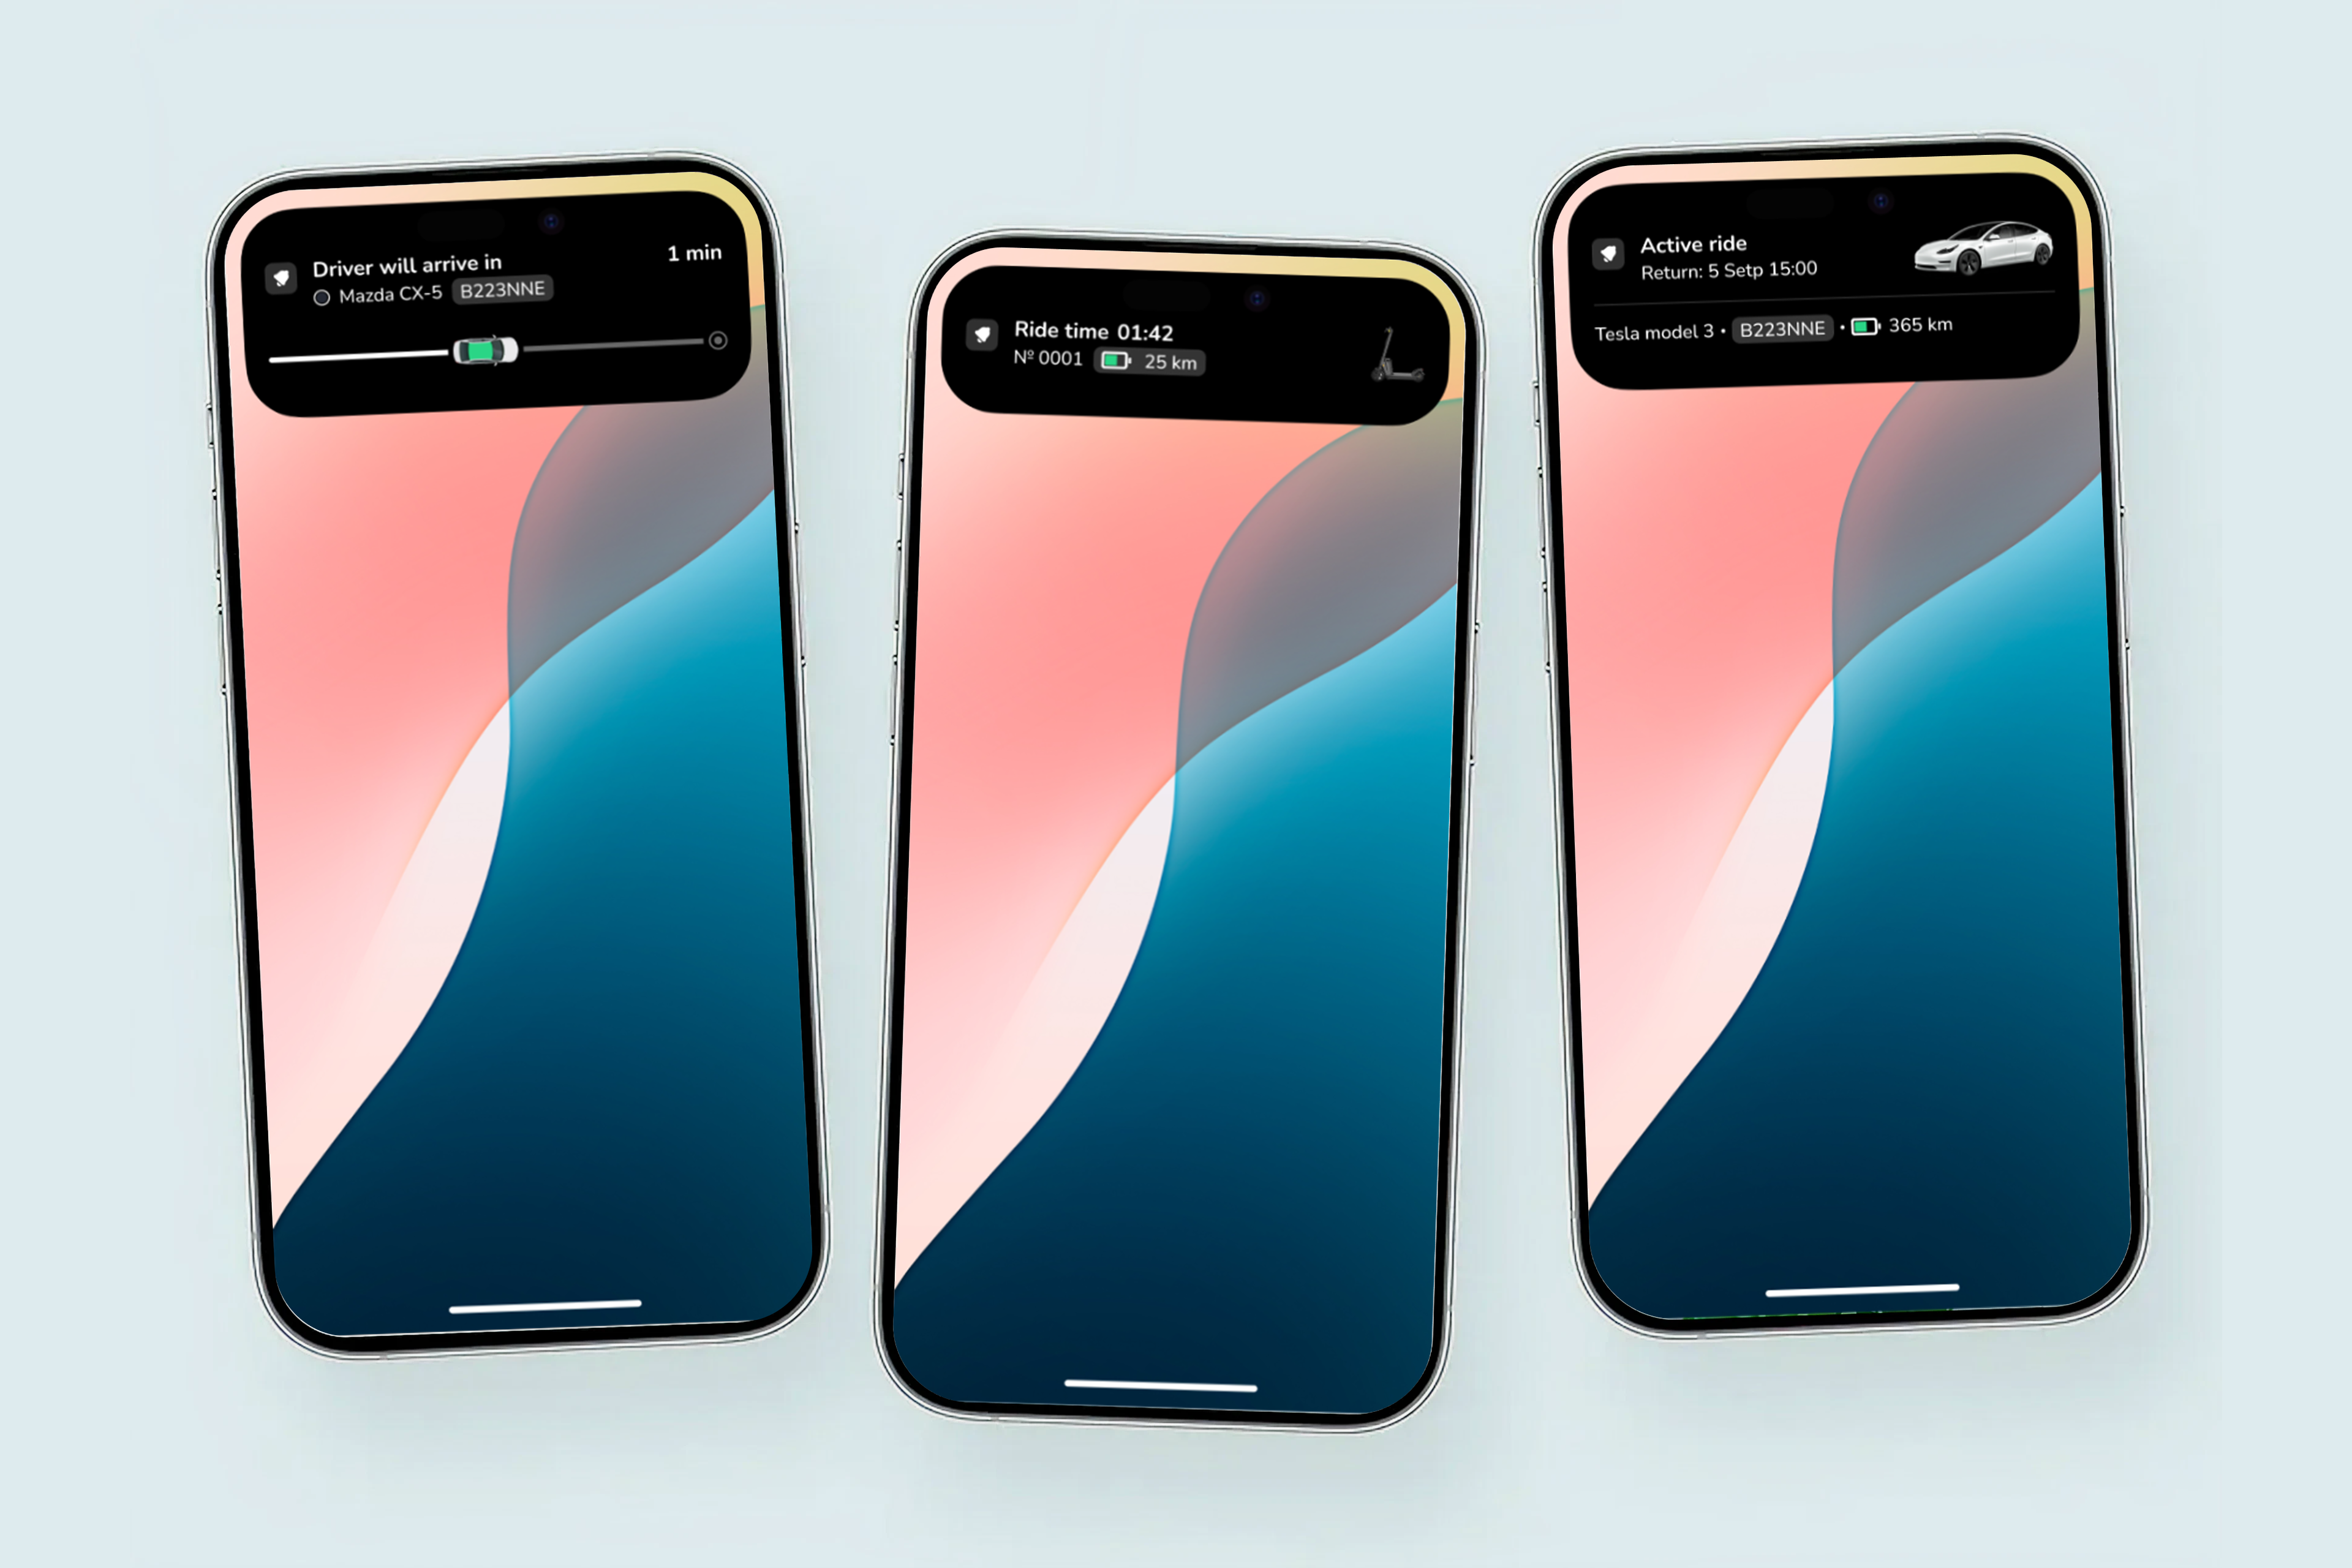
Live Activity lets customers view key ride information directly on their phone lock screen without repeatedly opening the app. Depending on the service, this can help them follow an active ride or a driver’s arrival.
Making this information readily accessible gives customers a more convenient way to stay informed throughout their journey.
These five releases are part of ATOM Mobility’s ongoing product development, helping operators identify unmet demand, automate routine coordination, understand field-team performance, and improve the customer experience.
Exploring software for your mobility business? Book a demo to see how ATOM Mobility can support your fleet, team, and customers.
Explore more product updates at https://www.atommobility.com/atomupdates
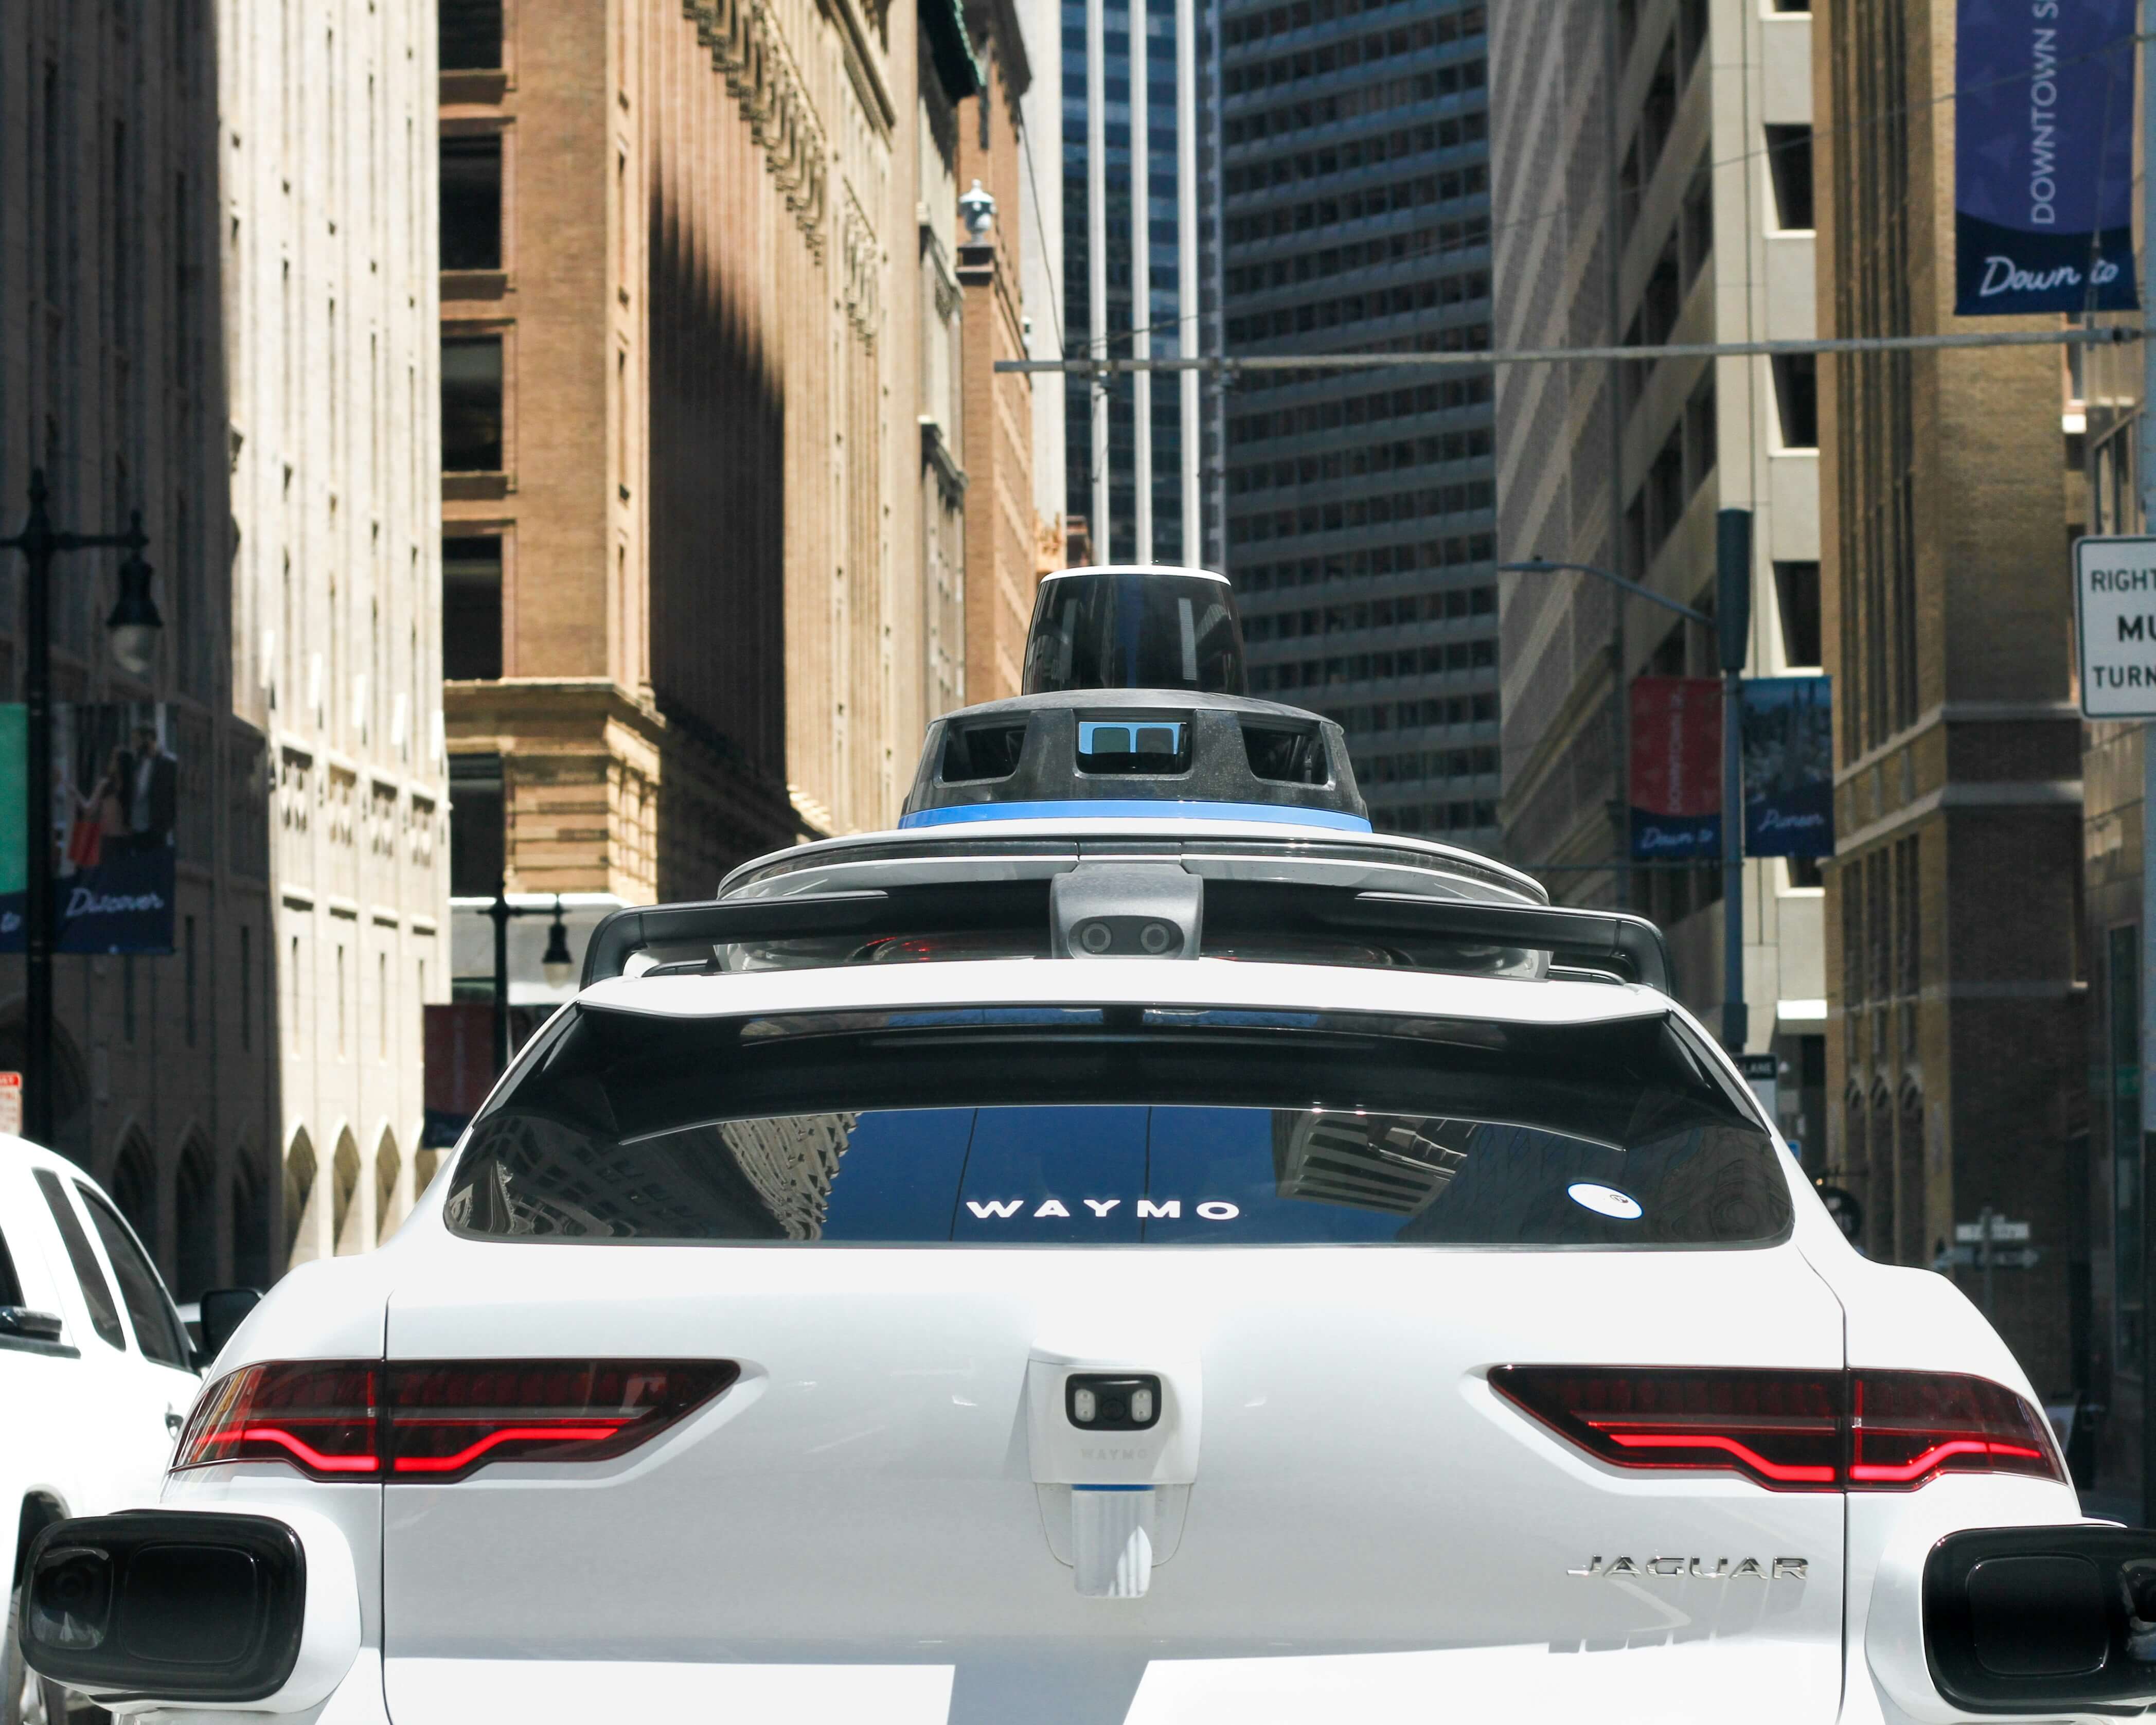
🤖 Who will actually operate Europe’s robotaxi fleets? Autonomous driving may remove the driver, but it doesn’t remove the work behind the car. Robotaxis still need charging, cleaning, maintenance, depots, customer support and someone managing the fleet every day. Early projects in Zagreb, Madrid and London illustrate different stages of deployment and how AV technology providers, fleet operators and booking platforms can work together. Taxi, rental and car-sharing companies already handle many of these tasks. What would it take to turn that experience into an autonomous fleet business?
For a taxi fleet owner, autonomous vehicles may seem to remove the most important part of the current business – the driver. But even without drivers, someone still needs to take care of the cars. They need to be owned or financed, charged, cleaned, inspected and repaired. Someone also needs to manage depots, deal with incidents, help customers and make sure enough cars are available.
The first robotaxi services and tests in Europe are already showing how this could work. The company that develops the autonomous driving technology does not always own or operate the cars. The app where customers book their rides may come from another company too. This could leave an important role for taxi, rental, car-sharing and other fleet companies that already know how to manage vehicles.
A taxi company today manages both cars and drivers. Drivers need to be recruited, scheduled, paid and supported. With a driverless fleet, these tasks would eventually disappear, but most of the work related to the cars would stay.
Autonomous cars still need charging or refuelling, cleaning, tyres, inspections, repairs and insurance. They also need somewhere to park when they are not working. If there is an accident or a technical problem, someone needs to deal with it and get the car back on the road. Customer support is still needed too when there are problems with bookings or payments, or when someone leaves something in the car.
Some of these tasks may even become more important. Robotaxis are expensive, and every hour a car spends charging, being cleaned or waiting for maintenance is an hour when it cannot take passengers. Moove, for example, already provides fleet ownership, depots, charging, maintenance and 24/7 operations for autonomous vehicles.
Drivers also do more than drive: they notice damage, report faults, help passengers and respond when something goes wrong. Without a driver, these responsibilities need clear processes and dedicated support. Existing fleet experience is an advantage, but operators will need to adapt it to vehicles running without someone behind the wheel.
There can be several companies behind one robotaxi ride. One provides autonomous driving technology, another may own the cars, and a local company can take care of the fleet. A platform such as Uber can then connect the cars with passengers. Sometimes one company may do several of these things, but this is not always the case.
Zagreb is one example. Pony.ai provides the autonomous driving system, Verne owns and operates the fleet, and Uber connects it with customers through its app. Autonomous rides became commercially available through Uber in August 2026 with a licensed operator onboard. On 10 September, Pony.ai and Verne also started fully driverless passenger test rides on a 22-kilometre route connecting parts of Zagreb with the airport. These are still limited test rides, not a fully driverless service across the whole city.
A similar model is being tested in Madrid. WeRide, Uber and AVOMO received permission in September 2026 to start testing and mapping under Spain’s ES-AV framework. The first 20 vehicles have an onboard specialist. WeRide provides the autonomous technology, Uber connects the cars with passengers, and AVOMO takes care of fleet operations. Commercial operations are planned for later in 2026, but the current permit is for testing and preparation rather than a general driverless taxi service.
In London, Wayve and Uber launched supervised autonomous passenger rides in September 2026. Customers can be matched with an autonomous vehicle through the Uber app, but there is still a licensed driver in the car.
The plans for the next few years are already much bigger. Pony.ai and Uber announced in August 2026 that they plan to deploy more than 2,000 robotaxis in Europe, starting with Zagreb and later expanding to four more European cities.
Bolt and Lucid announced another partnership in September, with Bolt aiming to deploy at least 25,000 autonomous Lucid vehicles across European cities. This is a future target, not 25,000 cars already operating today.
How these fleets are owned and operated may also be different from one city to another. Local regulations, available vehicles, charging and depot infrastructure and partnerships will all have an effect on how each service is set up.
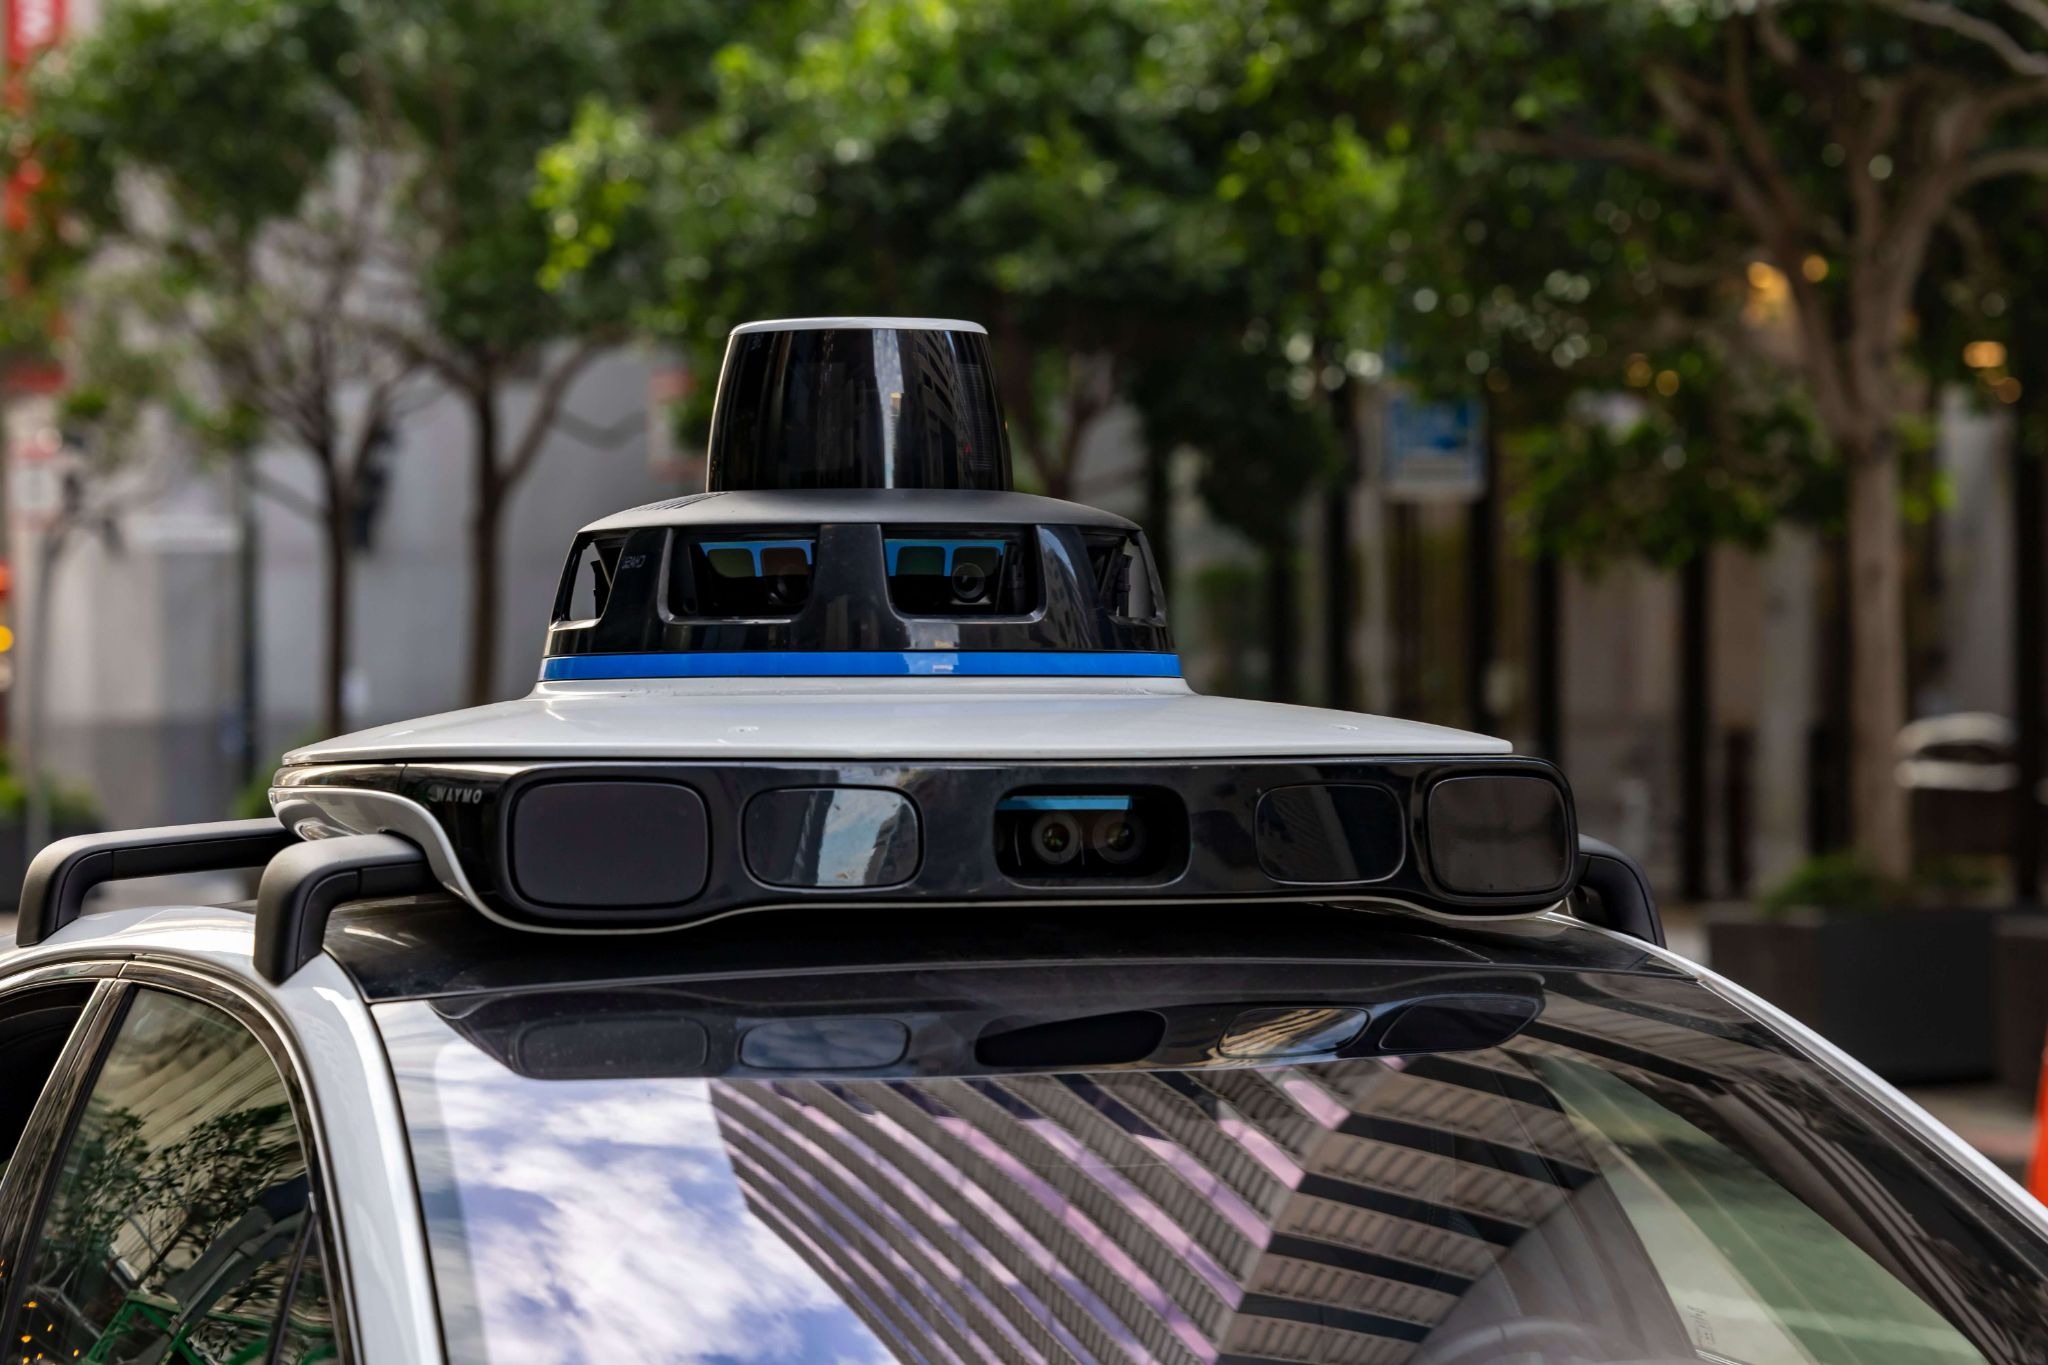
Taxi companies already do many of the things that would still be needed with an autonomous fleet. They maintain cars, deal with insurance and incidents, provide customer support and make sure enough vehicles are available. Some also already have their own depots, charging infrastructure or maintenance partners.
One possible model can already be seen in Zagreb. A local company owns and operates the autonomous fleet, while a larger ride-hailing platform brings customers. In the future, an existing taxi company could potentially have a similar role. Instead of managing cars and drivers, it could manage autonomous cars that receive bookings through a larger platform.
This does not mean platforms such as Uber will always rely on other companies to own the cars. Uber’s 2026 agreement with Rivian includes up to $1.25 billion in milestone-dependent investment and says that Uber or its fleet partners may purchase the autonomous vehicles. Uber is also developing infrastructure for autonomous fleets. Different ownership models are therefore possible.
Autonomous vehicles could also become interesting for rental and car-sharing companies, although this is probably further in the future. These businesses already manage vehicles, maintenance, cleaning, charging, bookings, customer accounts and payments, so much of the practical work is similar.
Autonomous driving could also change how rental and sharing cars are moved. Today, an employee may need to drive a car from one location to another. In the future, the vehicle could potentially do this itself within an area where autonomous driving is approved. It could even become possible for a rental car to drive itself to a customer’s pickup point.
Without drivers, it becomes especially important to understand how much time each vehicle is actually working. Every hour spent charging, being cleaned, waiting for maintenance or simply sitting unused means less time carrying paying passengers.
Some useful KPIs could be available hours per vehicle, paid trips per vehicle each day, revenue per available vehicle/day, empty kilometres, charging and maintenance downtime, cost per trip and incidents that need human help. These are most popular robotaxi industry KPIs of what a company could measure during a pilot.
For example, if cars spend too much time waiting to charge, the charging setup may need to change. A lot of empty kilometres could mean the cars are not in the right places, while too much maintenance downtime could make a vehicle more expensive to operate.
For either model, the business case depends on the partnership terms: who finances the vehicles, who carries the risk when demand is low, and how revenue and operating costs are shared. Operators should assess what remains after vehicle financing, insurance, charging, maintenance and partner fees. Depots, local service teams and reliable fleet availability could make an operator a valuable partner, but profitability still needs to be demonstrated.
One option for taxi fleets would be to work with an autonomous driving company and a larger ride-hailing platform. The local company could own or manage the cars and take care of the fleet, while customers book their rides through the larger platform.
Another option could be possible in cities where large ride-hailing platforms are not present or have limited coverage. A local company could work with an approved AV provider while using its own app, bookings, payments, customer support and fleet management.
In both cases, a company cannot simply buy autonomous cars and start offering rides. The technology needs to be approved, and local rules have to allow the service. These rules will also be different across Europe. Great Britain, for example, introduced its Automated Passenger Services permitting framework in 2026. Services similar to taxis or private hire vehicles need consent from the relevant local authority, while responsibility for the autonomous driving technology and the passenger service are treated separately.
A company does not need to have autonomous cars today to start preparing. A good first step is understanding the current fleet in detail – what each vehicle costs, how many hours it is available, how much time it spends charging or being repaired, and when cars are used the most.
Charging, cleaning, maintenance and depot processes are also worth looking at because all of these will still be needed with autonomous vehicles. A company interested in an AV pilot can then choose a location and use case, look at the local permit process and start talking to autonomous driving technology providers.
The software will also need some preparation. Customers still need to book and pay for rides, while the company needs fleet information, customer support, reporting and connections between its own systems and the AV technology. Starting with a small pilot makes it possible to test all of this before trying to build a larger service.
ATOM Mobility already provides many of the software functions used by taxi, ride-hailing, rental and sharing companies, including customer apps, bookings, payments, fleet management, maintenance tasks, analytics and APIs. Its ride-hailing software includes passenger and driver apps, dispatch, payments, fleet data, analytics and integrations. The ATOM Mobility API can also exchange data about vehicles, bookings, rides, payments, telemetry and maintenance tasks.
ATOM Mobility does not provide autonomous driving technology. This would come from a specialised AV company, and each project would have its own technical requirements and local approvals. For an AV pilot, ATOM Mobility could work with the fleet company and AV provider on the rider experience, integrations, fleet management and the data needed to measure how the pilot is working.
If you operate a taxi, rental or sharing fleet and want to explore an AV pilot, ATOM Mobility can help plan the booking and fleet-management setup, integrations and metrics you would need to test together with an AV technology partner.
Use test credentials to log in - Phone number: +1 123123123, Code: 777777


Driver App demo credentials - Email: test@atom.com, Password: driver