The bike-sharing industry in 2021 and beyond
August 26, 2021
min. read

The bike-sharing industry is on the rise. It is the only mobility industry that statistics indicate didn't experience significant losses during the pandemic. The future is also bright as there are government initiatives around the world to support bike-sharing. However, there are things that newcomers in the business can learn from the previous leaders - success in the industry with high demand is no guarantee that the company will be a success.
A bike is a comfortable means of transportation in regions where motorized vehicles are widely used but create heavy traffic jams and pollute the air. This is a problem in regions like Asia-Pacific, North America, and Europe. And this is where and why bike-sharing has become popular. According to the Statista Mobility Outlook, bike-sharing was the only mobility sector that grew its global revenues during the pandemic by a third in 2020. The single-person set-up and open-air nature of bike riding made it the perfect mode of transportation for the pandemic.

Bike-sharing is a shared transport service in which convectional bikes or electric bikes are made available for shared use to individuals on a short-term basis for a price or free. Development of software, GPS technologies, mobile payments, and IoT devices, as well as reduced locking and tracking system costs for bikes, have recently led to the popularity of a dockless bike-sharing system that allows users to leave the bike anywhere convenient.
According to Mordor Intelligence, the bike-sharing market was valued at USD 3 billion in 2020, and it is anticipated that it will reach USD 4 billion by 2026. The COVID-19 pandemic affected the bike-sharing sector in several countries. The most negative consequences were the daily decline in bike bookings.

Bike demand is majorly driven by developing countries, such as China and India that especially focus on e-bikes. China has always been the largest exporter of e-bikes. According to China’s Ministry of Industry and Information Technology, the country's output of electric bicycles reached 25.48 million during the first 10 months of 2020, a year-on-year increase of 33.4%. During this period, the revenue of major bicycle manufacturing companies reached about USD 22 billion, an increase of 16.8%. According to the China Bicycle Association, from January to September 2020, the volume of bicycle exports was 12% up on the same period last year, rising to USD 2.43 billion.
However, the bike-sharing market growth in Europe is predicted to be the fastest across the globe, as it is anticipated that a large number of service providers will venture into the region in the coming years. In regional countries, bikes are being rapidly made available near major transit hubs, such as railway stations, thereby offering users convenience and ease of travel. In addition, the European Union (EU) also promotes such services, because they are environment-friendly and help to reduce traffic.
Global bike-sharing service market size between 2020 and 2026 in billion U.S. dollars according to Statista:

Currently, major players in the bike-sharing market are:
- Uber Technologies Inc. - provides opportunities to rent a bike in a partnership with Lime. Jump brand bikes are available after Lime acquired the Jump company.
- Lyft Inc. - in November 2018, Lyft acquired Motivate, a bicycle-sharing system and the operator of Capital Bikeshare and Citi Bike. It thus became the largest bike-share service in the United States.
- Hellobike - a transportation service platform based in Shanghai, China. Founded in 2016, the company merged with Youon Bike the following year. In a series of fundraising rounds dating back to 2016, Hellobike has raised over US$1.8 billion from investors.
- DiDi Bike - Didi Chuxing Technology Co. is a Chinese vehicle for hire company headquartered in Beijing with over 550 million users and tens of millions of drivers. The company provides app-based transportation services, including bike-sharing.
The biggest companies in the market are associated with China as are the biggest deals. Looking at the recent biggest deals in bike-sharing, the first worth mentioning involved Didi Chuxing’s bike-sharing arm Qingju. It raised USD 600 million in a Series B equity fundraising round and will be granted an additional USD 400 million in loans.
What was also interesting that at the end of 2020 the mobile application of Mobike, one of China's earliest and largest bike-sharing providers, went offline after its acquisition by Meituan three years before. Mobike was acquired by Meituan for USD 2.7 billion in April 2018. In January 2019, in an internal letter to employees Wang Huiwen, co-founder and Senior Vice-President of Meituan, informed them that Mobike will be renamed Meituan Bike and that the firm would become a unit of the new parent's location-based service department.
The growing interest in e-bikes
One trend that will definitely influence the industry in the near future is the growing interest in e-bike sharing. Pedelecs or pedal electric cycles or EPAC (Electronically Power Assisted Cycles) are becoming increasingly popular. This is a type of electric bicycle where the rider’s pedaling is assisted by a small electric motor. Such vehicles are capable of higher speeds, compared to manually operated bikes. As the demand for higher speeds for short-distance traveling increases, so does the preference for e-bikes. People are ignoring the fact that sharing services on pedal-assisted bikes are cheaper than e-bikes, as the latter offers effortless driving, more convenience, and variable motor power, as well as higher speeds.
One of the most interesting investment deals in 2020 that underlines the interest in e-bikes involved London-based free-to-use shared electric bike firm London-based HumanForest. It announced in September that it had raised £1.8 million. HumanForest offers 20 minutes free per day and a corporate subscription service. It launched in June 2020. In just four months of the company’s operations, 14,000 riders have taken almost 42,000 rides with the number of rides increasing by over 100% month on month!
Later that year, the company raised £1.27m via crowdfunding with the support of over 520 investors, of whom approximately 30% were trial users. The company says that it ran a successful trial during summer 2020 in London with 200 e-bikes. The new funds will be used to expand the fleet to 1,500 e-bikes.
HumanForest’s business model is based on three sources of revenue - users pay 15p per minute after their free daily 10-minute ride is up, while partner companies pay to advertise their brand on the HumanForest digital platform and companies pay to offer their employees further minutes for the HumanForest fleet.
Bike-sharing - more positive than negative aspects
If we analyze positive, as well as negative aspects that could influence the future of bike-sharing, the positive aspects far exceed the negative ones. The only negative aspects are high initial investment costs, as well as the rise in bike vandalism and theft. Positive aspects that could stimulate the bike-sharing business in the future are growing venture capital investments, an increase in the inclusion of e-bikes in the sharing fleet, as well as technological advances in bike-sharing systems.
There is also increased interest from governments in different initiatives for the development of bike-sharing infrastructure. Furthermore, governments are offering subsidies to service providers for developing stations and expanding their reach to a large number of commuters. For instance, in 2018, Chinese Municipal governments subsidized the Public Bike Sharing Program development to encourage non-motorized transport and offer convenient, flexible, and low-cost mobility options. Meanwhile, in Europe, the new public bike-sharing system was launched in the Italian Municipality of Trieste in February 2020. The system, known as BiTS, is being implemented as part of the city's Integrated Sustainable Urban Development Plan at a cost of EUR 390,000, with the aim of developing sustainable mobility by promoting walking and cycling to reduce urban pollution.
Despite the fact that interest in bike-sharing is rising and will continue to do so, it is equally important to learn and not forget the mistakes of pioneers of the industry. For example, the company Ofo was founded in 2014 as a university project, but soon afterward raised $866 million from investors led by Chinese e-commerce giant Alibaba. Ofo was a station-free bike-sharing platform operated via an online mobile application. In total, over the course of nine investment rounds, the company has raised USD 2.2 billion but has still consistently experienced cash flow problems that were driven largely by intense competition in a market that has yet to be proven to be commercially viable according to analysts interviewed by Forbes.
Fees dropped to 1 yuan ($0.14) for each hour of use and sometimes were even free. Despite this fact, Ofo still managed to reach a valuation of $2 billion in a 2017 funding round and around $3 billion at its highest point, and at one time the company deployed more than 10 million bikes globally and attracted as many as 200 million users. “The company’s cash-burning operations and high valuation have combined to deter potential investors, and when capital became scarce, the startup could no longer cover its once sprawling operations,” wrote Forbes.
In 2018, Ofo announced a massive reduction in operations, and by 2020 it faced a large amount of unpayable debt as a result of which the company was no longer operating bike rentals. “Explanations of what exactly went wrong are still evolving, but it seems likely that the mind-boggling amounts of cash pumped into what wasn't essentially a "bike-sharing" model, but rather a rental business pepped up by a smartphone app, had something to do with it. Yes, the company bought bikes and placed them in the streets without docks for anybody to use, and that was somewhat new. And yes, a smartphone app served as the key. But the company owned the bikes, just like any old-fashioned rental shop, and incurred huge maintenance costs,” explained analysts from Roland Berger Strategy Consultants, who were quoted in its magazine “Own the future”.
So it doesn't matter how big the demand for the service is, you should always apply simple business principles to your business.
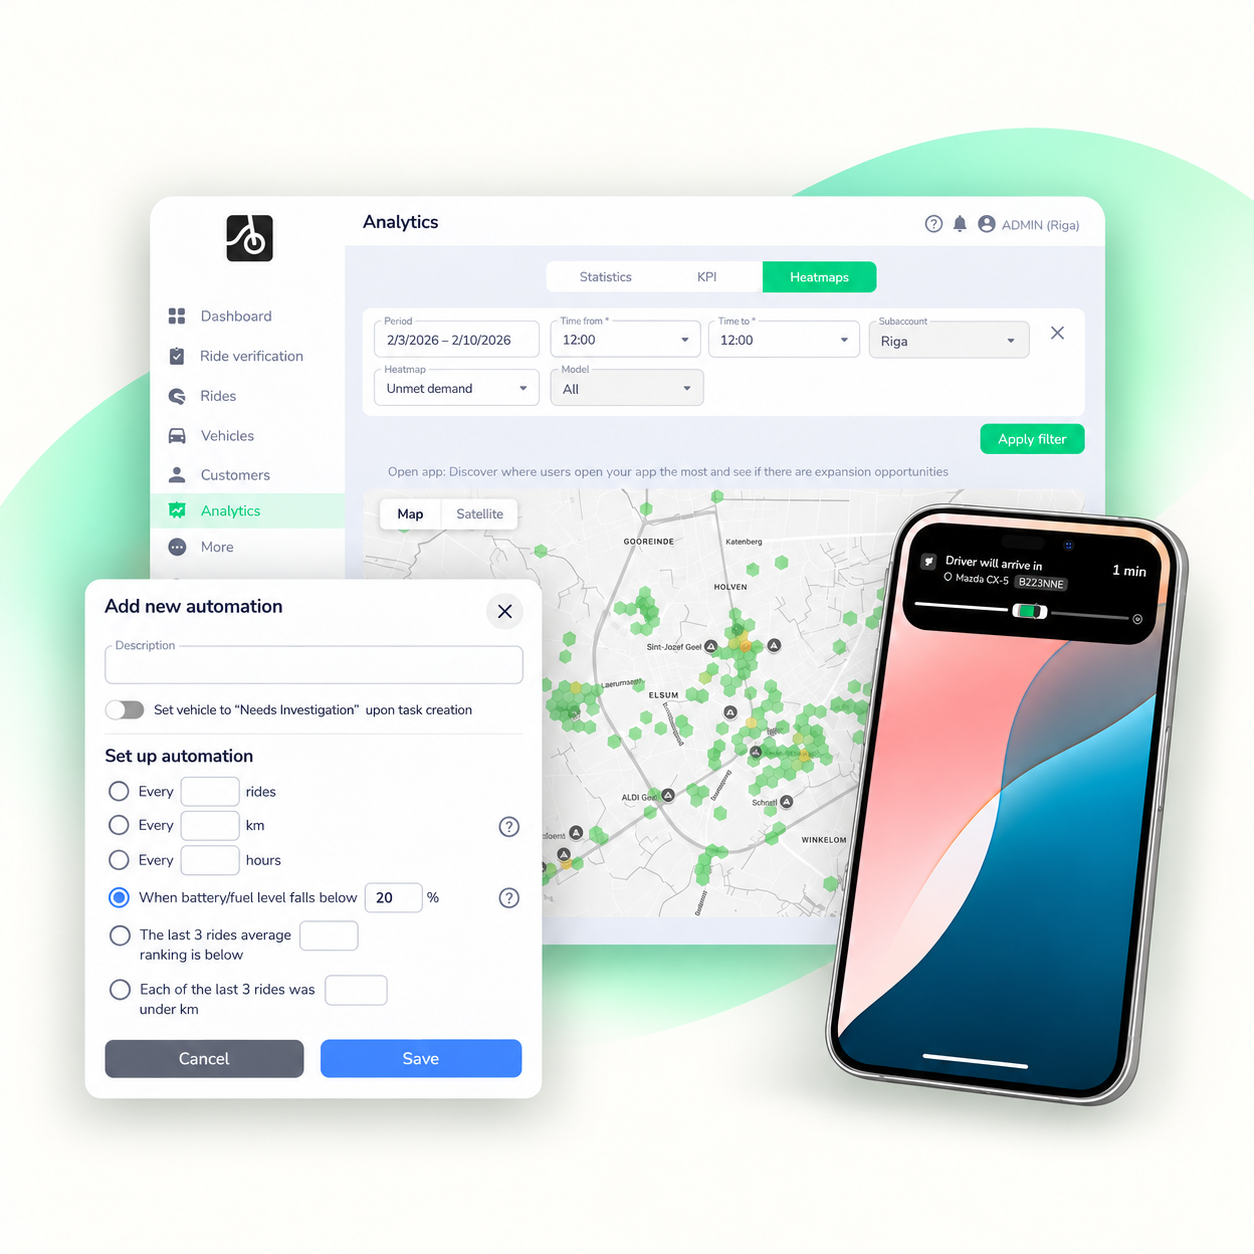
🚀 ATOM Mobility ships 7-15 new features every month, alongside smaller improvements and fixes. Explore five recent highlights: unmet demand heatmaps, automated fleet tasks, field-team performance tracking, new subscription types, and lock-screen ride updates - helping operators run more efficient fleets and improve the rider experience.
Knowing where customers need vehicles, keeping field teams productive, and giving riders reasons to return are everyday priorities for mobility operators. Every month, ATOM Mobility ships 7-15 new features, alongside smaller improvements and fixes. Here are five highlights from our recent releases - and how they can help operators improve fleet performance and the customer experience.
A customer opens your app, finds no vehicle nearby, and leaves. Your ride history alone won’t show you that missed opportunity.
The Unmet Demand heatmap highlights areas where users open the app but cannot find an available scooter, bike, or car within 1000 metres radius. Beyond colour-coded hexagons, on zoomed in view it shows the number of unique users who searched for a vehicle in each area without finding one nearby.
Use these insights to identify gaps in fleet coverage, prioritise rebalancing, and assess potential parking locations. Alongside seeing where rides happen, you can now understand where potential demand goes unmet.

Keeping a fleet ready for customers means staying on top of maintenance, charging, refuelling, and service quality. As your fleet grows into hundreds of vehicles, manually tracking when each vehicle needs attention becomes increasingly time-consuming.
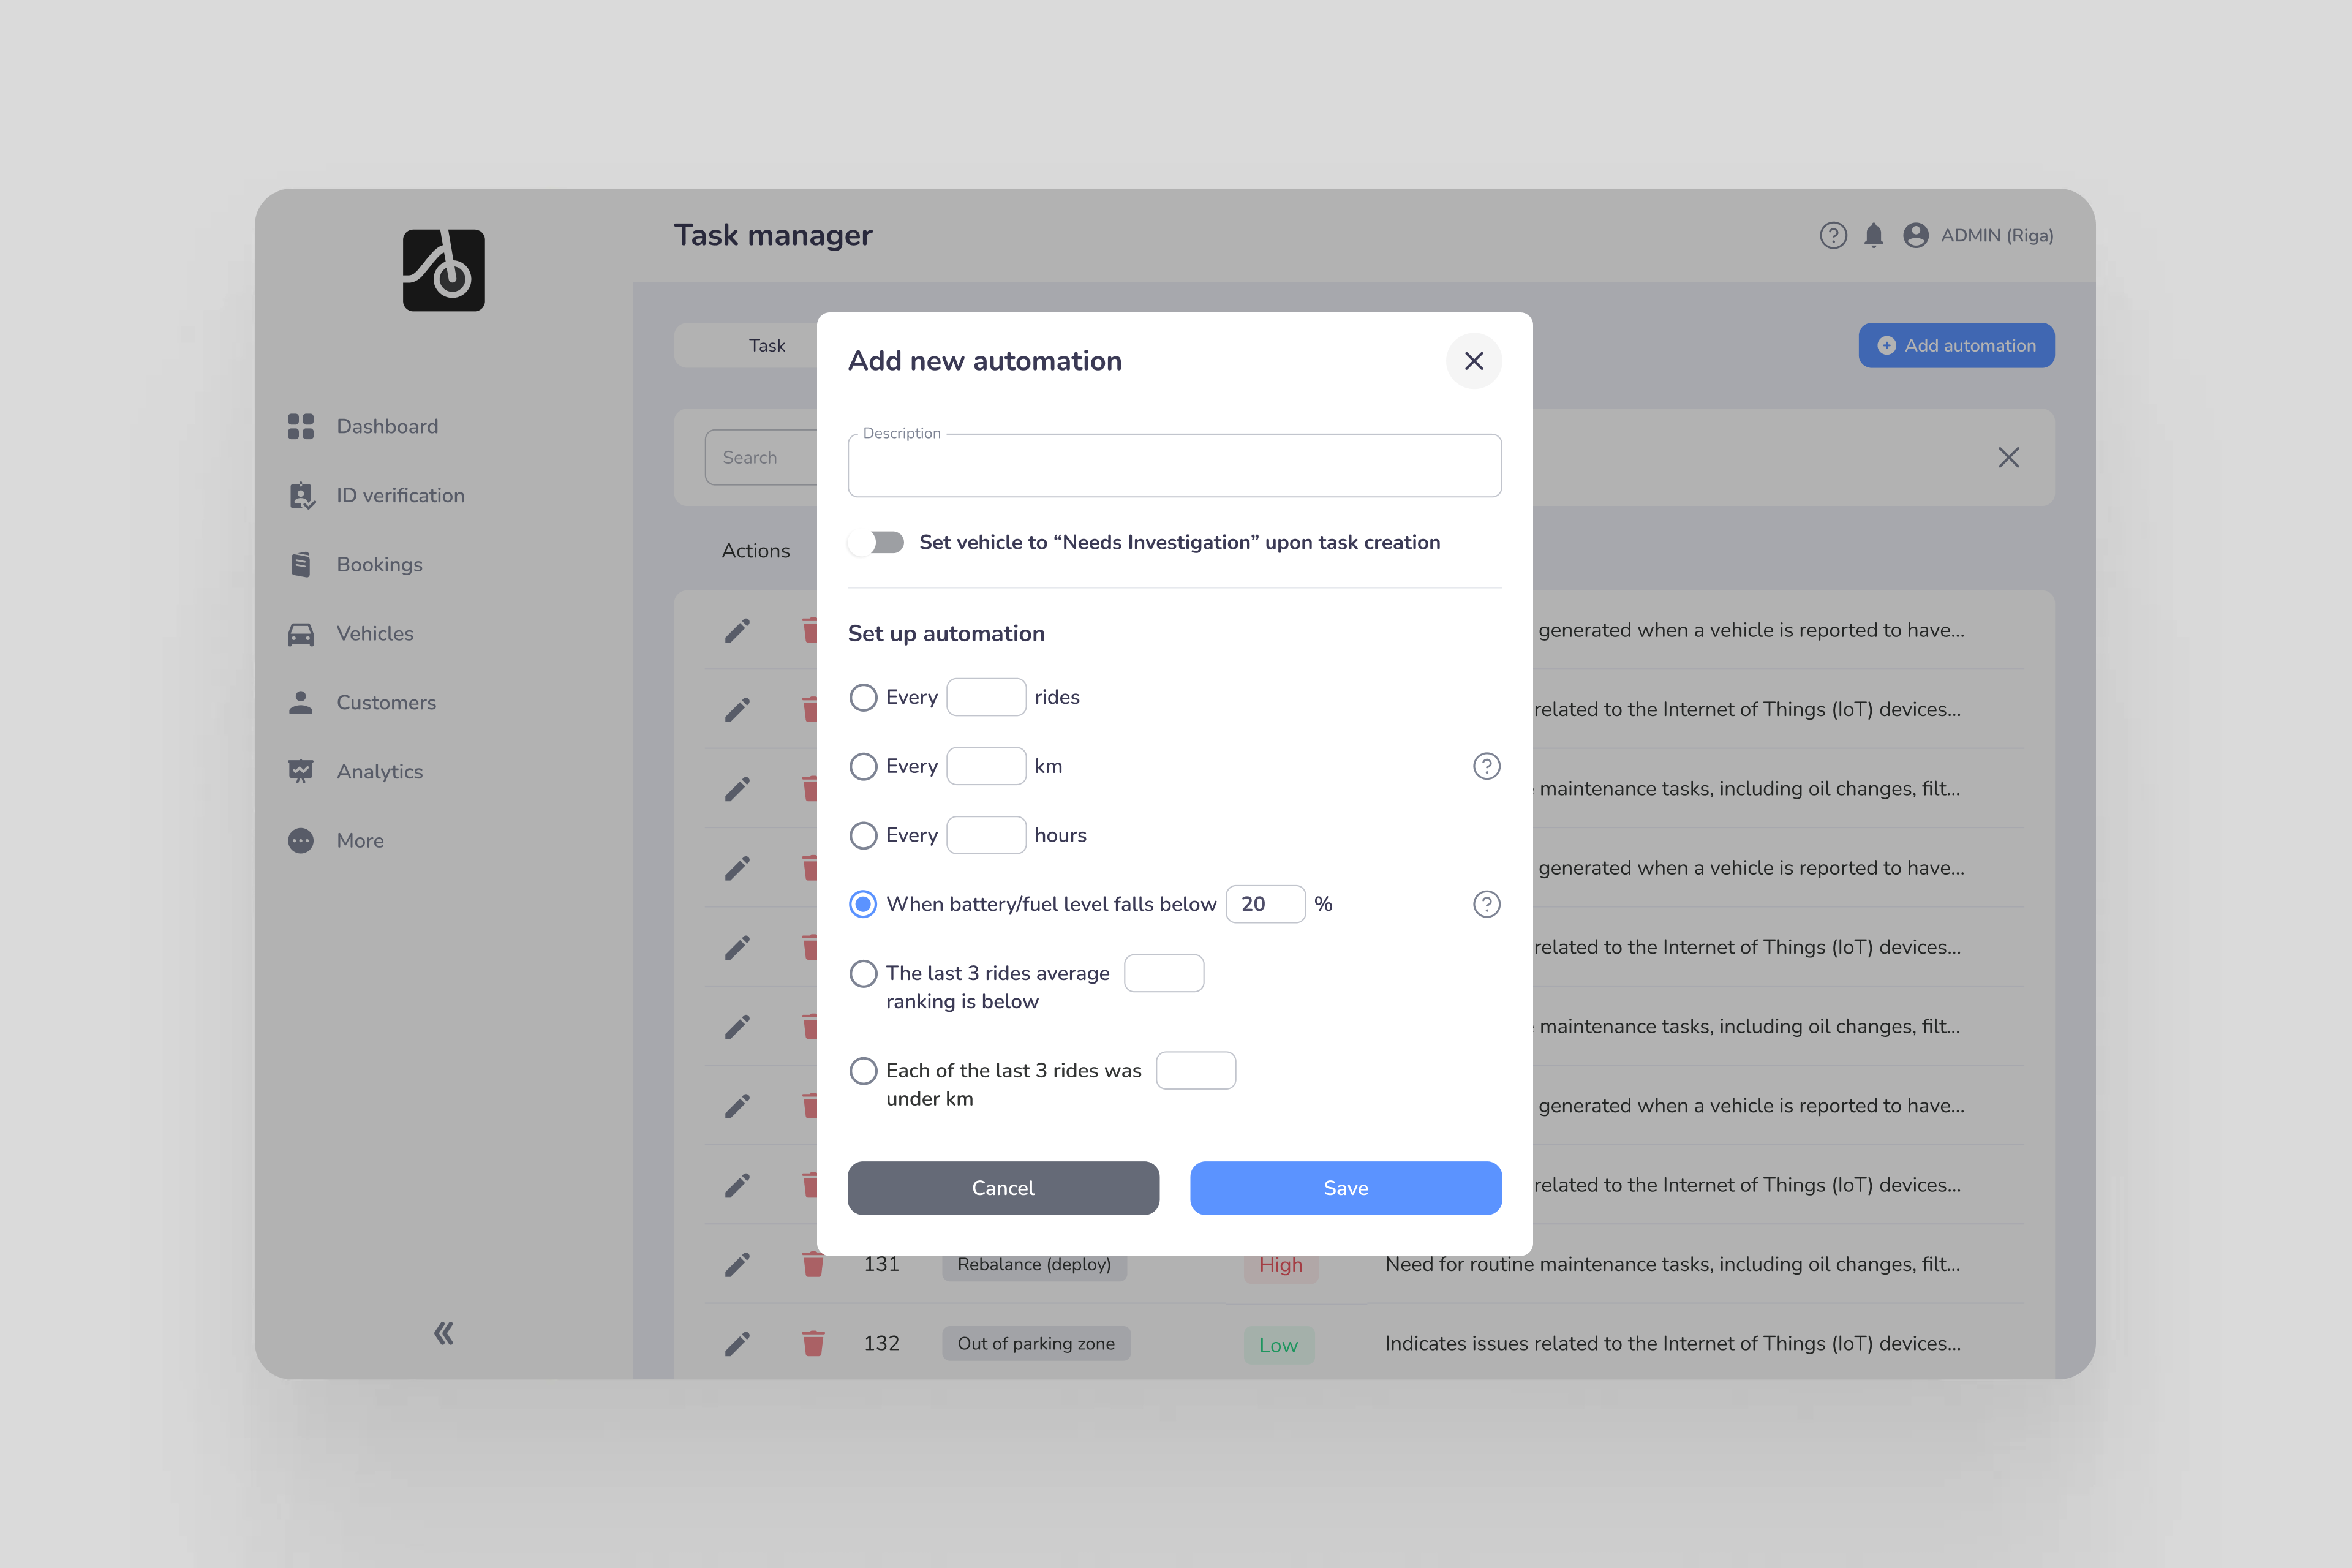
Task Manager automations turn vehicle usage, condition, and ride feedback into actionable tasks. Operators can configure tasks to be created:
These rules can support routine maintenance, trigger charging or refuelling tasks, and flag vehicles for inspection after low ratings or unusually short rides. For rebalancing tasks, if a customer uses the vehicle before collection, the task is automatically removed. This reduces manual monitoring and helps your team respond to vehicles that need attention.
How long do tasks take? Where does your team spend its time? Which operational bottlenecks need attention?
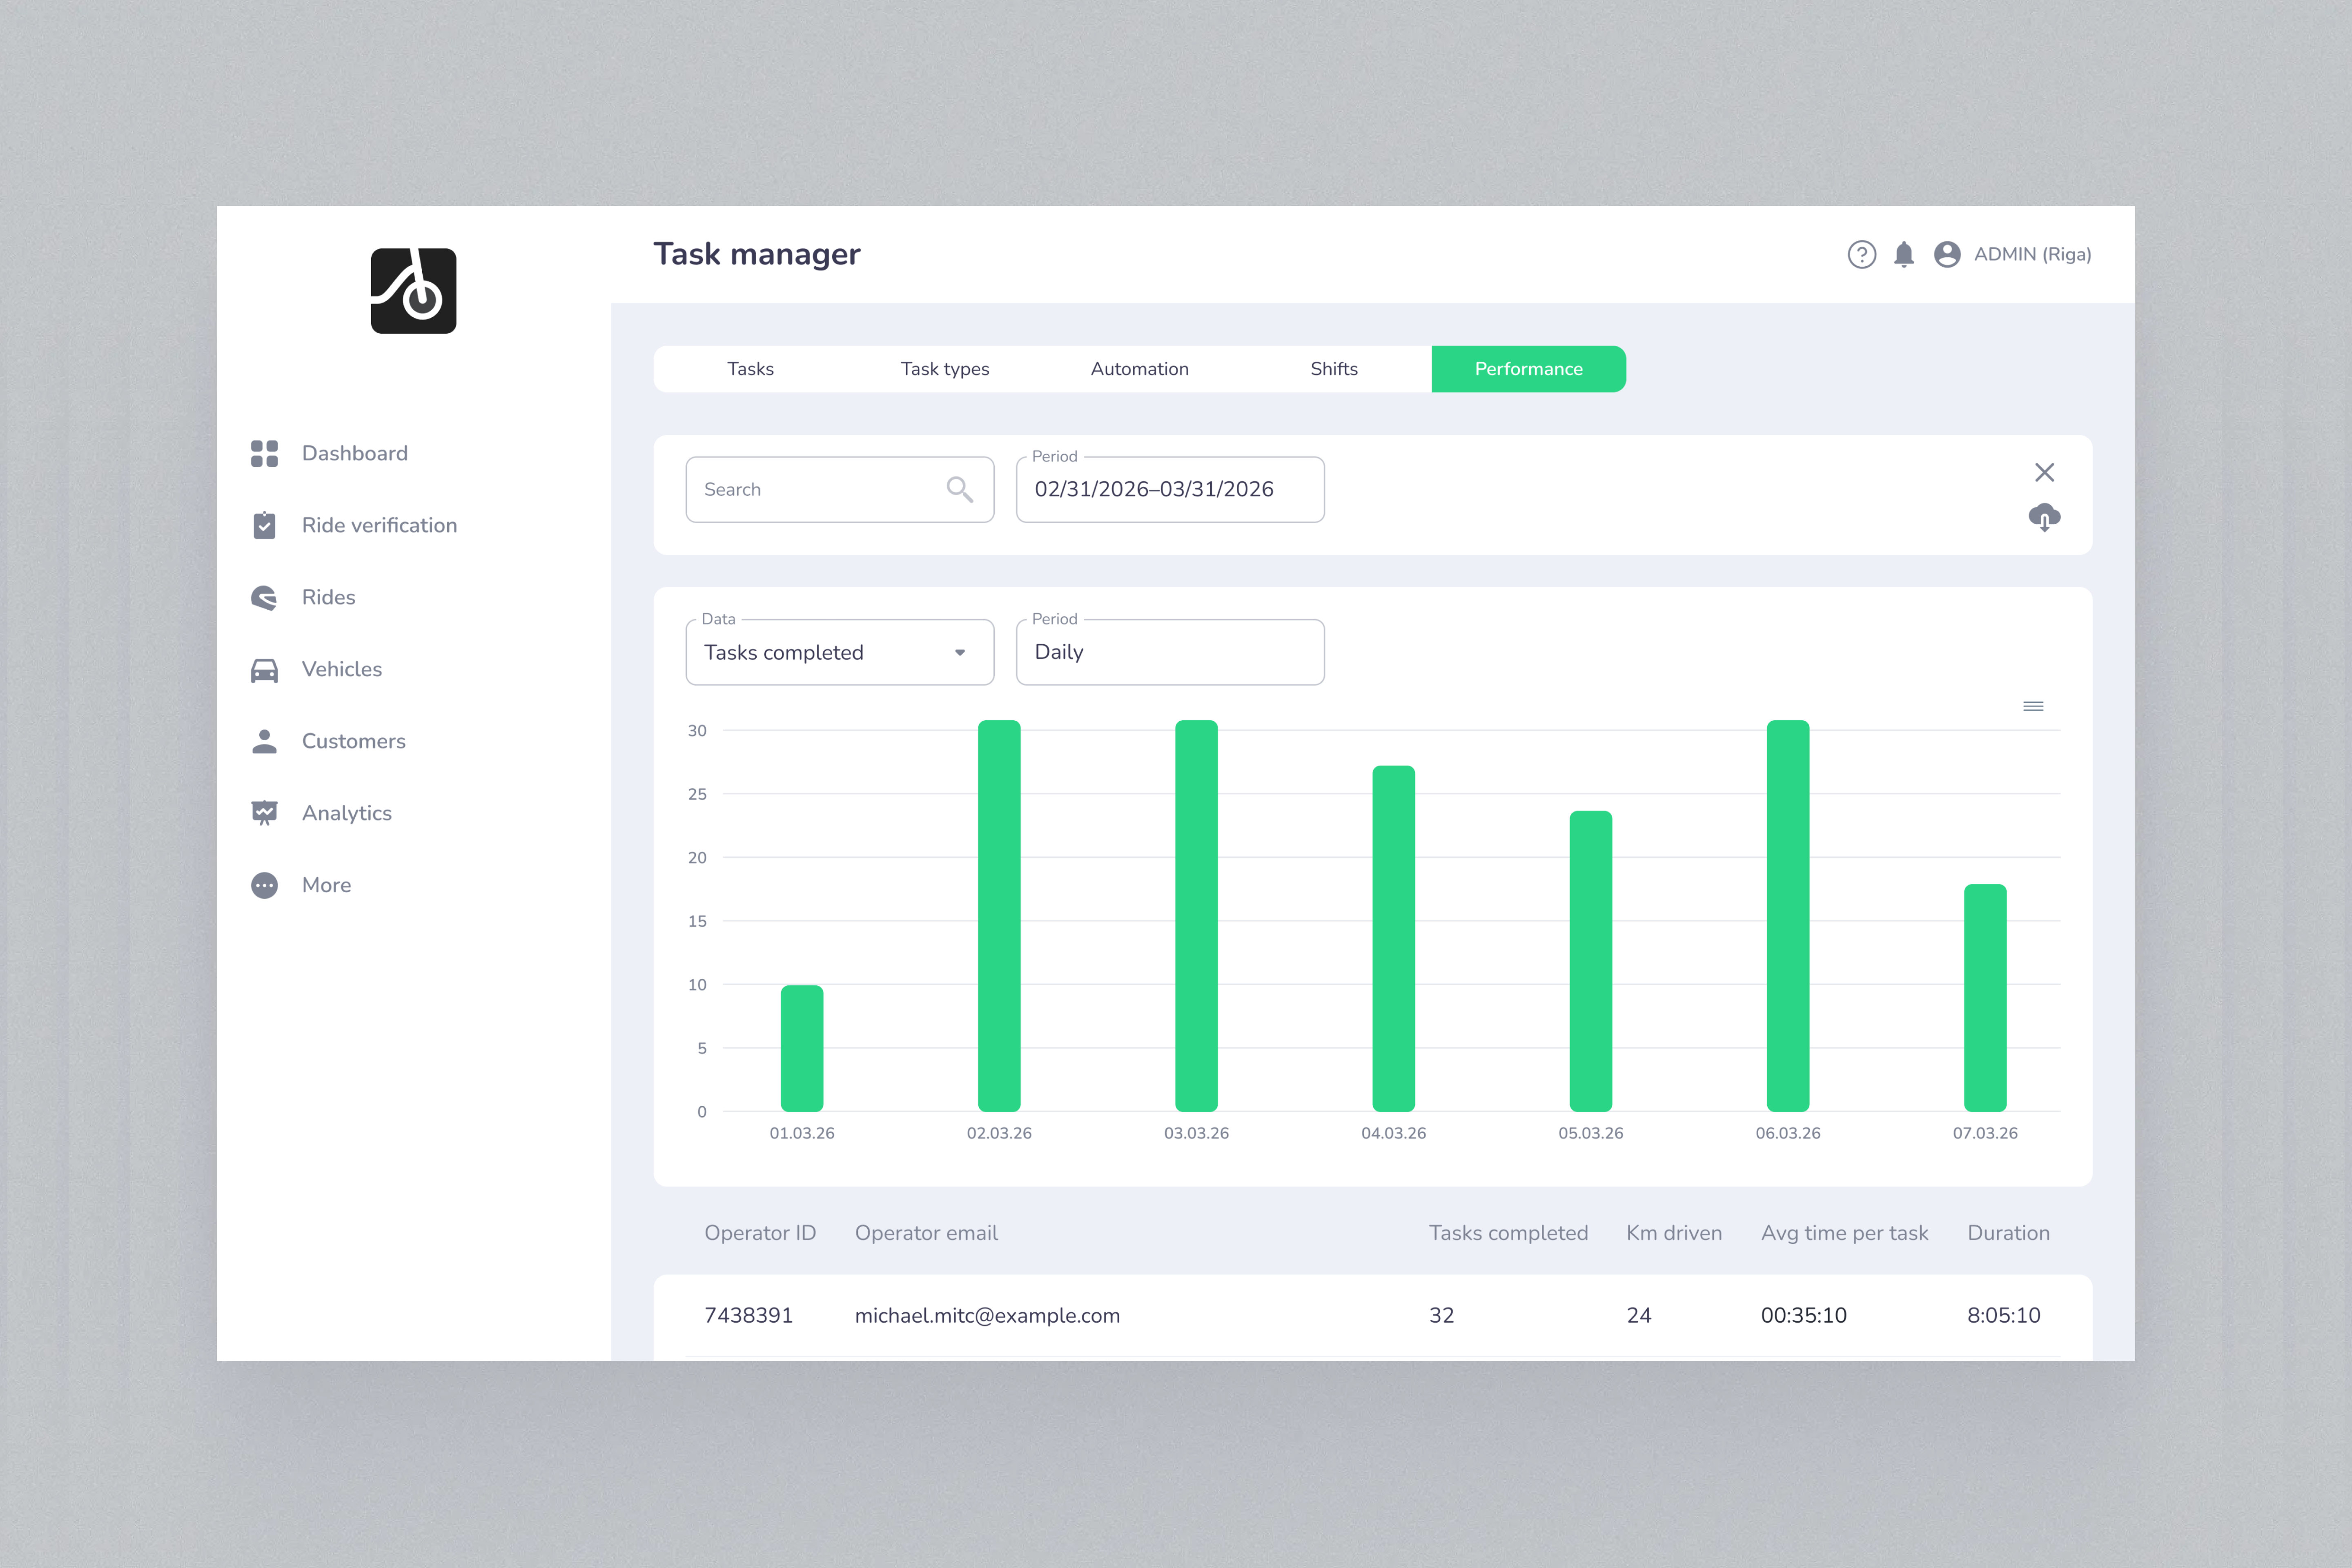
New Shifts and Operator Performance views give vehicle sharing and digital rental operators visibility into shift status and duration, distance driven, completed tasks, and average time per task.
Managers can use these insights to investigate delays, improve routes, and identify training needs. For example, longer task completion times could prompt a closer look at travel distances, workload, or the processes used at each location. Comparing results alongside task types and working conditions helps turn performance data into practical operational improvements.
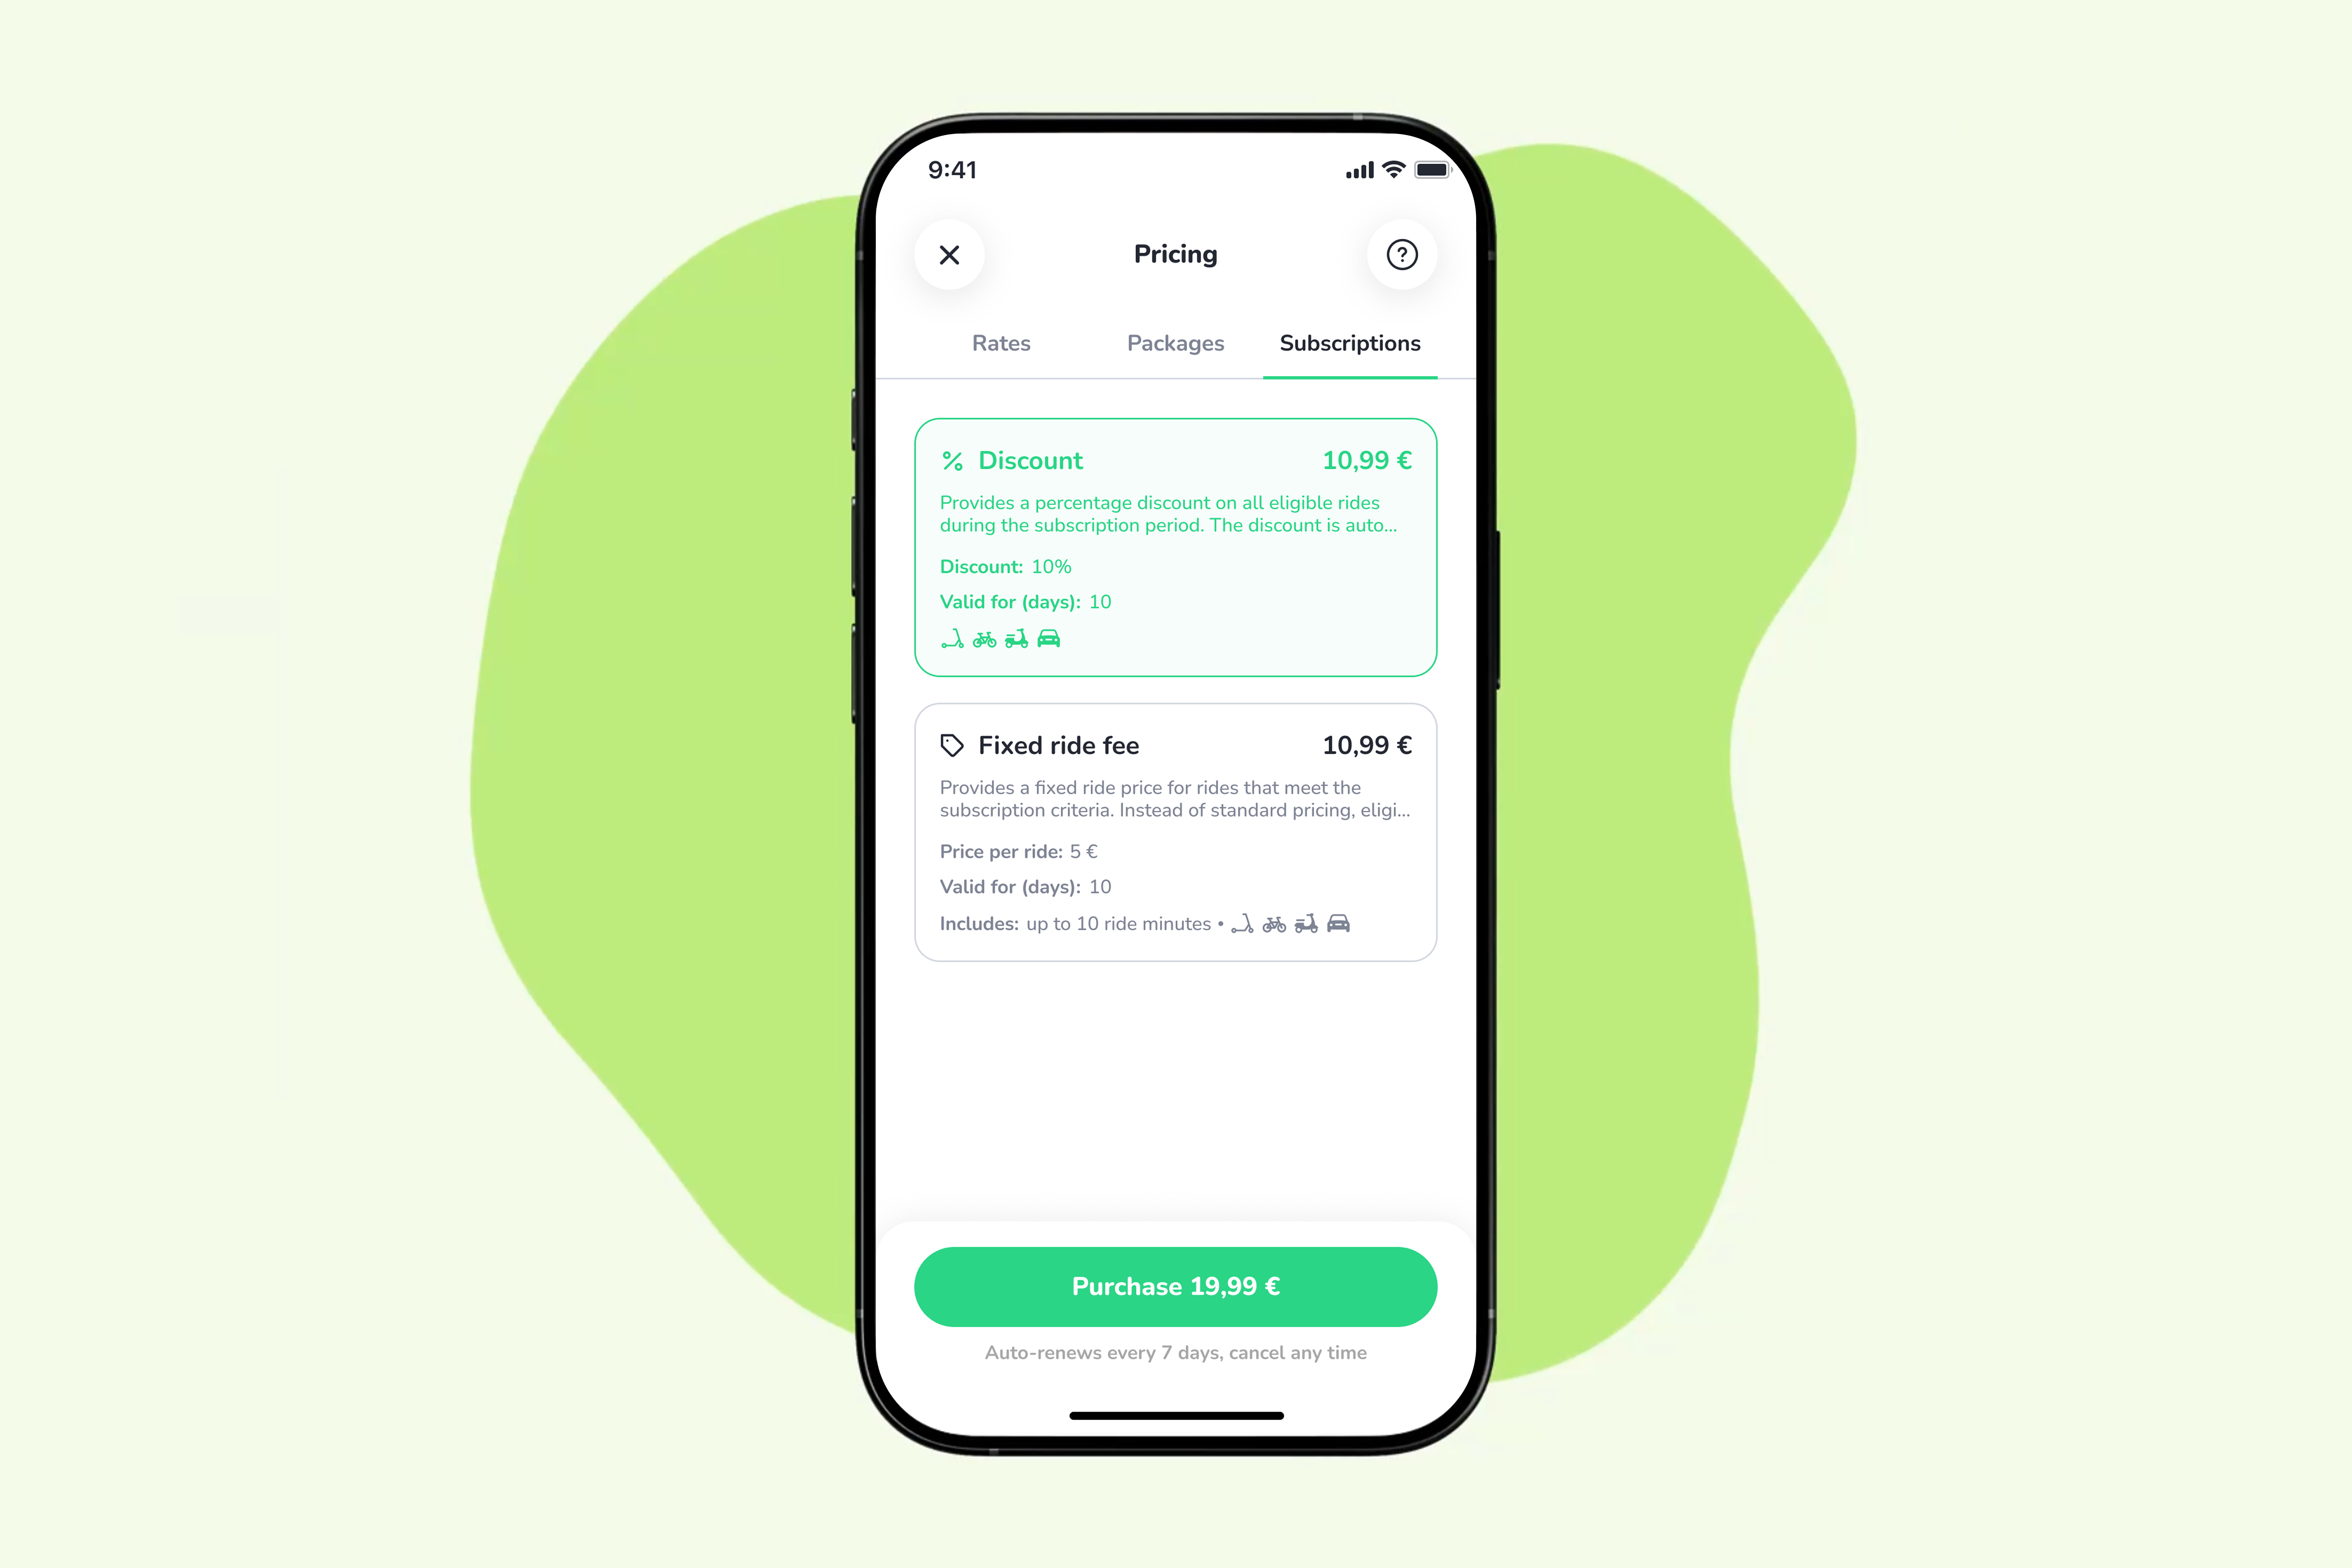
Different customers have different riding habits. Your subscriptions should reflect that.
ATOM Mobility now supports two additional subscription types:
These options let operators design offers around frequent riders and short-distance commuters. For example, you could offer subscribers a percentage discount on eligible rides or a predictable flat fee for qualifying short trips. Operators gain more flexibility to test offers that encourage repeat usage while fitting their pricing strategy.
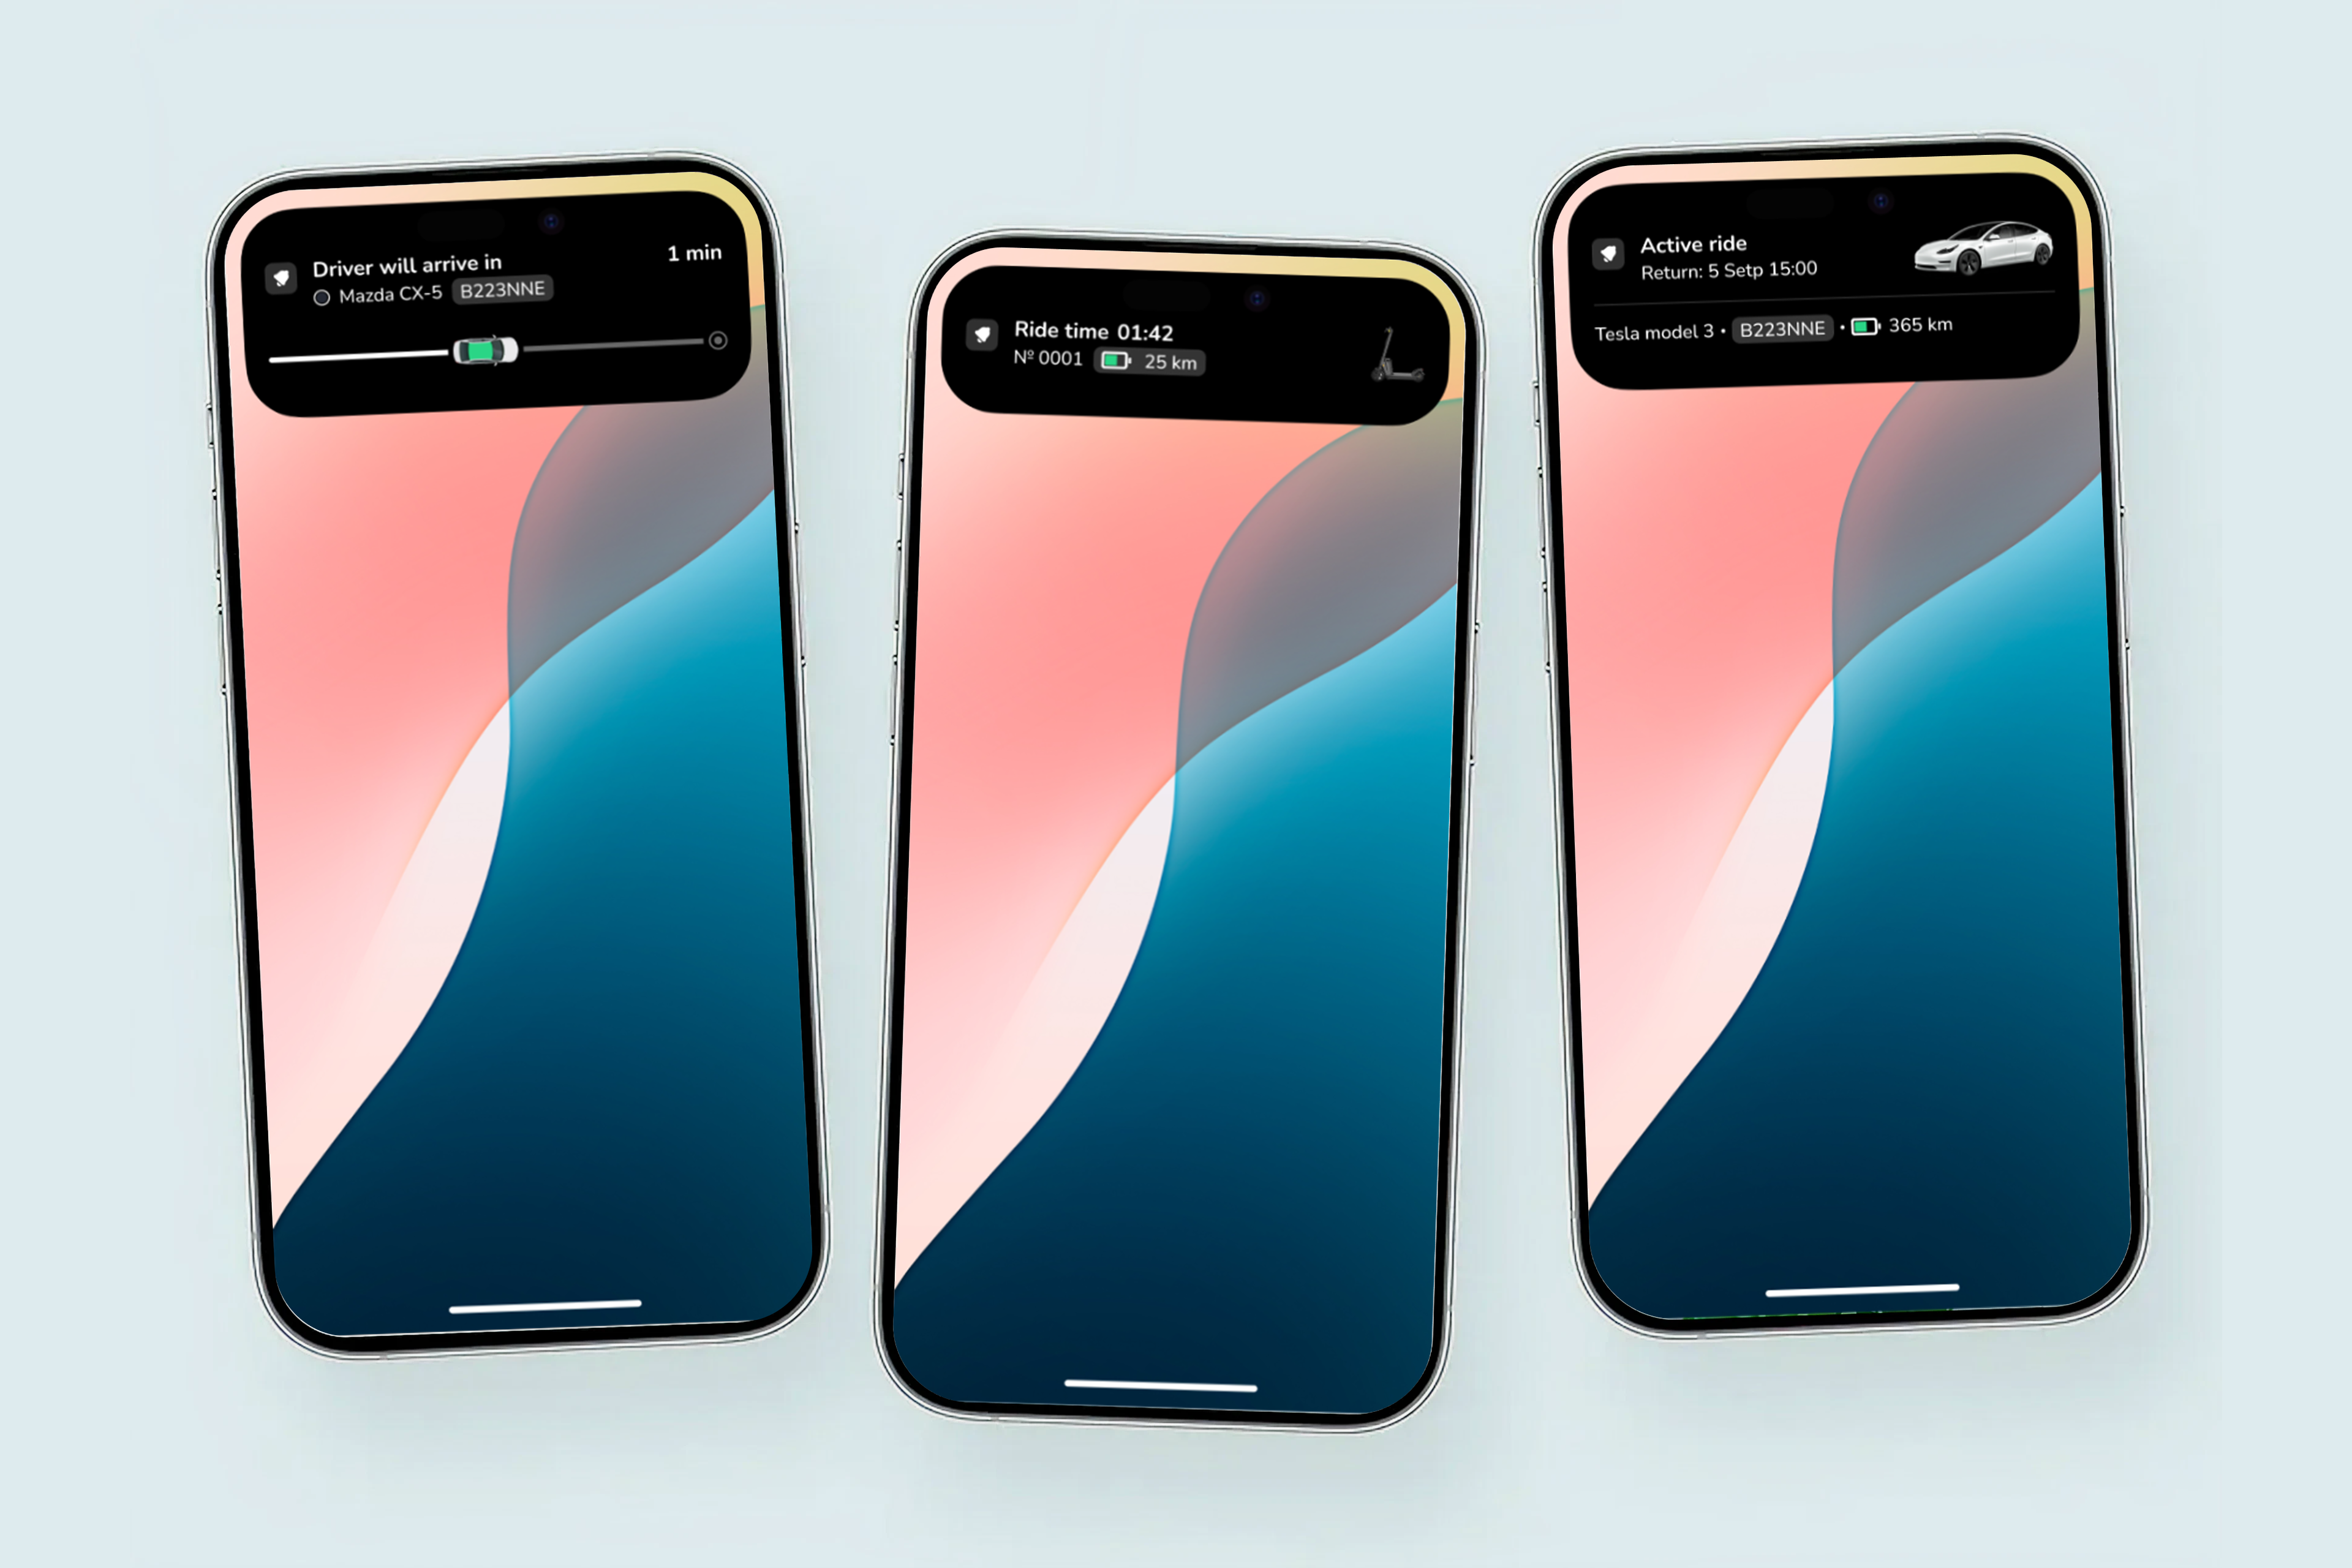
Checking an active trip should be simple.
Live Activity lets customers view key ride information directly on their phone lock screen without repeatedly opening the app. Depending on the service, this can help them follow an active ride or a driver’s arrival.
Making this information readily accessible gives customers a more convenient way to stay informed throughout their journey.
These five releases are part of ATOM Mobility’s ongoing product development, helping operators identify unmet demand, automate routine coordination, understand field-team performance, and improve the customer experience.
Exploring software for your mobility business? Book a demo to see how ATOM Mobility can support your fleet, team, and customers.
Explore more product updates at https://www.atommobility.com/atomupdates
🤖 Who will actually operate Europe’s robotaxi fleets? Autonomous driving may remove the driver, but it doesn’t remove the work behind the car. Robotaxis still need charging, cleaning, maintenance, depots, customer support and someone managing the fleet every day. Early projects in Zagreb, Madrid and London illustrate different stages of deployment and how AV technology providers, fleet operators and booking platforms can work together. Taxi, rental and car-sharing companies already handle many of these tasks. What would it take to turn that experience into an autonomous fleet business?
For a taxi fleet owner, autonomous vehicles may seem to remove the most important part of the current business – the driver. But even without drivers, someone still needs to take care of the cars. They need to be owned or financed, charged, cleaned, inspected and repaired. Someone also needs to manage depots, deal with incidents, help customers and make sure enough cars are available.
The first robotaxi services and tests in Europe are already showing how this could work. The company that develops the autonomous driving technology does not always own or operate the cars. The app where customers book their rides may come from another company too. This could leave an important role for taxi, rental, car-sharing and other fleet companies that already know how to manage vehicles.
A taxi company today manages both cars and drivers. Drivers need to be recruited, scheduled, paid and supported. With a driverless fleet, these tasks would eventually disappear, but most of the work related to the cars would stay.
Autonomous cars still need charging or refuelling, cleaning, tyres, inspections, repairs and insurance. They also need somewhere to park when they are not working. If there is an accident or a technical problem, someone needs to deal with it and get the car back on the road. Customer support is still needed too when there are problems with bookings or payments, or when someone leaves something in the car.
Some of these tasks may even become more important. Robotaxis are expensive, and every hour a car spends charging, being cleaned or waiting for maintenance is an hour when it cannot take passengers. Moove, for example, already provides fleet ownership, depots, charging, maintenance and 24/7 operations for autonomous vehicles.
Drivers also do more than drive: they notice damage, report faults, help passengers and respond when something goes wrong. Without a driver, these responsibilities need clear processes and dedicated support. Existing fleet experience is an advantage, but operators will need to adapt it to vehicles running without someone behind the wheel.
There can be several companies behind one robotaxi ride. One provides autonomous driving technology, another may own the cars, and a local company can take care of the fleet. A platform such as Uber can then connect the cars with passengers. Sometimes one company may do several of these things, but this is not always the case.
Zagreb is one example. Pony.ai provides the autonomous driving system, Verne owns and operates the fleet, and Uber connects it with customers through its app. Autonomous rides became commercially available through Uber in August 2026 with a licensed operator onboard. On 10 September, Pony.ai and Verne also started fully driverless passenger test rides on a 22-kilometre route connecting parts of Zagreb with the airport. These are still limited test rides, not a fully driverless service across the whole city.
A similar model is being tested in Madrid. WeRide, Uber and AVOMO received permission in September 2026 to start testing and mapping under Spain’s ES-AV framework. The first 20 vehicles have an onboard specialist. WeRide provides the autonomous technology, Uber connects the cars with passengers, and AVOMO takes care of fleet operations. Commercial operations are planned for later in 2026, but the current permit is for testing and preparation rather than a general driverless taxi service.
In London, Wayve and Uber launched supervised autonomous passenger rides in September 2026. Customers can be matched with an autonomous vehicle through the Uber app, but there is still a licensed driver in the car.
The plans for the next few years are already much bigger. Pony.ai and Uber announced in August 2026 that they plan to deploy more than 2,000 robotaxis in Europe, starting with Zagreb and later expanding to four more European cities.
Bolt and Lucid announced another partnership in September, with Bolt aiming to deploy at least 25,000 autonomous Lucid vehicles across European cities. This is a future target, not 25,000 cars already operating today.
How these fleets are owned and operated may also be different from one city to another. Local regulations, available vehicles, charging and depot infrastructure and partnerships will all have an effect on how each service is set up.
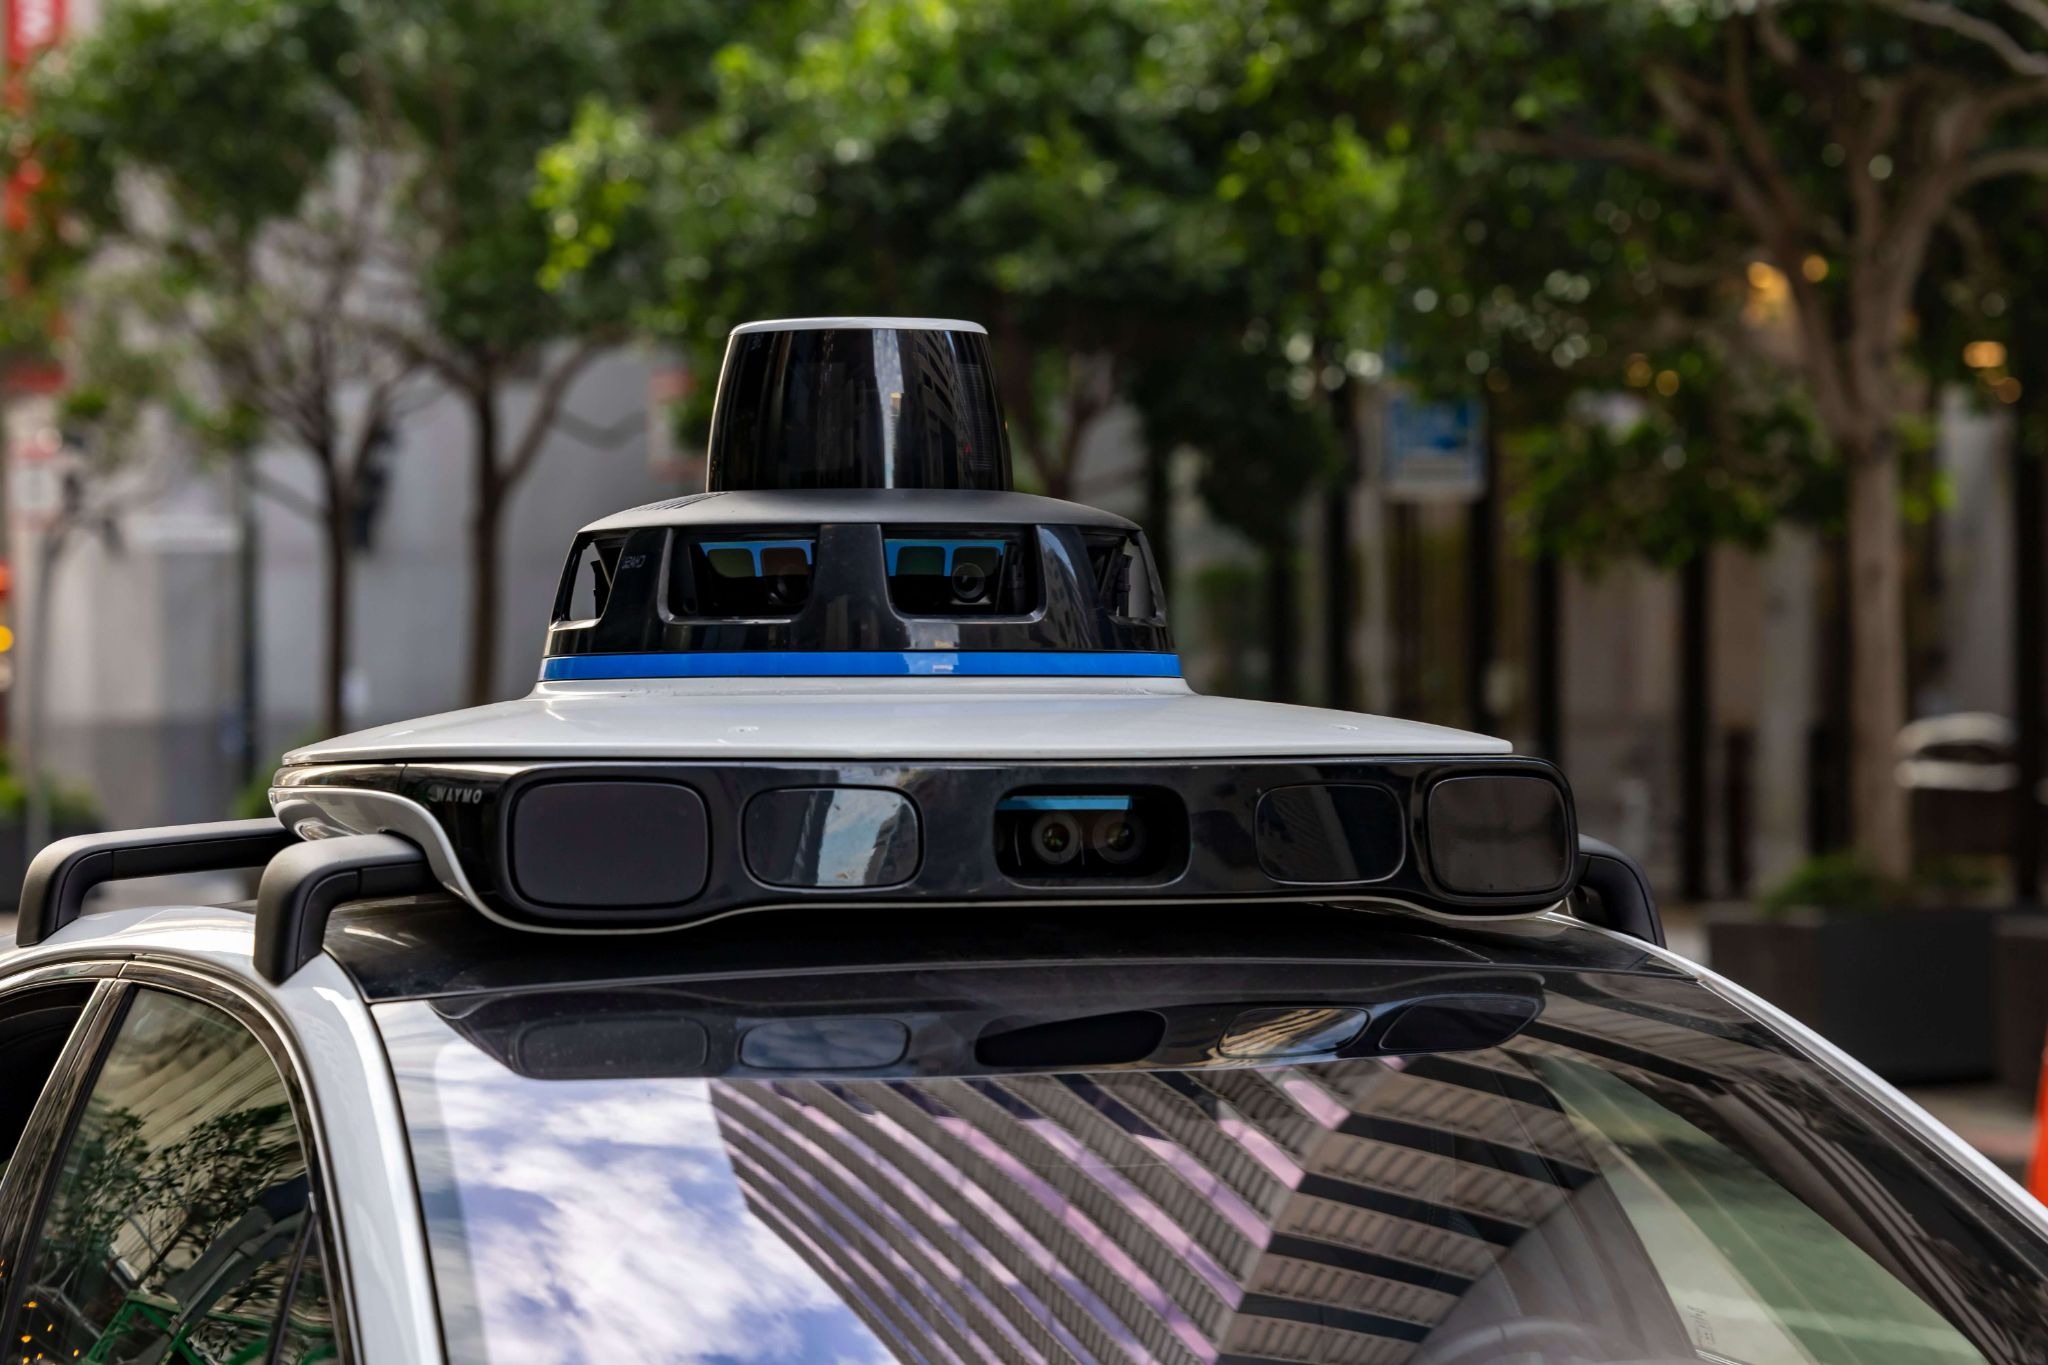
Taxi companies already do many of the things that would still be needed with an autonomous fleet. They maintain cars, deal with insurance and incidents, provide customer support and make sure enough vehicles are available. Some also already have their own depots, charging infrastructure or maintenance partners.
One possible model can already be seen in Zagreb. A local company owns and operates the autonomous fleet, while a larger ride-hailing platform brings customers. In the future, an existing taxi company could potentially have a similar role. Instead of managing cars and drivers, it could manage autonomous cars that receive bookings through a larger platform.
This does not mean platforms such as Uber will always rely on other companies to own the cars. Uber’s 2026 agreement with Rivian includes up to $1.25 billion in milestone-dependent investment and says that Uber or its fleet partners may purchase the autonomous vehicles. Uber is also developing infrastructure for autonomous fleets. Different ownership models are therefore possible.
Autonomous vehicles could also become interesting for rental and car-sharing companies, although this is probably further in the future. These businesses already manage vehicles, maintenance, cleaning, charging, bookings, customer accounts and payments, so much of the practical work is similar.
Autonomous driving could also change how rental and sharing cars are moved. Today, an employee may need to drive a car from one location to another. In the future, the vehicle could potentially do this itself within an area where autonomous driving is approved. It could even become possible for a rental car to drive itself to a customer’s pickup point.
Without drivers, it becomes especially important to understand how much time each vehicle is actually working. Every hour spent charging, being cleaned, waiting for maintenance or simply sitting unused means less time carrying paying passengers.
Some useful KPIs could be available hours per vehicle, paid trips per vehicle each day, revenue per available vehicle/day, empty kilometres, charging and maintenance downtime, cost per trip and incidents that need human help. These are most popular robotaxi industry KPIs of what a company could measure during a pilot.
For example, if cars spend too much time waiting to charge, the charging setup may need to change. A lot of empty kilometres could mean the cars are not in the right places, while too much maintenance downtime could make a vehicle more expensive to operate.
For either model, the business case depends on the partnership terms: who finances the vehicles, who carries the risk when demand is low, and how revenue and operating costs are shared. Operators should assess what remains after vehicle financing, insurance, charging, maintenance and partner fees. Depots, local service teams and reliable fleet availability could make an operator a valuable partner, but profitability still needs to be demonstrated.
One option for taxi fleets would be to work with an autonomous driving company and a larger ride-hailing platform. The local company could own or manage the cars and take care of the fleet, while customers book their rides through the larger platform.
Another option could be possible in cities where large ride-hailing platforms are not present or have limited coverage. A local company could work with an approved AV provider while using its own app, bookings, payments, customer support and fleet management.
In both cases, a company cannot simply buy autonomous cars and start offering rides. The technology needs to be approved, and local rules have to allow the service. These rules will also be different across Europe. Great Britain, for example, introduced its Automated Passenger Services permitting framework in 2026. Services similar to taxis or private hire vehicles need consent from the relevant local authority, while responsibility for the autonomous driving technology and the passenger service are treated separately.
A company does not need to have autonomous cars today to start preparing. A good first step is understanding the current fleet in detail – what each vehicle costs, how many hours it is available, how much time it spends charging or being repaired, and when cars are used the most.
Charging, cleaning, maintenance and depot processes are also worth looking at because all of these will still be needed with autonomous vehicles. A company interested in an AV pilot can then choose a location and use case, look at the local permit process and start talking to autonomous driving technology providers.
The software will also need some preparation. Customers still need to book and pay for rides, while the company needs fleet information, customer support, reporting and connections between its own systems and the AV technology. Starting with a small pilot makes it possible to test all of this before trying to build a larger service.
ATOM Mobility already provides many of the software functions used by taxi, ride-hailing, rental and sharing companies, including customer apps, bookings, payments, fleet management, maintenance tasks, analytics and APIs. Its ride-hailing software includes passenger and driver apps, dispatch, payments, fleet data, analytics and integrations. The ATOM Mobility API can also exchange data about vehicles, bookings, rides, payments, telemetry and maintenance tasks.
ATOM Mobility does not provide autonomous driving technology. This would come from a specialised AV company, and each project would have its own technical requirements and local approvals. For an AV pilot, ATOM Mobility could work with the fleet company and AV provider on the rider experience, integrations, fleet management and the data needed to measure how the pilot is working.
If you operate a taxi, rental or sharing fleet and want to explore an AV pilot, ATOM Mobility can help plan the booking and fleet-management setup, integrations and metrics you would need to test together with an AV technology partner.
Use test credentials to log in - Phone number: +1 123123123, Code: 777777


Driver App demo credentials - Email: test@atom.com, Password: driver